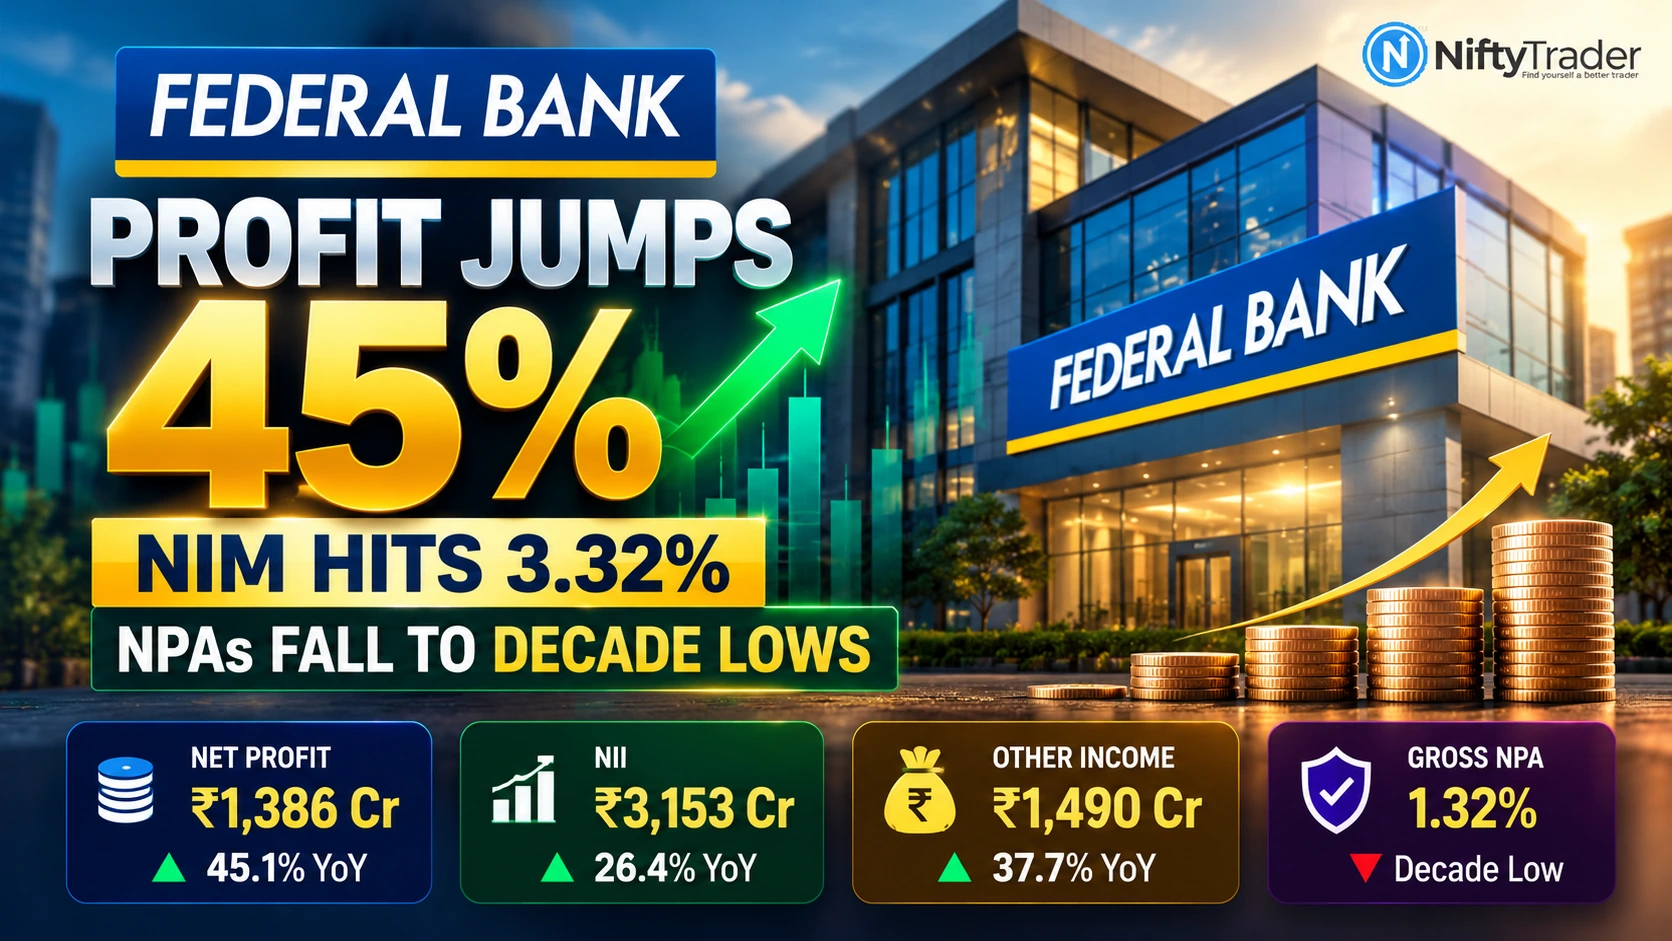
Federal Bank‘s September-quarter profit surged 45.10% year-on-year to a record ₹1,386.09 crore, but the earnings mix deserves a closer look. Net interest income (NII) grew 26.38%, while other income increased 37.73% to a record ₹1,490.44 crore. At the same time, net interest margin (NIM) expanded to 3.32%, and gross and net non-performing asset ratios fell to decade lows, according to the bank’s Q2 FY27 results announcement.
The combination points to stronger core banking income, improved funding economics and better reported asset quality. The key question for investors is whether Federal Bank can sustain this momentum while maintaining margins, growing deposits and keeping credit costs under control.
The bank also disclosed the appointment of Rajesh Varrier as an Additional Director (Non-Executive Independent Director), effective October 16, 2026. Here are the important numbers, the earnings signals and the developments investors should watch next.
Track Live: Federal Bank Option Chain (FEDERALBNK) — Live OI & IV
Federal Bank Q2 FY27 Results: Key Highlights
For the quarter ended September 30, 2026, Federal Bank reported the following standalone performance:
- Net profit: ₹1,386.09 crore, up 45.10% YoY and 17.77% QoQ.
- Net interest income (NII): ₹3,153.40 crore, up 26.38% YoY.
- Operating profit: ₹2,225.37 crore, up 35.35% YoY.
- Net interest margin (NIM): 3.32%, up 26 basis points YoY.
- Other income: ₹1,490.44 crore, up 37.73% YoY.
- Fee income: ₹1,167.71 crore, up 31.86% YoY.
- Gross NPA: 1.32%, down 51 basis points YoY.
- Net NPA: 0.17%, down 31 basis points YoY.
- Gross advances: ₹3,01,687.80 crore, up 21.66% YoY.
- Total deposits: ₹3,42,693.56 crore, up 18.61% YoY.
- CASA ratio: 32.04%, up 103 basis points YoY.
- Return on assets (RoA): 1.32%, up 23 basis points YoY.
The bank described the quarter’s net profit as its highest-ever quarterly profit. The figures are from its October 16, 2026, press release on the unaudited results for the quarter and half-year ended September 30, 2026.
Primary source: Federal Bank’s Q2 FY27 results press release filed with the exchanges.
1. Profit Grows 45%, but What Drove the Earnings Increase?
Federal Bank’s net profit increased from ₹955.26 crore in Q2 FY26 to ₹1,386.09 crore in Q2 FY27. Operating profit rose 35.35% to ₹2,225.37 crore.
Three numbers help explain the performance: NII grew 26.38%, fee income increased 31.86%, and other income rose 37.73%.
The growth in NII is particularly important because it reflects the difference between interest earned on loans and investments and interest paid on deposits and borrowings. Fee income adds another source of revenue beyond interest spreads.
However, other income also reached a record ₹1,490.44 crore. Its increase means investors should examine the detailed composition of non-interest income before assuming that the entire profit growth can be repeated at the same pace.
The distinction is important: a bank can report strong quarterly earnings through a combination of recurring banking income and other revenue items, but those components may not have the same level of predictability.
Federal Bank’s next earnings update will help investors assess whether NII and fee income continue to grow strongly and how the composition of other income evolves.
2. NIM Expands to 3.32% as Funding Costs Decline
Federal Bank’s net interest margin increased from 3.06% in Q2 FY26 to 3.32% in Q2 FY27, an expansion of 26 basis points.
The bank reported a 40-basis-point year-on-year decline in its cost of funds. Its cost of deposits declined 39 basis points to 5.18%.
NII reached ₹3,153.40 crore, growing faster than gross advances, which increased 21.66% year-on-year. This combination suggests that the bank’s interest-income growth was supported by more than just expansion in the loan book.
Lower funding costs can improve the economics of lending, particularly when a bank can maintain its lending yields and manage deposit pricing effectively.
The next test is whether this improvement continues. Competition for deposits, changes in interest rates and the repricing of loans can affect future margins. Investors should therefore monitor NIM alongside deposit growth rather than treating one quarter’s expansion as a permanent trend.
3. Gross and Net NPAs Fall to Decade Lows
Asset quality strengthened during the September quarter.
Federal Bank’s gross NPA ratio declined to 1.32%, while its net NPA ratio fell to 0.17%. The bank described both measures as their lowest levels in a decade.
Fresh slippages declined 27.48% year-on-year, and the slippage ratio improved to 0.59% from 0.94% a year earlier.
The restructured loan book stood at ₹1,389.55 crore, equivalent to 0.46% of gross advances. The provision coverage ratio, excluding technical write-offs, increased to 86.78%, while coverage including technical write-offs stood at 94.49%.
Credit cost declined 19 basis points year-on-year to 0.31%.
These indicators point to an improvement in reported asset quality alongside continued loan growth. Lower slippages and credit costs can support future profitability by reducing the pressure from credit losses.
However, investors should continue tracking fresh slippages, recoveries, write-offs and credit costs. A lower NPA ratio is encouraging, but it does not eliminate the risk of future deterioration as the loan book expands.
4. Advances Cross ₹3 Lakh Crore as CASA Growth Strengthens
Federal Bank’s total business franchise crossed ₹6.4 lakh crore, increasing 20.12% year-on-year.
Gross advances reached ₹3,01,687.80 crore, up 21.66%, while total deposits rose 18.61% to ₹3,42,693.56 crore.
CASA balances increased 22.56% to ₹1,09,803.15 crore, taking the CASA ratio to 32.04% from 31.01% a year earlier. Non-resident deposits reached ₹1,19,055.98 crore, up 26.63%. FCNR(B) deposits increased 239.14% to ₹23,547.72 crore.
A stronger CASA franchise can help a bank manage funding costs because current-account and savings-account deposits generally cost less than many term deposits. The improvement is therefore relevant to the increase in NIM.
But deposit growth remains an important variable. Advances grew faster than deposits during the year, so investors should monitor whether Federal Bank can maintain its lending momentum without facing renewed pressure to offer higher deposit rates.
Which lending segments grew fastest?
The bank reported strong year-on-year growth across several selected businesses:
- Gold loans: 37.13%.
- Loans against property (LAP): 32.21%.
- Credit cards: 28.27%.
- Commercial banking: 25.46%.
- Commercial vehicles and construction equipment (CV/CE): 21.74%.
- Corporate and Institutional Banking: 17.19%.
- Business Banking: 12.39%, returning to growth.
The bank’s expansion across these segments supports the picture of a growing lending franchise. The important consideration is whether growth remains profitable and is accompanied by disciplined underwriting.
5. Operating Efficiency Improves; Capital Adequacy at 16.84%
Federal Bank’s cost-to-income ratio improved by 196 basis points year-on-year to 52.08%. Return on assets increased 23 basis points to 1.32%, while return on equity rose 256 basis points to 13.57%.
The bank reported a capital adequacy ratio (CRAR) of 16.84% and Tier I capital of 15.76%.
These measures add context to the headline profit growth. A lower cost-to-income ratio indicates that operating expenses are taking a smaller share of operating income, while RoA and RoE help show how effectively the bank generates returns from its assets and equity.
Capital adequacy is also important because a bank needs sufficient capital to support further lending and absorb potential losses.
The next question is whether Federal Bank can preserve these operating and return metrics as its business expands.
6. Federal Bank Appoints Rajesh Varrier as Independent Director
In a separate corporate announcement dated October 16, 2026, Federal Bank appointed Rajesh Varrier as an Additional Director (Non-Executive Independent Director) on its board for three consecutive years, effective October 16, 2026.
The appointment was reported in the bank’s corporate-announcement coverage. It is a governance development separate from the Q2 earnings announcement.
The appointment should not be presented as a cause of the quarter’s profit growth or as a direct stock-price catalyst without further evidence. Investors seeking additional context can review the formal exchange disclosure and the director’s profile when available.
Related source: Federal Bank corporate announcements — The Economic Times.
7. Federal Bank Share Price Reaction After Q2 Results
Federal Bank shares traded higher after the results announcement. CNBC-TV18 reported that the stock was up approximately 0.6% at ₹339 around 1:30 pm IST on October 16, 2026.
This is an intraday price snapshot, not the closing price.
The market had several positive results to assess: record quarterly profit, stronger NII, margin expansion, lower NPA ratios and continued deposit growth. However, a positive intraday move does not establish whether the stock is undervalued or whether further gains will follow.
The subsequent closing price, trading volumes, valuation and management’s outlook will be important when assessing the market’s reaction. No analyst-consensus beat is claimed here because a reliable pre-results consensus estimate has not been independently verified.
What Federal Bank’s Q2 Results Mean for Investors
Federal Bank’s Q2 performance combines stronger interest income, improved margins and better reported asset quality. The bank also recorded strong fee-income growth and an improvement in operating efficiency.
But the most useful question is not simply whether profit can grow again by 45%. It is whether the bank can sustain NII growth, preserve its 3.32% NIM, maintain asset quality and continue generating recurring fee income as the balance sheet expands.
Investors should focus on three indicators in the next quarter:
- NIM and funding costs: Whether the bank can preserve its margin as deposit pricing and lending rates change.
- Earnings composition: Whether NII and fee income continue to support profit growth and how other income evolves.
- Asset quality: Whether lower slippages and credit costs persist alongside loan growth.
These measures will provide a clearer picture of the durability of Federal Bank’s earnings momentum than the headline profit increase alone.
Read Next: Q2 FY27 Bank Results: Indian Bank Profit Rises 15% to ₹3,462 Cr; KVB Jumps 37%, UCO Bank 27%
Disclaimer: This article is for informational and educational purposes only. It is not investment advice or a recommendation to buy or sell Federal Bank shares. Financial figures should be read alongside the bank’s official filings.