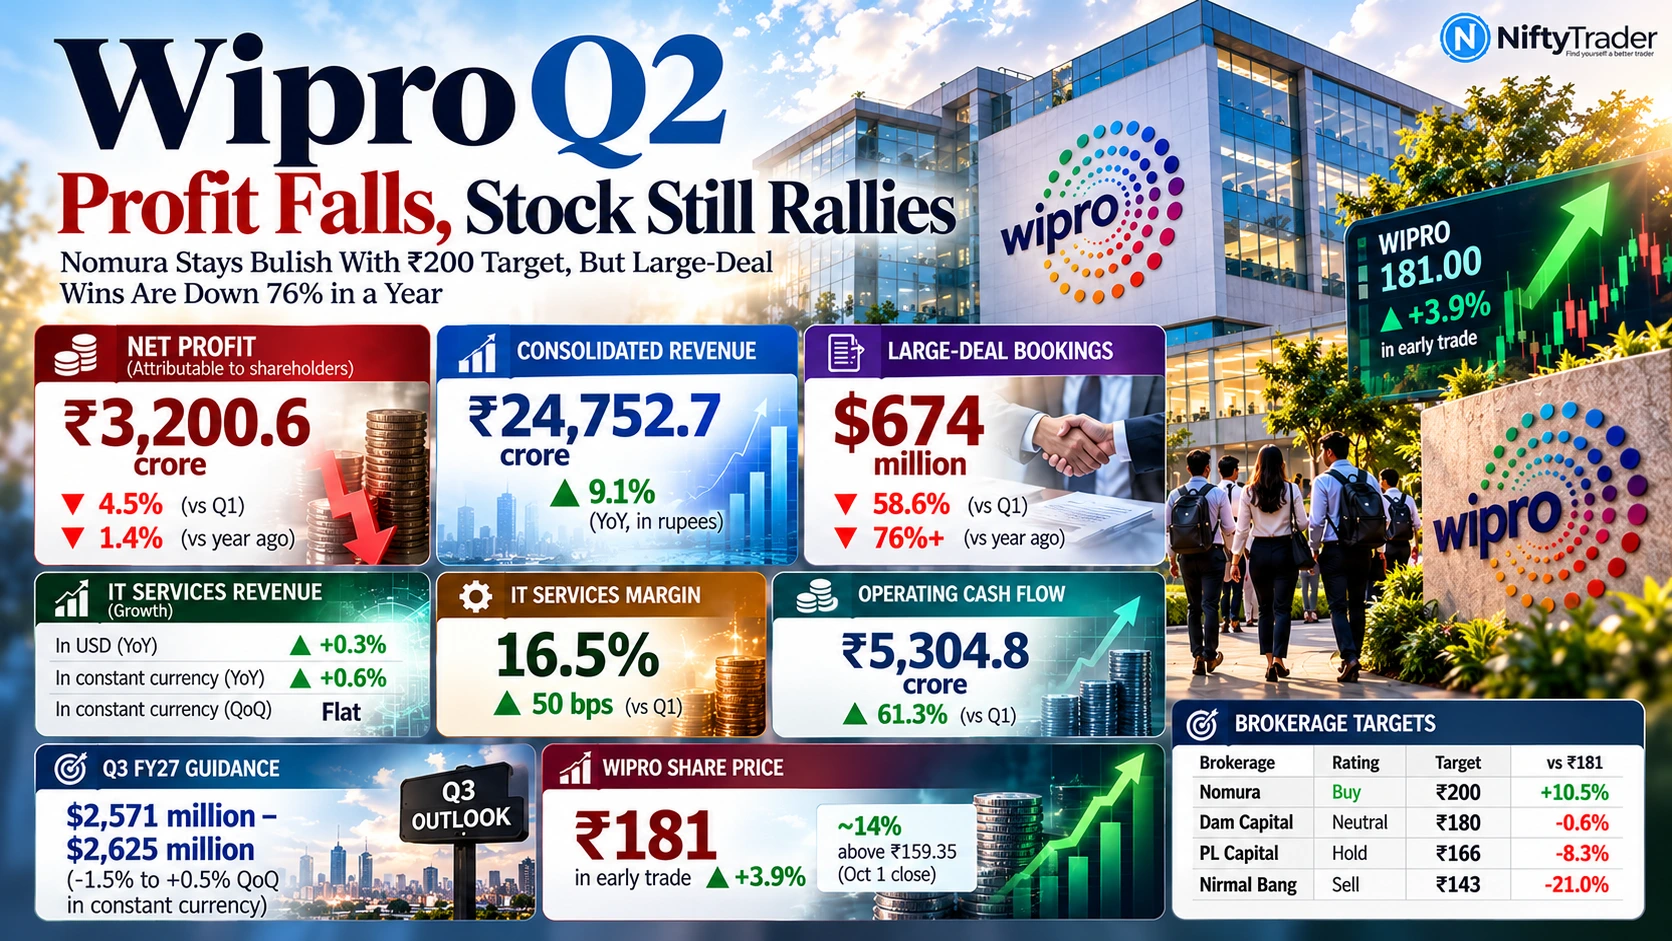
Wipro Q2 FY27 in 60 seconds
- Profit: Rs 3,200.6 crore (attributable to shareholders), down 4.5% from Q1 and 1.4% from a year ago. Total profit for the period fell 1.9%.
- Core growth: IT services revenue was flat sequentially in constant currency and up 0.6% year-on-year. Headline revenue rose 9.1% in rupees.
- Large deals: Bookings were $674 million, down 58.6% from Q1 and down more than 76% from a year ago.
- Margin: IT services margin rose 50 bps to 16.5%.
- Q3 outlook: Guidance is -1.5% to +0.5% sequentially in constant currency.
- Nomura: Buy, Rs 200 target. That is 14.9% above Thursday’s close of Rs 174.05 and about 10.5% above Friday’s early price of about Rs 181.
Wipro’s shares are rallying on a quarter in which its large-deal wins fell by more than three-quarters year-on-year. That tension explains why Nomura’s Rs 200 target and the lowest target we tracked, Rs 143, sit so far apart.
The shares jumped nearly 4% in early trade on Friday to around Rs 181, their highest level in over a month. That is about 14% above the Rs 159.35 close on October 1. The stock is still down roughly a third in 2026.
Why Wipro Shares Rose Despite a Profit Dip
Profit missed. Wipro’s Rs 3,200.6 crore was about 1.5% below the CNBC-TV18 poll estimate of Rs 3,248.6 crore. Three things worked in its favour:
- A low bar: Before the results, Jefferies expected a 1.4% sequential decline in constant-currency IT services revenue, Motilal Oswal 0.5% and Nuvama 1%. Wipro reported flat revenue.
- Sector relief: IT stocks rallied broadly. Tech Mahindra rose 4.5% and the Nifty crossed 23,100, and Wipro’s US-listed shares jumped 5% to a near two-month high the day before. Part of the rally reflects the sector, not Wipro alone.
- Management’s tone: Executives voiced strong confidence in Q3 bookings, pointing to deals that have yet to close.
Track Live: Wipro Option Chain (WIPRO) — Live OI, IV, Greeks & PCR
The Growth Gap: 9.1% Headline vs 0.6% Core
| Revenue measure | Q2 FY27 |
|---|---|
| Consolidated revenue (rupees), YoY | +9.1% |
| IT services revenue (US dollars), YoY | +0.3% |
| IT services revenue (constant currency), YoY | +0.6% |
| IT services revenue (constant currency), QoQ | Flat |
Consolidated revenue came in at Rs 24,752.7 crore. Reuters said that it edged past the LSEG average estimate of 246.27 billion rupees. The beat was about 0.5%.
The 9.1% figure should not be read as demand growth. In dollar terms, IT services revenue rose just 0.3% year-on-year. The gap is mostly currency translation, since a weaker rupee inflates revenue reported in rupees. The 0.6% constant-currency growth also includes acquired revenue, so organic growth is likely lower. Sequential growth was led by Consumer and BFSI, while Healthcare and Tech & Comms stayed weak.
Large-Deal Wins Are Down 76%: The Number Behind the Rally
A year ago, Wipro reported $2.9 billion in large deals and $4.7 billion in total bookings.
| Bookings | Q2 FY27 | vs Q1 (constant currency) | vs year ago |
|---|---|---|---|
| Large deals | $674 million | -58.6% | Down more than 76% |
| Total bookings | $2.595 billion | -22.9% | Down about 45% |
Reuters called the total an almost four-year low. Wipro signed nine large deals, and management said two deals slipped into Q3 because of paperwork delays, with neither lost. Nirmal Bang points out that the same explanation was offered after Q1 without the deals converting, and that Wipro’s conversion of deal value into revenue is already the weakest among peers.
Margins Recover to 16.5%, With a Rupee Assist
The IT services margin improved 50 bps from Q1, but it was 20 bps lower than a year earlier. Management credited operational improvements and rupee depreciation, partly offset by continuing investments. The rupee is outside Wipro’s control, so investors should not assume it will keep helping. The margin is still below the 17% level the company is working towards.
Cash flow was a bright spot. Operating cash flow was Rs 5,304.8 crore, or 165.8% of net profit, and 61.3% higher than in the previous quarter.
Wipro Q3 Guidance: What the Range Hides
Wipro guided to $2,571 million to $2,625 million for the December quarter, citing furloughs and fewer working days. Reuters said the range was modestly ahead of analysts’ expectations of a decline of up to 2% or flat.
The detail is in the mix. Nirmal Bang says the unchanged band now includes a full quarter of Mindsprint and the Alpha Net acquisition, implying minimal or negative organic growth.
Wipro Share Price Target: Nomura’s Rs 200 vs the Rest of the Street
Nomura kept its Buy rating. MarketScreener’s tracking shows it cut its target to Rs 200 from Rs 250 on July 1, and to Rs 190 on July 17. Rs 200 is therefore above its post-Q1 level.
| Brokerage | Rating | Target | vs Rs 181 |
|---|---|---|---|
| Nomura | Buy | Rs 200 | +10.5% |
| Dam Capital | Neutral | Rs 180 | -0.6% |
| PL Capital | Hold | Rs 166 | -8.3% |
| Nirmal Bang | Sell | Rs 143 | -21.0% |
Wipro now trades roughly at Dam Capital’s Rs 180 target, so among the post-results targets only Nomura’s sits clearly above the price.
The three post-results calls below Nomura’s come from a Business Standard roundup. PL Capital raised its target from Rs 154, and Dam Capital expects flat FY27 revenue and growth only in FY28 after four years of decline. Ahead of the results, Jefferies had Underperform at Rs 150, Motilal Oswal Neutral at Rs 160 and HDFC Securities Add at Rs 185. From the highest target to the lowest, the gap is nearly 40%.
What to Watch Next
- The two slipped deals: PL Capital says closing them in Q3 could support revenue upside in Q4 FY27.
- Large-deal bookings: After a quarter this weak, another soft print would undercut management’s confidence.
- Organic growth: Q3 will show how much growth comes from acquisitions and how much from the core business.
- Margin without the rupee: Can 16.5% reach 17% without a currency tailwind?
- The sector trade: IT stocks led Friday’s rally. If that relief fades, Wipro’s recent gains are exposed.
Also Check: WIPRO Options Chart | Nifty Trader
Bottom Line
Wipro stabilised revenue and rebuilt some margin, but its order book shrank sharply. The Street’s targets run from Rs 143 to Rs 200 because analysts disagree on one question: will the delayed deals sign and turn into revenue, or will weak signings keep growth subdued? The next quarter’s bookings should settle that.
Read Next: Nifty Near 23,000, but Smallcaps Fall 1.3% as FIIs Sell ₹5,285 Crore: 10 Stocks to Watch Today
FAQs
Why did Wipro shares rise after Q2 results?
Wipro shares rose nearly 4% in early trade on October 16. Revenue edged past estimates, margins improved, cash flow was strong and Wipro’s US-listed shares had jumped the day before. Investors also seemed willing to look past a profit miss and weak bookings.
What is Nomura’s Wipro target price?
Rs 200 with a Buy rating, 14.9% above Thursday’s close of Rs 174.05 and about 10.5% above Friday’s early price of about Rs 181.
How much did Wipro’s large-deal bookings fall?
They fell to $674 million, down 58.6% from Q1 and more than 76% from a year ago.
What is Wipro’s Q3 FY27 revenue guidance?
IT services revenue of $2,571 million to $2,625 million, or -1.5% to +0.5% sequentially in constant currency.
Disclaimer: This article is for information only and is not investment advice. Ratings and targets belong to the brokerages cited. Prices change quickly, so check live data before acting.