The new framework requires real-time margin relief against eligible early-pay-in securities while retaining client-level margin checks and safeguards for reversed trades.
October 22, 2026
The Securities and Exchange Board of India (SEBI) has specified a real-time framework for recognising the value of securities delivered early against sale obligations when calculating margins on clients’ subsequent cash-market positions. The framework takes effect on February 22, 2027.
Under the new rules, clearing corporations must not collect margins from trading members or clearing members on eligible subsequent buy or sell positions up to the value of securities accepted under the early pay-in (EPI) mechanism, subject to the conditions specified in the circular.
The official SEBI circular, issued on October 22, 2026, also sets out how the eligible EPI value must be calculated, how it is adjusted when a sale position is squared off and how resulting margin shortfalls are handled.
The decision follows proposals from the Brokers’ Industry Standards Forum, recommendations from SEBI’s Risk Management Review Committee and the regulator’s internal deliberations.
What changes under the new SEBI circular?
The directive applies when a client has a net sell obligation in a settlement and the clearing corporation has successfully accepted the EPI request for the securities sold.
In those circumstances, the clearing corporation must recognise the eligible EPI value in real time when determining the margin to be collected from the trading or clearing member on the client’s subsequent cash-market positions.
The eligible amount is the lower of:
- The value of securities for which EPI has been made.
- The value of securities sold by the client.
This calculation limits the benefit to the value supported by the relevant securities and sale obligation.
The circular also specifies that, when a client takes a position in the cash segment on the same trading day using the EPI benefit, the clearing corporation must assess the client’s available margin after reducing the eligible EPI value.
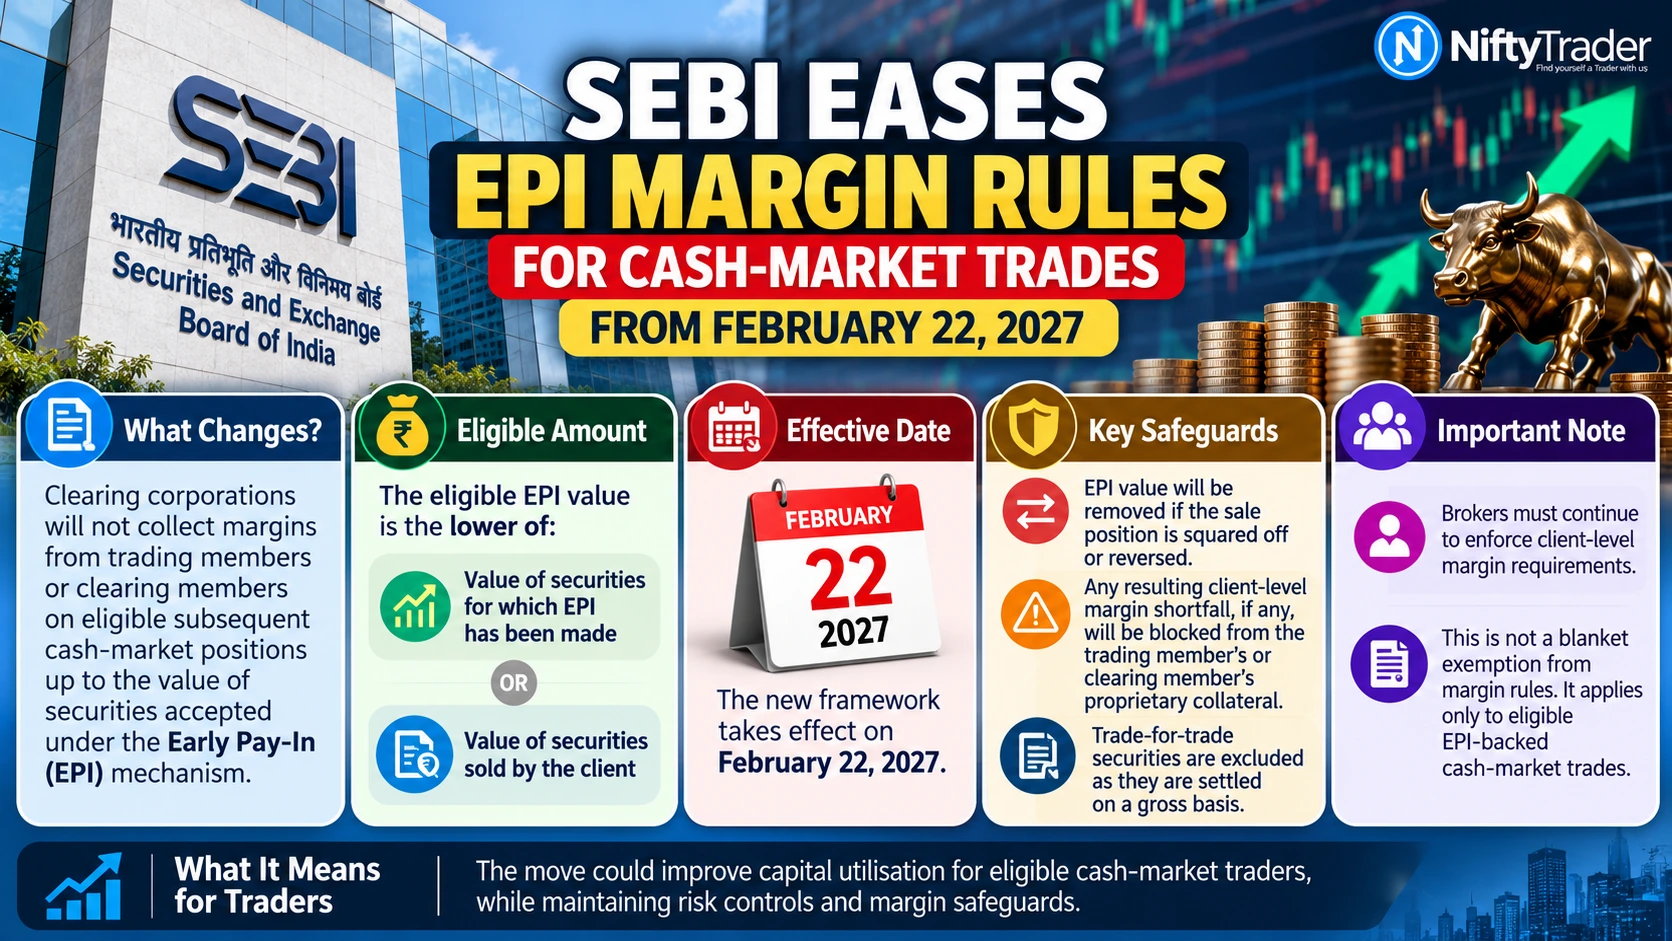
How the new framework differs from existing EPI provisions
The decision does not introduce the use of EPI value for subsequent margin requirements for the first time.
The National Stock Exchange’s existing margin collection and reporting FAQs already allow eligible EPI value to count towards subsequent margin requirements under specified conditions. These include acceptance of the EPI request through the block mechanism and, for the subsequent-margin treatment described in the FAQ, credit of the sale proceeds to the client’s ledger.
SEBI’s new circular expressly establishes a real-time obligation for clearing corporations to refrain from collecting margins from trading or clearing members on eligible subsequent cash-market positions, up to the accepted EPI amount.
It also specifies the trade-date valuation method, the adjustment required when the relevant sale position is reversed and the associated collateral safeguard.
The distinction is important for market participants: the change concerns the explicit clearing-corporation framework and its operational requirements, rather than the first-ever recognition of EPI value for margin purposes.
What does the change mean for traders?
The framework could improve capital utilisation for eligible cash-market traders by reducing the need to provide separate margin funds for subsequent positions to the extent covered by accepted EPI value.
For example, suppose a client sells securities worth ₹1 lakh and the clearing corporation accepts EPI worth ₹80,000. Under the circular’s valuation formula, the eligible EPI value would be ₹80,000.
That amount may support the margin treatment of eligible subsequent positions under the prescribed framework. It does not mean that every subsequent trade worth ₹80,000 can automatically be executed without other applicable margin checks.
The practical benefit depends on the client’s transactions, successful EPI acceptance and the applicable margin requirements.
Why the relief is not a blanket margin exemption
The circular distinguishes between the clearing corporation’s obligation to collect margin from a trading or clearing member and the broker’s responsibility to enforce client-level margin requirements.
SEBI has directed trading members to ensure that their risk-management systems permit clients to square off positions against which EPI benefits have been used or take fresh positions only when the requisite client margins are available.
Consequently, the relief should not be interpreted as permission to trade without sufficient funds or collateral. Brokers must continue to apply the relevant client-level checks.
What happens if the client squares off the sale?
If a client squares off the sale position in securities against which the EPI benefit has been used, the clearing corporation must remove the corresponding EPI value from the margin calculation.
If removing that value creates a margin shortfall at the client level, the clearing corporation will block the shortfall from the proprietary collateral of the trading member or clearing member, as prescribed by the circular.
The circular excludes trade-for-trade securities from this particular condition because those transactions are settled on a gross basis.
These safeguards link the margin benefit to the underlying sale transaction and address the risk that the EPI value may no longer be available to support the client’s positions.
Why the change matters for the Indian market
For eligible traders, the framework may reduce the duplication of capital used to meet margin requirements after securities have been delivered early. For brokers and clearing corporations, it provides a defined method for calculating the benefit, adjusting it when positions change and managing resulting shortfalls.
However, the circular does not quantify the potential effect on market turnover, investor participation or brokerage funding needs. Those outcomes will depend on implementation and market behaviour.
The immediate significance is operational: clearing corporations must apply the prescribed real-time treatment, while trading members must maintain controls that ensure clients meet applicable margin requirements.
What should traders and brokers watch next?
The new framework is scheduled to take effect on February 22, 2027, four months after the circular’s issuance.
Before implementation, market participants should monitor further instructions from stock exchanges and clearing corporations, including any amendments to their rules, system changes or operational procedures.
SEBI’s circular specifically directs clearing corporations to make necessary amendments to relevant rules and regulations, implement system changes where required and publish the provisions on their websites.
For traders, the key consideration is whether their broker’s systems correctly recognise accepted EPI value and continue to enforce required margins when subsequent positions are taken or the underlying sale is reversed.
Bottom line
SEBI has specified a real-time framework for margin relief against eligible early-delivered securities, but the benefit remains conditional and does not remove the requirement to maintain sufficient client margins.
Read Next: KEI Industries Shares Falls 11% Intraday Despite 39% Q2 Revenue Growth; Futures OI Diverges
Disclaimer: This article is for informational and educational purposes only and is based on SEBI’s circular and publicly available information. It does not constitute investment advice, a recommendation to buy or sell securities, or a guarantee of margin availability. The applicability of EPI benefits is subject to SEBI regulations, clearing corporation procedures and broker-level margin requirements. Readers should verify the latest official circulars and consult their broker for transaction-specific details. NiftyTrader is not responsible for investment decisions made on the basis of this article.