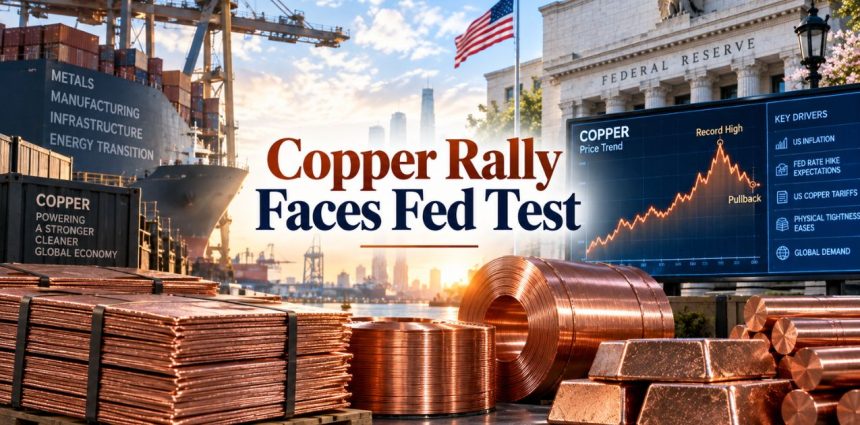
Copper is losing momentum just as the market faces a new question: can the metal’s supply-and-demand story overcome a stronger dollar, higher rate expectations, and uncertainty over US tariffs?
Copper’s record rally is running into a new problem: the macro backdrop is turning against it just as the physical-market squeeze that drove the rally starts to ease.
London Metal Exchange copper slipped on Monday after firmer-than-expected core US inflation strengthened expectations that the Federal Reserve could raise interest rates this week. By 10:05 a.m. Singapore time, LME copper was down 0.3% at around $14,193 a tonne, adding to a pullback that followed last week’s record high near $14,875.
The move matters because copper had been trading on an almost entirely different narrative: tight physical supply, expectations of US tariffs on refined metal, mine disruptions, and rapidly rising demand from data centres, power infrastructure, and renewable-energy projects.
Now the trade is being challenged by two forces at once: higher US yields and less certainty around tariffs.
That creates a critical question for copper traders: is this just a pause after a record run, or the start of a deeper reset?
US inflation has changed the near-term copper equation
The immediate trigger is US inflation, though it’s worth being precise about where the surprise actually was.
The August Consumer Price Index rose 0.4% month-on-month and 3.4% year-on-year, both in line with economist expectations. The real surprise was in core CPI, which, stripped of food and energy, rose 0.3% in August, a tenth of a point hotter than forecast and its strongest monthly gain since April. Core inflation was 2.4% over the year. Gasoline prices alone jumped 3.9% for the month.
Producer inflation had already added to the concern. The US Producer Price Index rose 0.4% in August, with final-demand prices up 5.4% year-on-year. Final-demand goods prices jumped 1.1%.
Together, those numbers have pushed traders to rethink the Fed’s next move.
Market pricing put the probability of a 25-basis-point Fed rate hike at about 87% ahead of this week’s meeting, up sharply from earlier levels. Goldman Sachs has now shifted to a 25-basis-point September hike call, reversing its earlier no-change forecast, putting it alongside JPMorgan Wealth Management, which had already been positioned for a hike since early August.
The Federal Open Market Committee is scheduled to meet on September 15-16, with its policy decision and press conference due on September 16.
For copper, that is uncomfortable.
Higher interest rates tend to support the dollar and raise the opportunity cost of holding assets that do not generate interest income. That can pressure industrial metals, particularly when speculative positioning is already elevated.
Also Read: US Jobs Report Lifts September Rate-Hike Expectations, Dow, S&P 500 and Nasdaq Slide
But copper’s rally was never only a Fed story
The bigger reason copper has climbed so far is that the market has been pricing a physical supply problem.
LME copper reached a record around $14,875 a tonne last week before reversing sharply, with the market growing vulnerable to profit-taking after a huge run.
That is an important change.
During the earlier rally, buyers were willing to pay increasingly large premiums for metal available immediately, the cash-to-three-month spread widened to as much as $545 a tonne earlier this month, the widest backwardation since the 2021 squeeze. By Monday, that premium had all but vanished: LME data showed spot copper commanding just a $4.50-a-tonne premium over three-month metal, according to Bloomberg. The extreme premium for immediately available metal had largely disappeared.
In other words, copper’s physical market still looks tight in important regions, but the emergency bidding for immediate metal has cooled sharply.
The US tariff trade is creating an unusual distortion
This may be the most important part of the copper story that the simple “Fed hikes, copper falls” explanation misses.
Traders had been moving large amounts of copper into the United States in anticipation of tariffs on refined imports. That strategy pushed US inventories higher while tightening availability elsewhere.
But Washington has now delayed a decision on refined-copper tariffs, with affordability concerns becoming a major issue. The US remains heavily dependent on imported copper and has only two operational copper smelters, meaning broad tariffs could raise costs for manufacturers using the metal.
That delay changes the market equation.
The original expectation was straightforward: tariffs would make US copper more expensive, encouraging stockpiling and creating tighter supply outside America.
Instead, traders are now facing a policy vacuum.
The tariff has not disappeared. The certainty around the tariff has disappeared.
That distinction matters because copper had already rallied in anticipation of the policy.
Record prices meet a more difficult demand test
Copper still has a compelling long-term demand story.
The metal is essential for electricity networks, power generation, electric equipment, renewable infrastructure, and data-centre construction. The AI buildout is particularly important because data centres require large amounts of electrical infrastructure, including copper-intensive wiring and grid connections.
The supply side is also difficult to expand quickly. Mine disruptions and lower output in several producing regions have kept investors focused on the possibility of a structural deficit.
That creates the market’s central tension:
| Bullish copper argument | Bearish near-term pressure |
|---|---|
| Data-centre and grid demand | Higher US interest-rate expectations |
| Mine disruptions | Stronger dollar |
| Tight inventories outside the US | Tariff decision delayed |
| Long lead times for new mines | Speculative positioning being reduced |
| Electrification demand | High copper prices could slow marginal demand |
The result may be a more volatile market rather than an outright bearish one.
Sucden Financial analysts said copper could remain choppy around current levels while the market waits for a stronger dip-buying or a fresh macro or fundamental catalyst.
Why the next move could be bigger than Monday’s decline
Copper’s first weekly decline since June was a sign that the rally had become increasingly vulnerable to profit-taking after its strong run. The latest pullback adds another layer: the Federal Reserve is suddenly becoming a bigger part of the copper trade.
That means three events now matter more than simply watching the headline copper price.
First, the Fed. A hike is increasingly priced, but the market will pay close attention to the Fed’s guidance on whether another move could follow later in the year.
Second, the dollar and US bond yields. If yields continue moving higher, the pressure on industrial metals could intensify even without a major change in physical copper demand.
Third, US copper policy. Any decision on refined-copper tariffs could abruptly reverse global flows again. A broad tariff announcement could revive the stockpiling trade, while a softer outcome could remove one of the biggest speculative supports behind the recent rally.
The expectation gap traders should watch
Copper entered September with investors largely focused on scarcity.
It is entering this week with the market suddenly forced to think about money, policy, and demand destruction as well.
That does not automatically invalidate the long-term copper bull case. But it raises the risk that prices were running ahead of the immediate fundamentals.
The uncertainty is therefore not whether copper has a structural role in electrification and AI infrastructure. It clearly does.
The bigger uncertainty is how much of that future demand has already been priced into a market that recently touched $14,875 a tonne.
For traders, the $14,000 area could become an important level to watch. A sustained recovery above the record range would suggest the structural supply story is overpowering macro pressure again. A deeper break lower, particularly alongside rising yields and a stronger dollar, would indicate that the Fed and tariff uncertainty are becoming the dominant forces.
What to watch next
The immediate focus is the September 16 Fed decision, followed by any fresh signal from Washington on refined-copper tariffs.
Copper’s next move may ultimately depend on which story wins: a world that needs much more copper, or a market where high prices, higher rates, and policy uncertainty finally start forcing buyers to step back.
Market caution: Copper remains highly sensitive to interest rates, the US dollar, China demand, inventories, tariffs, and mine-supply disruptions. Short-term price moves can therefore diverge sharply from the long-term electrification story.
Read Next: Global Rates Are Rising. Why India May Feel It Before RBI Hikes
Disclaimer: This article is for informational purposes only and does not constitute investment advice.