A payment to a micro or small supplier made one day past the legal limit can cost a business its deduction, and Form 3CD now makes auditors report it supplier by supplier.
With the tax audit deadline days away, businesses face a detail that is easy to miss. The amended Form 3CD requires reporting of delayed payments to micro and small enterprises under Clause 22 and the resulting disallowance under Section 43B(h). The form also adds transaction-level reporting for loans and deposits, regulatory settlements and share buybacks. Practitioners say the amended form applies in full this year.
Need to Know
- Deadline: Tax audit reports for AY 2026-27 (Form 3CA-3CD or 3CB-3CD) are due September 30, 2026. Unless CBDT issues an official order, taxpayers should treat September 30 as the operative date.
- Extension status: The Rajasthan High Court adjourned the petition to September 28 because CBDT had not filed its reply. No extension has been notified.
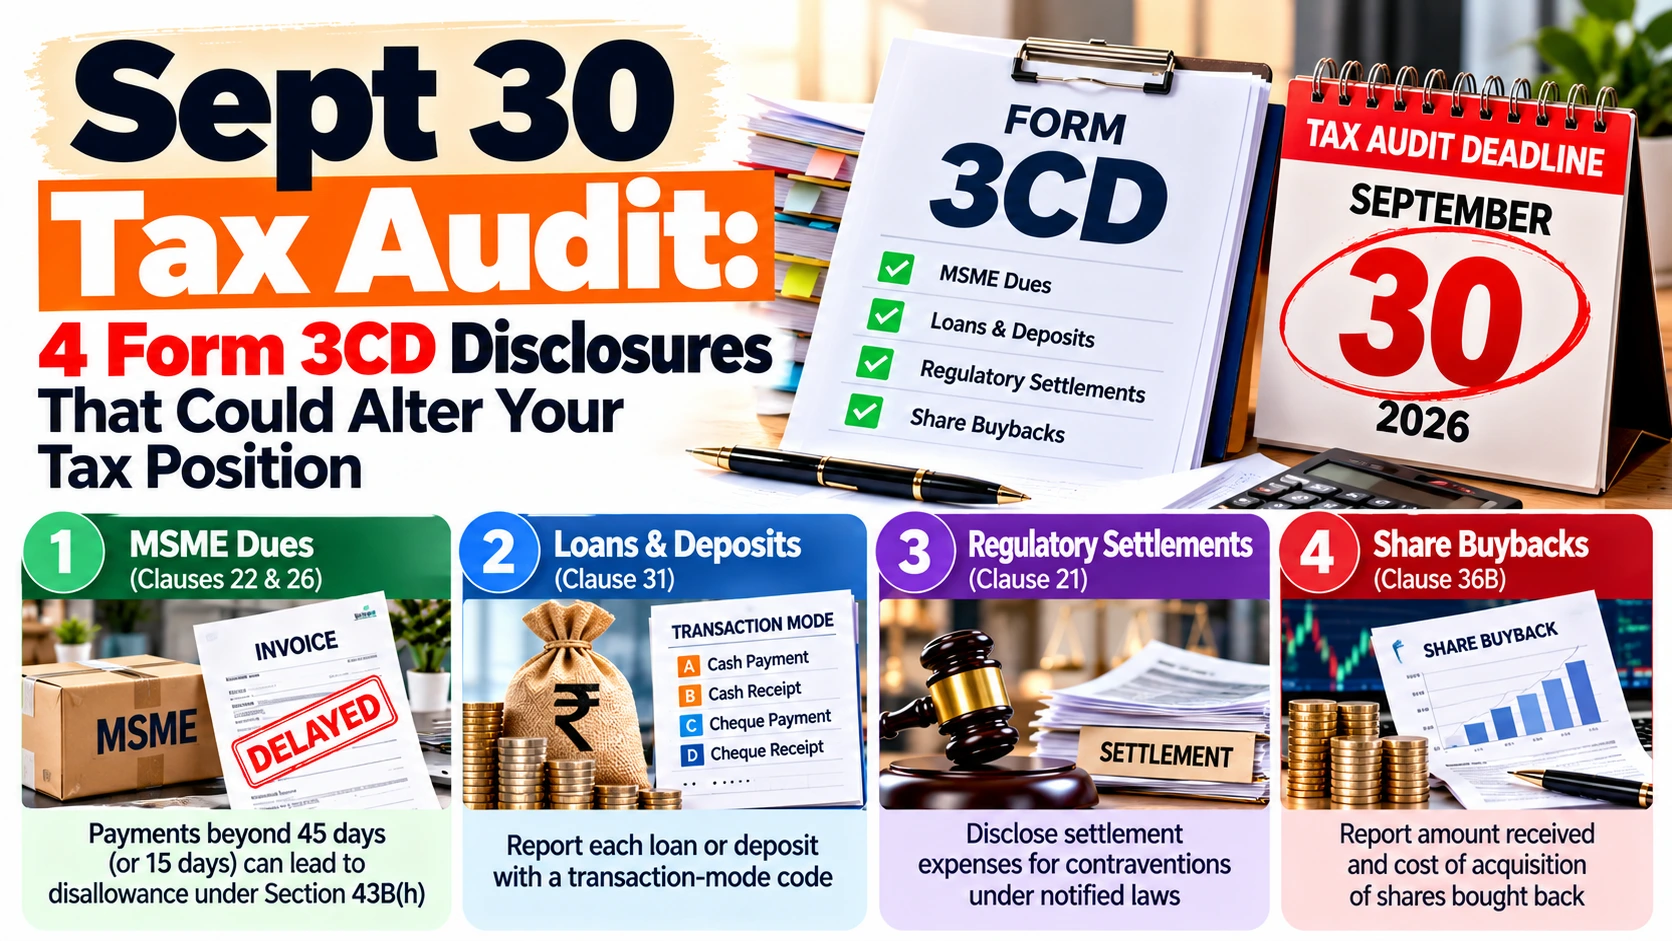
- Four Form 3CD areas: MSME dues (Clauses 22 and 26), loans and deposits (Clause 31), regulatory settlements (Clause 21) and share buybacks (Clause 36B).
- Biggest trap: The MSME payment limit is 45 days where a written agreement exists and 15 days where there is none.
- Penalty for missing the deadline: Section 271B allows 0.5% of turnover or gross receipts, capped at ₹1.5 lakh, subject to reasonable-cause relief under Section 273B.
Also Read: How to Check Income Tax Refund Status in 2026
Will the Tax Audit Deadline Be Extended?
Not yet. The Income Tax Department’s September 22 SMS campaign repeated the September 30 date for AY 2026-27 audit reports. More than 45 associations have sought an extension, and the Rajasthan Tax Consultants Association filed its petition on September 22. The common demand is October 31 for audit reports and November 30 for audit-case ITRs.
There is a precedent. Last year, the Rajasthan High Court directed CBDT to extend the date on September 24, 2025. CBDT then moved the deadline from September 30 to October 31, 2025. A later circular extended it again to November 10, 2025. A request, however, is not an extension. Until CBDT notifies one or a court orders it, September 30 stands.
What Changed in Form 3CD for AY 2026-27?
The changes come from the Income-tax (Eighth Amendment) Rules, 2025, notified on March 28, 2025 and effective April 1, 2025.
| Clause | What must be reported | Records to reconcile |
|---|---|---|
| 22 and 26: MSME dues | Interest inadmissible under the MSMED Act; amounts payable to micro and small enterprises; amounts paid within and beyond the Section 15 limit | Udyam status, invoice and acceptance dates, payment dates, written agreements |
| 31: Loans and deposits | Each loan or deposit taken and each repayment, with a transaction-mode code | Bank entries, journal entries, asset and liability transfers |
| 21: Regulatory settlements | Expenditure incurred to settle proceedings for contraventions under notified laws | Settlement orders, payment proof, accounting entry |
| 36B: Share buybacks | Amount received and cost of acquisition of shares bought back | Buyback statements, contract notes, demat records |
1. MSME Dues: The 15-Day Trap
Under Section 15 of the MSMED Act, payment must be made within the period agreed in writing, which cannot exceed 45 days. Where there is no written agreement, the limit is 15 days. Payments delayed beyond these limits are inadmissible as an expense under Section 43B(h). That disallowance flows into Clause 26. In practice, the deduction shifts to the year of actual payment.
A year-end payable that looks routine in the balance sheet can therefore change the tax computation. For each micro or small supplier, businesses should establish four things:
- whether the supplier qualifies as a micro or small enterprise
- the invoice and acceptance dates
- whether a written agreement exists
- the actual payment date
2. Loans and Deposits: Every Entry Gets a Code
Clause 31 now asks for each loan or deposit taken and each repayment, along with a code for the nature of the transaction.
| Code | Mode | Code | Mode |
|---|---|---|---|
| A | Cash payment | G | Conversion of assets |
| B | Cash receipt | H | Conversion of liabilities |
| C | Non-account-payee cheque payment | I | Journal entry (debit) |
| D | Non-account-payee cheque receipt | J | Journal entry (credit) |
| E | Transfer of asset | K | Any other mode (debit) |
| F | Transfer of liability | L | Any other mode (credit) |
The mode-wise classification brings journal-entry settlements between group entities and director current accounts back into view. Reporting a transaction is not the same as incurring a penalty. Sections 271D and 271E depend on the facts of each transaction, and reasonable-cause relief under Section 273B may apply.
3. Regulatory Settlements: Keep the Paper Trail
Clause 21 adds expenditure incurred to settle proceedings for contraventions under laws notified by the Central Government. Finance and legal teams should be able to connect the settlement order, the payment, the expense booked and its tax treatment. This is a reporting requirement, and the tax treatment is a separate question decided on the applicable provisions and facts.
4. Share Buybacks: Acquisition Cost Now Matters
Clause 36B asks whether the assessee received any amount from a buyback covered by Section 2(22)(f), and if so the amount received and the cost of acquisition. This applies to audited assessees, meaning businesses and professionals under tax audit, not retail investors who are outside the audit net. Those with buyback proceeds in FY 2025-26 need contract notes, broker statements and demat records to support historic cost.
Also Read: Income Tax 2026-27: Before Paying Capital Gains Tax, Check Whether You Have an Unused Exemption
The Final Check Before Upload
Before the report goes up, confirm that books of account = tax computation = Form 3CD disclosures. A mismatch is not automatically a violation, but it can trigger queries at processing or assessment.
Which Form Applies: 3CD or Form 26?
For AY 2026-27, use Form 3CA-3CD or 3CB-3CD under the Income-tax Act, 1961. The consolidated Form 26 applies to Tax Year 2026-27 and is due September 30, 2027.
What to Watch Next
Two outcomes are possible in the next 48 hours.
- If CBDT or the court extends the date: Expect October 31 for audit reports and November 30 for audit-case ITRs, as associations have sought. The reconciliation work does not disappear; it only moves.
- If nothing changes: Firms that left MSME ageing, journal-entry classification and buyback records to the last day will have the narrowest window.
Read Next: Bank Strike Deferred: Banks Open Today, 5-Day Week Pending
FAQ: Tax Audit Deadline and Form 3CD
What is the tax audit deadline for AY 2026-27?
September 30, 2026 for ordinary audit cases. Transfer-pricing cases have a separate date.
Has the tax audit deadline been extended?
No extension has been notified. The matter is before the Rajasthan High Court, but a petition does not change the date.
What is the MSME payment limit under Section 15?
It is 45 days at most where a written agreement exists, and 15 days where there is none.
Does a journal entry in Clause 31 attract a penalty?
Not automatically. Penalties under Sections 271D and 271E depend on the facts and statutory conditions.
Do investors have to report buybacks in Form 3CD?
Only assessees whose accounts are subject to tax audits.
Sources: Income Tax Department guidance for AY 2026-27; CBDT Notification No. 23/2025; Form 26 FAQs. This article is for information and is not tax advice. Consult your Chartered Accountant.