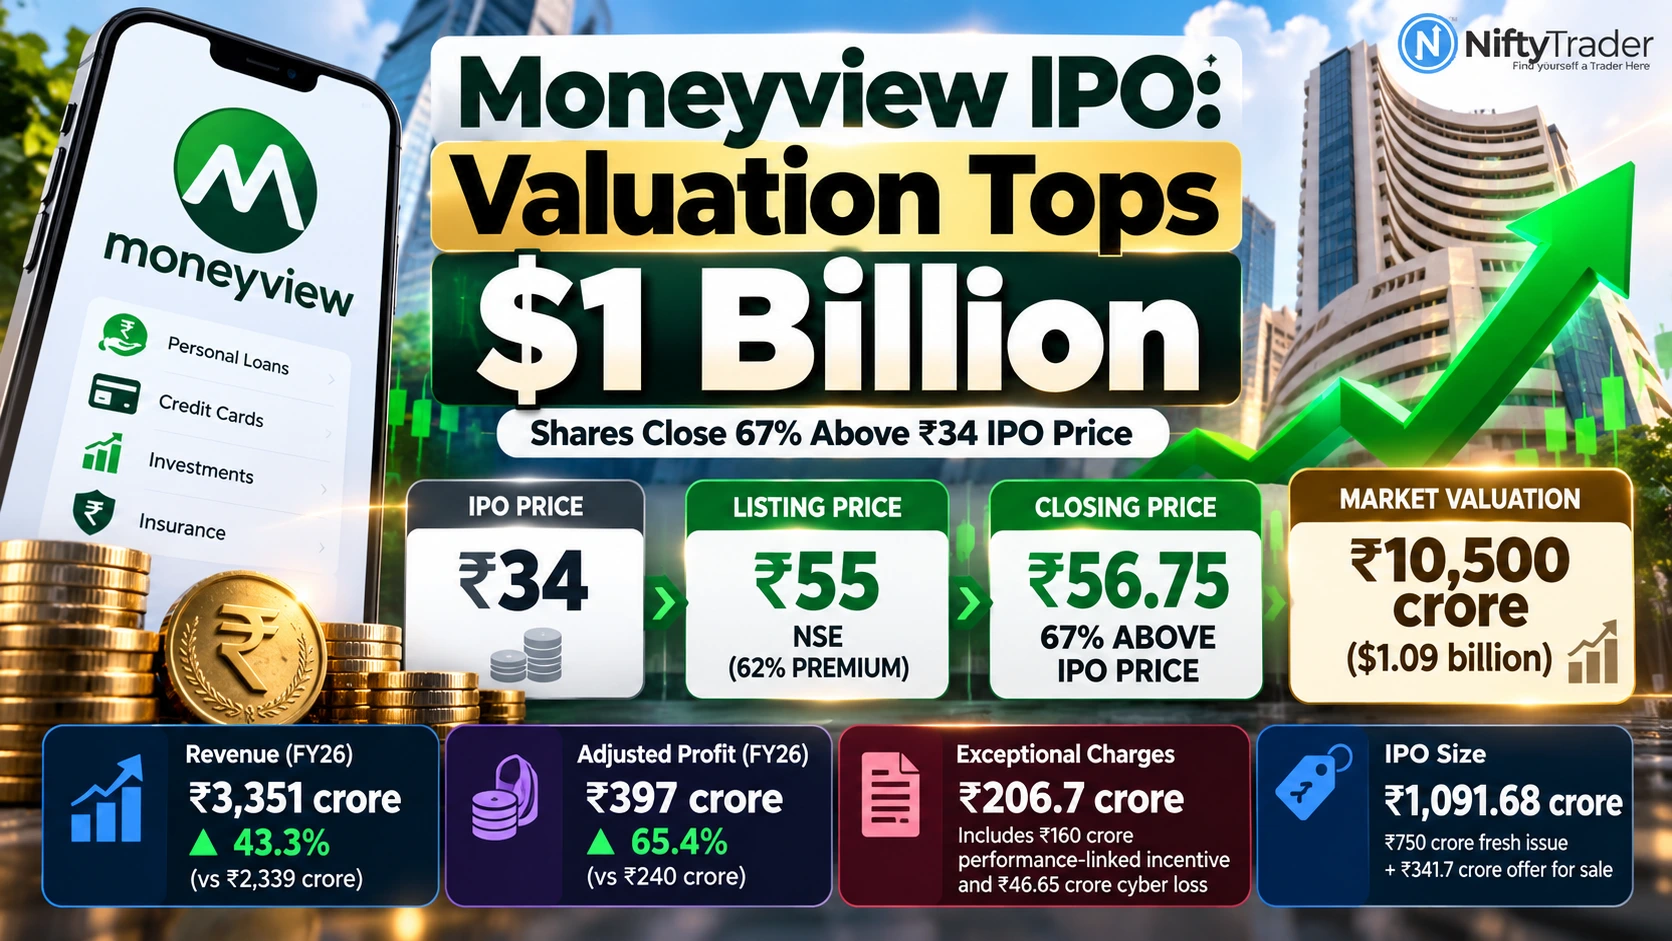
Moneyview shares closed 67% above the ₹34 IPO price at ₹56.75 on October 1, taking the fintech’s market value to about ₹10,500 crore or $1.09 billion. FY26 adjusted profit rose 65.4%, but rising impairment and DLG costs create a higher earnings bar after the sharp valuation reset.
Moneyview’s stock-market debut has done more than deliver a 67% gain over its IPO price.
It has reset the valuation investors are now placing on the fintech.
Moneyview shares opened at ₹55 on the NSE and ₹55.61 on the BSE against the ₹34 issue price. The stock climbed as much as 76% during the session before closing at ₹56.75, up about 67% from the IPO price, according to Reuters. The closing price put the company’s market valuation at approximately ₹10,500 crore ($1.09 billion).
That is substantially above the roughly ₹5,985 crore ($624 million) valuation implied by the IPO’s upper price band.
But the more important number may be hidden inside Moneyview’s FY26 profit.
Reported FY26 PAT rose only about 1% to ₹242.7 crore. Yet after accounting for ₹206.7 crore of exceptional charges, profit before exceptional items rose 65.4% to ₹397.3 crore.
That creates the central question after the listing:
Can Moneyview continue delivering enough underlying earnings growth to support the much higher valuation now assigned to the stock?
The answer will depend not only on revenue and profit growth but also on credit costs, DLG expenses, managed AUM and asset quality.
Track Live: Moneyview IPO
Moneyview share price: ₹34 IPO to ₹56.75 close
Moneyview’s IPO price band was ₹32–₹34 per share, with the company valued at about ₹5,985 crore at the upper end.
The ₹1,091.68-crore IPO comprised a ₹750-crore fresh issue and an offer for sale of about ₹341.7 crore.
On Thursday, Moneyview listed at:
- ₹55 on NSE, a 61.76% premium to the ₹34 IPO price
- ₹55.61 on BSE, a 63.56% premium
- ₹56.75 closing price, about 66.9% above the IPO price
The stock touched an intraday high of about ₹62, taking the maximum gain from the IPO price to roughly 82%.
At ₹56.75, Reuters reported a market valuation of approximately ₹105 billion, or $1.09 billion.
The shift is significant.
At the IPO price, Moneyview was being valued at about ₹5,985 crore. At the first-day closing price, the reported market value was around ₹10,500 crore.
That means the public market has assigned Moneyview a valuation roughly 75% higher than its IPO-stage valuation.
The stock’s first-day move is therefore only part of the story. The bigger change is the earnings expectation embedded in the new valuation.
The ₹397 crore profit number investors should watch
Moneyview’s FY26 headline PAT can make the company’s earnings trajectory look unusually weak.
Revenue from operations increased 43.3% to ₹3,351.2 crore from ₹2,339.1 crore in FY25.
Yet reported PAT increased only from ₹240.3 crore to ₹242.7 crore.
The reason was the exceptional charge of ₹206.7 crore recorded during FY26. On an adjusted basis, Moneyview’s profit before exceptional items increased to ₹397.3 crore, representing 65.4% growth from ₹240.3 crore in FY25.
The exceptional items included a ₹160 crore performance-linked incentive and a ₹46.65 crore cyber-incident loss.
This distinction matters when looking at the stock after its listing.
Using the IPO-stage valuation of about ₹5,985 crore and FY26 adjusted profit of ₹397.3 crore, a simple NiftyTrader calculation gives a valuation of roughly 15 times adjusted FY26 profit.
At the ₹56.75 closing price and Reuters’ approximately ₹10,500-crore market valuation, the same calculation rises to roughly 26 times adjusted FY26 profit.
These are arithmetic valuation ratios based on reported market value and adjusted profit, rather than company-reported P/E figures.
In other words, the market has not merely rewarded Moneyview for its existing earnings.
It has substantially increased the price being paid for those earnings.
Also Check: Latest IPO News & Updates
Why the $1 billion valuation needs context
Moneyview crossed the $1 billion mark in public trading after entering the IPO at a valuation of about $624 million.
However, the public-market valuation should not be treated as directly comparable with a private funding valuation.
Moneyview had reached unicorn status in 2024 at a reported private valuation of around $1.2 billion.
At approximately $1.09 billion after its first-day close, the company is therefore above the $1 billion threshold but still below that reported 2024 private valuation.
That makes the more relevant comparison the move from the IPO’s ₹5,985-crore valuation to roughly ₹10,500 crore after listing.
The public market has effectively repriced the company before investors have seen several quarters of post-listing results.
That creates an expectation gap.
Q1 FY27 gives the re-rating an earnings cushion
Moneyview does have a strong recent earnings trend behind the listing.
For Q1 FY27, operating revenue increased 50.2% year on year to ₹1,041.1 crore, while PAT jumped 158.8% to ₹173.8 crore from ₹67.2 crore. EBITDA increased 88.1% to ₹424.3 crore.
The business also expanded during the quarter.
Loan disbursals rose 40.3% to ₹7,152 crore, while managed AUM increased 27.2% year on year to ₹22,520.2 crore as of June 30, 2026.
Fee and commission income, Moneyview’s largest revenue stream, grew 61.5% to ₹632.9 crore and accounted for 60.8% of operating revenue.
Interest income increased 36.9% to ₹387.2 crore.
These figures provide a stronger earnings backdrop for the listing than the 1% FY26 reported-PAT growth alone suggests.
But Q1 also creates a new challenge.
At ₹173.8 crore, quarterly PAT was already substantial relative to FY26 reported profit of ₹242.7 crore. The market now needs to see whether this level of earnings can be sustained rather than assuming that one strong quarter represents a permanent new run rate.
The valuation has risen faster than AUM
One of the most important differences between the stock-price growth and the underlying operating growth is visible in the latest AUM figures.
Q1 FY27 managed AUM increased 27.2% year on year to ₹22,520.2 crore, while operating revenue increased 50.2%.
That faster revenue growth is positive for operating leverage.
But it also raises a question for future quarters:
Can Moneyview maintain strong revenue growth without credit costs rising at a faster pace?
The answer matters because the business combines lending on its own NBFC balance sheet with loans originated through external lending partners.
Of the ₹22,520.2 crore managed AUM at June 30, around ₹5,657.5 crore was on Whizdm Finance’s books, while ₹16,862.7 crore was serviced for external lending partners.
That asset-light structure can support scale, but it does not remove credit risk from the business model.
Credit costs are the part of the growth story to watch
Moneyview’s Q1 earnings were strong, but impairment and DLG expenses remain important variables.
Impairment expenses rose to about ₹261.4 crore in Q1 FY27, according to the company’s RHP-based financial disclosures. DLG expenses were about ₹101.3 crore during the quarter.
This creates a useful counterpoint to the headline 159% PAT growth.
Revenue increased 50.2%, while impairment expense also remained substantial.
The key question is therefore not simply whether Moneyview can increase AUM.
It is whether it can grow AUM and revenue while keeping credit losses, impairment and DLG expenses under control.
Gross Stage 3 loans at Whizdm Finance were around 2.72% as of June 30, 2026, while net Stage 3 stood at 0.59%.
Those figures need to be monitored alongside future loan growth rather than viewed independently.
IPO proceeds will increase lending capacity
Moneyview raised ₹750 crore through the fresh issue.
The company plans to use:
- ₹325 crore to support loan disbursals under default-loss-guarantee arrangements
- ₹250 crore to augment the capital base of Whizdm Finance
- The balance for general corporate purposes
The allocation means the IPO is not simply a balance-sheet event.
A significant portion of the new capital is intended to support additional lending activity.
That creates another forward-looking test for the company:
Can the additional capital generate faster sustainable earnings without producing a disproportionate increase in credit costs?
The next few quarterly results will provide more evidence.
Check Live: Latest IPO GMP Today (Live IPO Grey Market Premium)
Moneyview IPO demand was exceptionally strong
The stock’s sharp debut followed unusually strong IPO demand.
Moneyview’s ₹1,091.68-crore issue was subscribed 98.46 times overall.
The QIB portion was subscribed 227.45 times, the NII portion 115.41 times and the retail portion 19.57 times.
The strong subscription explains the intensity of investor interest going into the listing, but subscription data alone does not determine the company’s future earnings.
The market’s next test is fundamentally different.
The IPO measured demand for the issue.
The listed market will measure delivery against the valuation.
Five numbers to track after Moneyview’s listing
1. Adjusted profit
FY26 profit before exceptional items was ₹397.3 crore, up 65.4%.
Investors can watch whether underlying earnings continue to grow at a similar pace.
2. Q1 FY27 PAT
Q1 profit reached ₹173.8 crore, up 158.8%.
The uncertainty is whether this growth rate can persist across multiple quarters.
3. Managed AUM
Managed AUM stood at ₹22,520.2 crore in June 2026, up 27.2% year on year.
AUM growth needs to be assessed alongside asset quality and profitability.
4. Credit and DLG costs
Impairment expenses and DLG costs will be critical as the company expands its lending activity.
Faster revenue growth is more valuable if credit costs remain controlled.
5. Operating leverage
Revenue grew 50.2% in Q1 FY27, faster than managed AUM growth of 27.2%.
The market will be watching whether this gap remains favourable or narrows as the business scales.
Moneyview shares: The real test starts after the debut
Moneyview’s first trading day changed the valuation conversation.
The stock moved from an IPO price of ₹34 to a ₹56.75 close, while the company’s reported market value reached approximately ₹10,500 crore, or $1.09 billion.
At the same time, the underlying business has delivered substantial growth.
FY26 revenue rose 43.3%.
Adjusted FY26 profit before exceptional items increased 65.4%.
Q1 FY27 revenue grew 50.2%.
Q1 FY27 PAT surged 158.8%.
Managed AUM reached ₹22,520.2 crore.
Those numbers provide a fundamental basis for the market’s optimism.
But the valuation has also moved sharply.
On NiftyTrader’s arithmetic, the multiple based on adjusted FY26 profit has risen from about 15 times at the IPO valuation to roughly 26 times at the ₹56.75 closing valuation.
That is the expectation gap investors now have to monitor.
Moneyview does not necessarily need to reproduce its Q1 FY27 159% profit growth every quarter. But after the first-day re-rating, the company will need to demonstrate sustained earnings growth, healthy AUM expansion and controlled credit costs.
The listing was the first test. The next test is whether earnings can catch up with the valuation.
Moneyview IPO and Stock: Key Facts
| Metric | Moneyview |
|---|---|
| IPO price | ₹34 |
| Price band | ₹32–₹34 |
| NSE listing price | ₹55 |
| BSE listing price | ₹55.61 |
| October 1 closing price | ₹56.75 |
| Gain vs IPO price | ~66.9% |
| Intraday high | ~₹62 |
| IPO size | ₹1,091.68 crore |
| Fresh issue | ₹750 crore |
| OFS | ~₹341.7 crore |
| IPO subscription | 98.46x |
| QIB subscription | 227.45x |
| FY26 revenue | ₹3,351.2 crore |
| FY26 reported PAT | ₹242.7 crore |
| FY26 adjusted profit before exceptional items | ₹397.3 crore |
| FY27 Q1 revenue | ₹1,041.1 crore |
| FY27 Q1 PAT | ₹173.8 crore |
| FY27 Q1 managed AUM | ₹22,520.2 crore |
| Approx. market value at ₹56.75 | ₹10,500 crore |
| Approx. valuation | $1.09 billion |
Read Next: Why Is the Nifty Falling Despite GST +14.7%, PMI 55.1?
FAQs
What was Moneyview’s IPO price?
Moneyview’s IPO price band was ₹32–₹34 per share, with the issue priced at ₹34 per share at the upper end.
At what price did Moneyview shares list?
Moneyview shares opened at ₹55 on the NSE and ₹55.61 on the BSE on October 1, 2026.
What was Moneyview’s closing price on the listing day?
Moneyview shares closed at ₹56.75 on October 1, 2026, according to Reuters. The closing price was about 67% above the ₹34 IPO price.
What is Moneyview’s valuation after the IPO?
At ₹56.75, Reuters reported Moneyview’s market valuation at approximately ₹105 billion, or $1.09 billion.
Why did Moneyview’s FY26 profit rise only 1%?
Reported FY26 PAT increased to ₹242.7 crore from ₹240.3 crore after the company recorded ₹206.7 crore of exceptional charges. Profit before exceptional items was ₹397.3 crore, up 65.4%.
What was Moneyview’s Q1 FY27 profit?
Moneyview reported Q1 FY27 PAT of ₹173.8 crore, up 158.8% from ₹67.2 crore in Q1 FY26. Operating revenue rose 50.2% to ₹1,041.1 crore.
What are the main risks to watch in Moneyview shares?
Key indicators include adjusted profit growth, managed AUM, impairment expenses, DLG costs, asset quality, partner economics and the sustainability of revenue growth.
How much was Moneyview valued at in its IPO?
At the upper end of the ₹32–₹34 price band, Moneyview was valued at approximately ₹5,985 crore, or about $624 million.
Disclaimer: This article is for informational purposes only and does not constitute investment advice or a recommendation to buy, sell or hold Moneyview shares. Investors should review the company’s official disclosures, financial statements, valuation metrics and risk factors before making investment decisions.