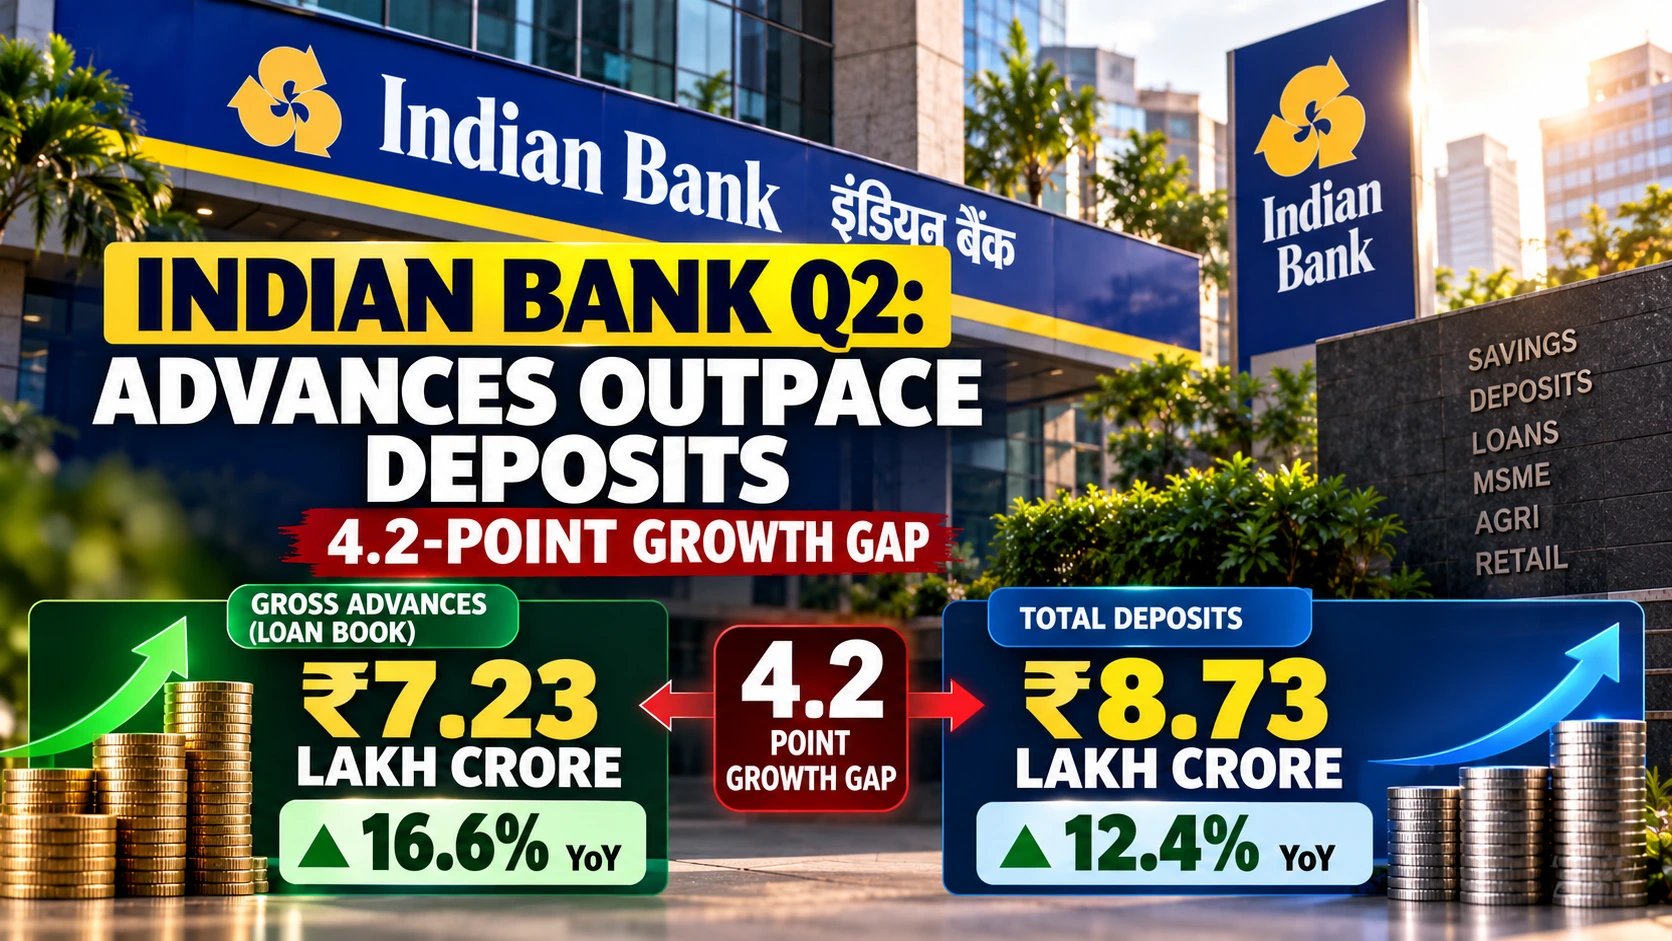
Indian Bank‘s loan book is pulling away from its deposit base. Provisional September-quarter figures show gross advances up 16.6% year on year to ₹7.23 lakh crore, while total deposits grew 12.4% to ₹8.73 lakh crore, a gap of 4.2 percentage points. After the June quarter, management described the gap between the two growth rates as only about 40 basis points. Total business reached ₹15.96 lakh crore, up 14.2%, but how that growth is funded is now the question for the bank’s detailed results.
Advances Accelerate While Deposit Growth Slows
Indian Bank’s provisional business update for September 30, 2026 put total business at ₹15.96 lakh crore, up 14.2% from a year earlier and 4.4% from June. In the quarter alone, gross advances rose 5.5%, while deposits rose 3.4%.
The year-on-year trend shows the shift. In Q1 FY27, advances grew 13.89% and deposits 13.40%, according to management on the June-quarter analyst call. In Q2, advances in growth accelerated by about 2.7 percentage points, while deposit growth slowed by about one point.
What Management Said About the Gap
On the Q1 call, Managing Director and CEO Binod Kumar said the gap between advances and deposit growth needs to stay range-bound, warning that a wide gap starts to affect profitability and net interest margin. He also said he would not mind advances growing 15% if deposits grew 13%, provided margins were not compromised. Q2’s 4.2-point gap is wider than that illustration.
Guidance needs care. Indian Bank has guided to 11–13% advances growth and 9–11% deposit growth for FY27. Those targets cover the year to March 2027, while the Q2 figures measure twelve months to September 30, so the two are not like-for-like. Both Q1 growth rates were also above the guided ranges, so running above guidance is not new. What changed in Q2 is the split between loans and deposits. Any revision to guidance would need a separate announcement from the bank.
NiftyTrader’s calculation from the bank’s rounded figures puts gross advances at about 82.8% of total deposits at September 30, against 81.2% in June and 79.8% a year earlier.
How Peers Compare
Public sector lenders that filed provisional figures on October 1 show the same pattern, but Indian Bank’s gap is narrower than at several of them. Canara Bank‘s advances rose 19.35% against deposit growth of 13.13%, a gap of about 6.2 percentage points. Punjab & Sind Bank reported 19.37% against 12.98%, and UCO Bank 24.68% against 14.05%, gaps of about 6.4 and 10.6 percentage points.
CASA and RAM: What Is Funding the Growth
Indian Bank’s domestic CASA ratio was 39.28% at September 30, down 45 basis points from 39.73% in June but up 41 basis points from 38.87% a year earlier. Management has targeted about 40% for the year. Current account deposits grew 27.5% year on year to ₹0.51 lakh crore, while savings deposits grew 10.8% to ₹2.76 lakh crore, according to the bank’s data.
On the lending side, domestic RAM (retail, agriculture and MSME) advances grew 17.8% to ₹4.43 lakh crore, up 6.2% in the quarter and slightly faster than the overall advances book.
What the Update Does Not Show
The release covers business volumes only. It has no figures for net interest income, margins, profit, slippages or provisions. For reference, after the June quarter the bank reported an annualised credit cost of 0.23%, against a full-year guide of below 1%. Management also said margins had bottomed out but saw no immediate trigger for expansion. Whether faster loan growth changes that picture, particularly if deposits must be raised at a higher cost, will only be visible in the detailed Q2 results.
Option-Chain Snapshot
NiftyTrader’s option-chain snapshot at 4:10 PM IST on October 1 showed Indian Bank at ₹793.15 with an open-interest put-call ratio of 1.12. The heaviest Put open interest sat at the ₹800 strike, just above the spot price, and the heaviest Call open interest at ₹900. NiftyTrader’s reading places the nearest OI resistance at ₹840, with max pain at ₹830. These are positioning data, not guaranteed levels or trading targets, and open interest can change as positions are added, closed or rolled over.
Track Live: INDIAN BANK Option Chain (NSE) — Live OI, PCR & Greeks
What to Watch Next
Indian equity markets were closed on October 2 for Gandhi Jayanti, so the first full trading session since the update is Monday, October 5. After that, the detailed Q2 results will show whether deposit growth can narrow the gap with lending, and whether the CASA ratio recovers towards the 40% target after its sequential dip. They will also show net interest income and margins, asset quality including slippages and credit cost, and whether management changes its FY27 guidance.
Track daily institutional flows in banking stocks on the NiftyTrader FII-DII Tracker at niftytrader.in/fii-dii-data.
Bottom Line
Indian Bank’s September-quarter update shows business growth of 14.2%, but the more important change is that advances growth accelerated to 16.6% while deposit growth slowed to 12.4%. The gap is wider than the roughly 40 basis points management cited a quarter ago, though narrower than at several public sector peers. The provisional figures say nothing yet about margins or asset quality, so the detailed results will decide whether this growth strengthens or strains profitability.
Read also: ₹4,800 Crore FX Shock Hits Indian Banks: Why the Rupee’s Slide Matters Again
Disclaimer: This article is for informational and educational purposes only and does not constitute investment advice or a recommendation to buy, sell or hold any security. Investments in securities markets are subject to market risks. Option-chain open-interest levels are market-positioning indicators, not guaranteed support, resistance or trading targets. Readers should consult a SEBI-registered investment adviser before making any investment decision.