JSW Steel Q2 FY27 Results: Why Analysts Expect Strong Profit Growth
JSW Steel is heading into its second-quarter results with analysts expecting a sharp rise in profitability. Stronger domestic steel prices, resilient demand and healthy sales volumes could support earnings in Q2 FY27, even as higher coking coal costs and seasonal pressure remain concerns.
Brokerage estimates suggest that JSW Steel’s adjusted net profit could increase by 60% to nearly 111% year-on-year. The actual performance, however, will depend on sales realisations, production volumes and cost pressures.
Track Live : NSE Option Chain — Live | BSE Option Chain — Live Sensex & Bankex Options Data Today
JSW Steel Q2 FY27 Results : Firm Steel Prices and Resilient Demand Could Support Earnings
Domestic hot-rolled coil (HRC) and cold-rolled coil (CRC) prices increased approximately 21–22% year-on-year and 3–4% quarter-on-quarter during Q2 FY27. However, primary rebar prices declined around 3% sequentially, while semi-finished steel prices fell approximately 1%.
Elara Capital said steel demand remained resilient, supported by channel restocking ahead of expected price increases. Healthy demand from the pipe sector, improving construction activity after a patchy monsoon and strong automobile demand, particularly for galvanized products, also supported the sector.
These factors could help JSW Steel deliver stronger revenue and profit growth. However, investors will watch whether higher selling prices are sufficient to offset rising input costs.
JSW Steel Q2 FY27 Results: Key Highlights
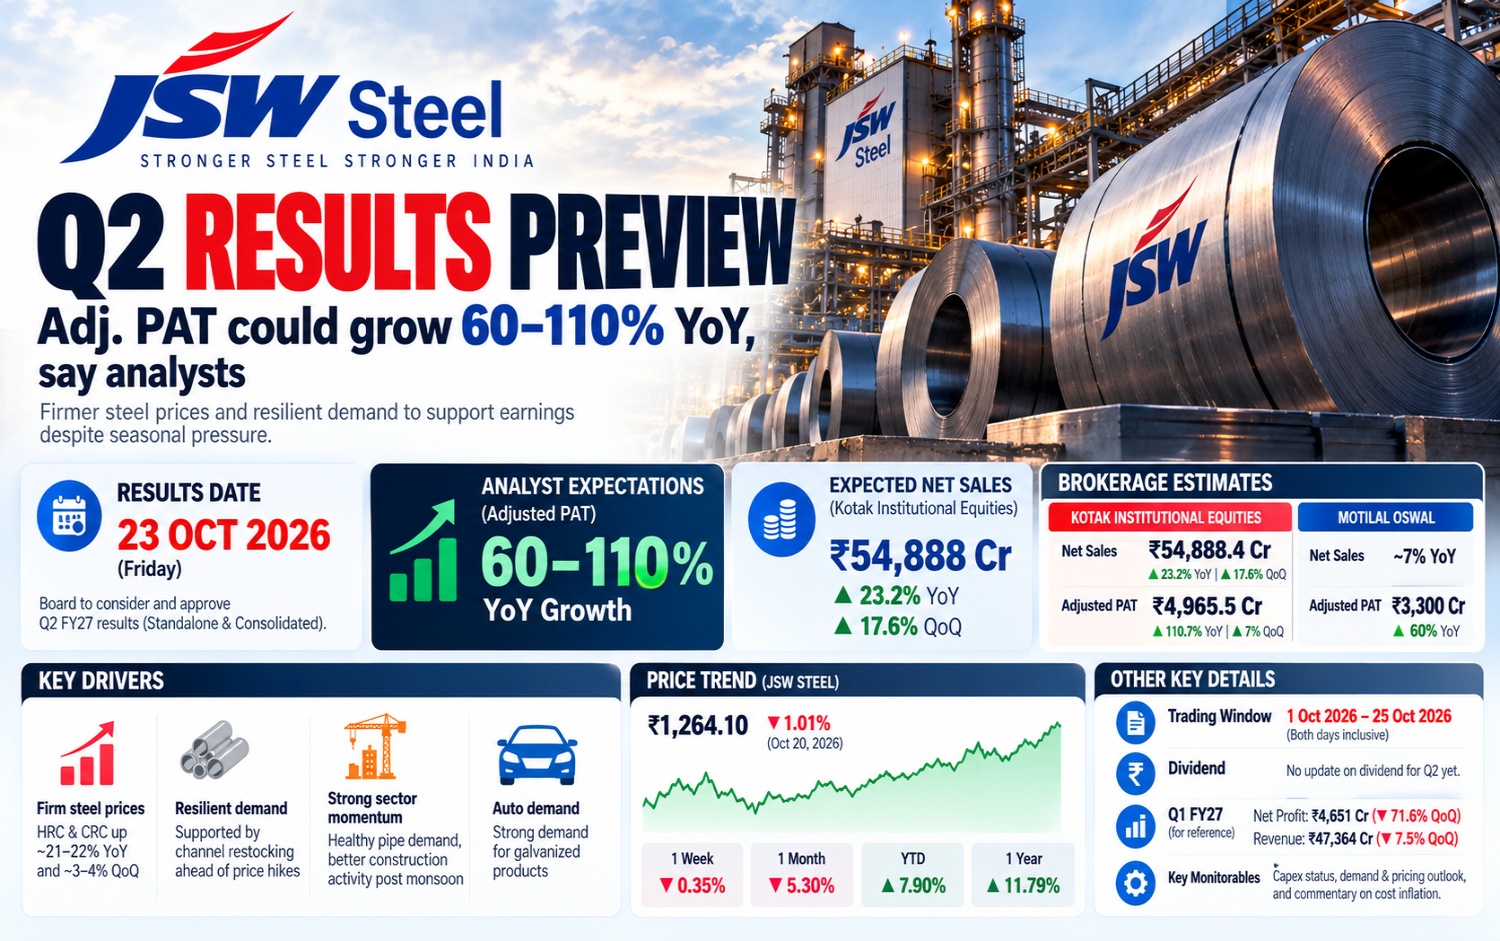
JSW Steel is scheduled to announce its Q2 FY27 financial results on Friday, October 23, 2026. Analysts expect strong year-on-year growth in adjusted net profit, supported by firm steel prices and resilient demand. Kotak Institutional Equities forecasts revenue of ₹54,888.4 crore and adjusted profit after tax (PAT) of ₹4,965.5 crore for the quarter.
| Key Metric | Details |
|---|---|
| Expected Adjusted PAT Growth | 60–110% YoY |
| Results Date | Friday, October 23, 2026 |
| Kotak Estimated Revenue | ₹54,888.4 crore |
| Kotak Estimated Adjusted PAT | ₹4,965.5 crore |
Kotak Expects JSW Steel Profit to Rise 111%
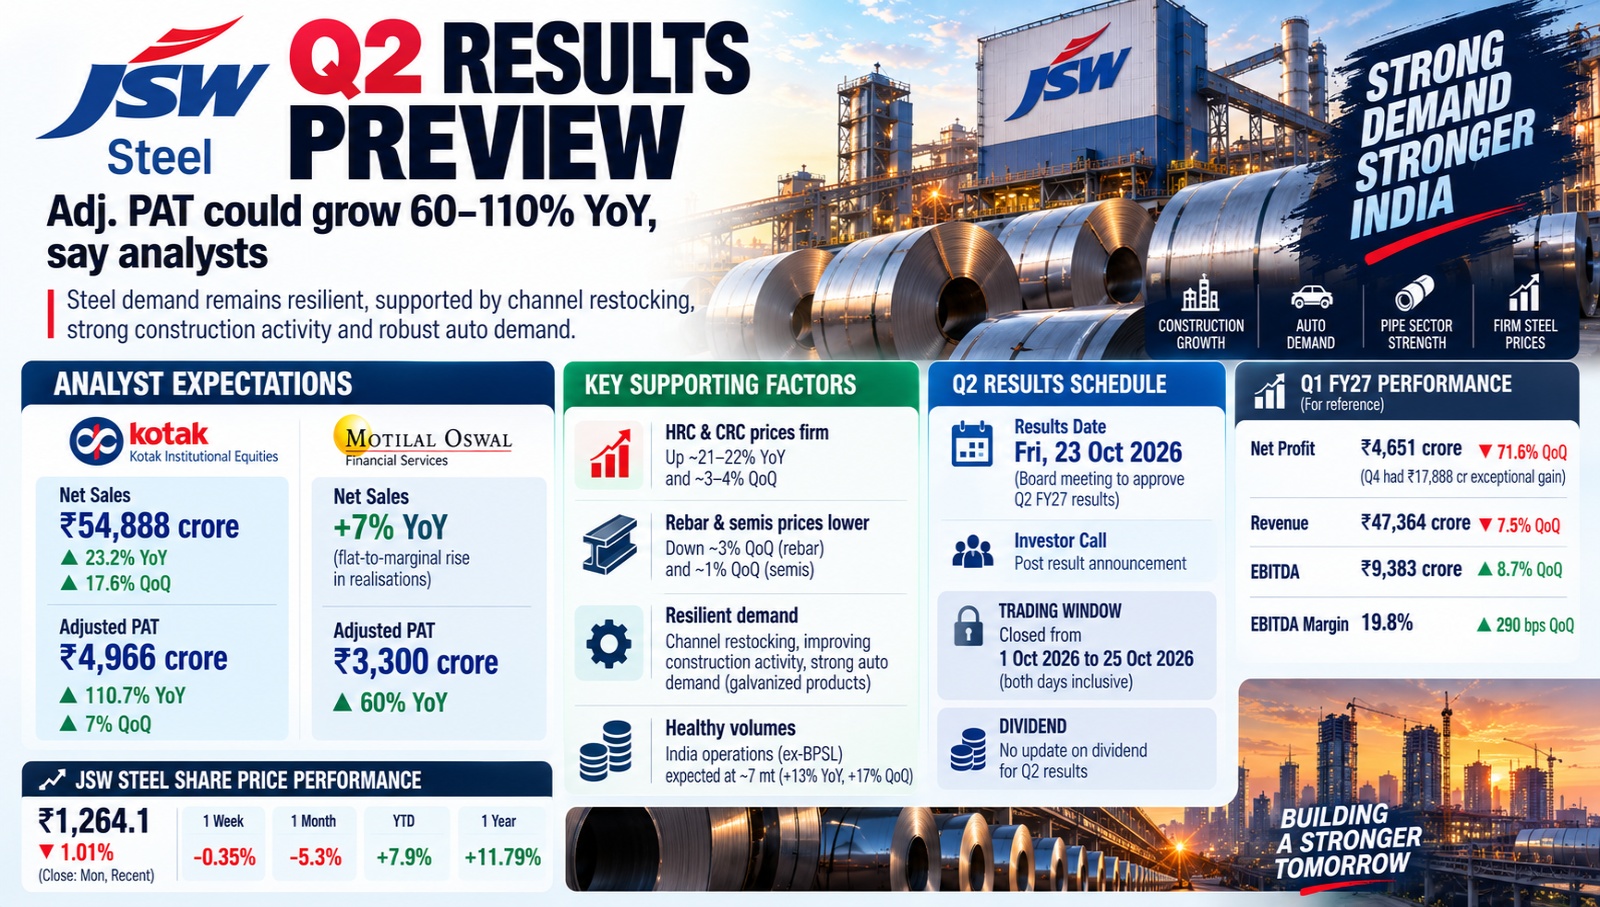
Kotak Institutional Equities expects JSW Steel’s net sales to increase 23.2% year-on-year and 17.6% quarter-on-quarter to ₹54,888.4 crore.
The brokerage projects adjusted profit of ₹4,965.5 crore, representing growth of 110.7% year-on-year and 7% sequentially.
Kotak expects India operations, excluding Bhushan Power and Steel (BPSL), to report volumes of approximately 7 million tonnes, up 13.2% year-on-year and 17% quarter-on-quarter. JVML volumes are estimated at around 1.1 million tonnes.
However, the brokerage expects standalone steel realisations to decline 1.1% sequentially, despite rising 27% year-on-year. EBITDA per tonne for India operations is projected at ₹13,744, down 10.1% quarter-on-quarter because of lower realisations and higher coking coal costs.
JSW Steel Q2 Results Preview: Brokerage Estimates
Kotak Institutional Equities (KIE)
Kotak Institutional Equities expects JSW Steel’s net sales to increase 23.2% year-on-year and 17.6% quarter-on-quarter to ₹54,888.4 crore in Q2 FY27. Adjusted profit after tax (PAT) is projected to rise 110.7% year-on-year and 7% sequentially to ₹4,965.5 crore.
|
Financial Metric |
Q2 FY27 Estimate |
YoY Change |
QoQ Change |
|---|---|---|---|
| Net sales | ₹54,888.4 crore | +23.2% | +17.6% |
| Adjusted PAT | ₹4,965.5 crore | +110.7% | +7.0% |
| India volumes, excluding BPSL | Around 7 million tonnes | +13.2% | +17.0% |
| JVML volumes | Around 1.1 million tonnes | — | — |
| India EBITDA per tonne | ₹13,744 | +26.0% | −10.1% |
Kotak expects standalone steel realisations to decline 1.1% sequentially because of seasonal price weakness, although they could remain 27% higher year-on-year. Higher coking coal costs and lower sequential realisations are expected to weigh on EBITDA per tonne.
Motilal Oswal Sees Adjusted Profit Reaching ₹3,300 Crore
Motilal Oswal Financial Services expects JSW Steel’s adjusted profit after tax (PAT) to rise 60% year-on-year to ₹3,300 crore, supported by 7% sales growth.
The brokerage expects flat-to-marginally higher net sales realisation (NSR) and healthy sales volumes as capacity ramps up.
Investors will also watch management’s comments on capital expenditure, demand, steel pricing and cost inflation. These factors could influence expectations for earnings in the coming quarters.
Motilal Oswal Financial Services (MOFSL)
Motilal Oswal expects JSW Steel’s adjusted PAT to rise 60% year-on-year to ₹3,300 crore, supported by estimated sales growth of 7% in Q2 FY27. The brokerage expects a flat-to-marginal increase in net sales realisation (NSR) and healthy sales volumes as capacity ramps up.
| Financial Metric | MOFSL Estimate |
|---|---|
| Adjusted PAT | ₹3,300 crore |
| Adjusted PAT growth (YoY) | +60% |
| Sales growth (YoY) | +7% |
| Net sales realisation | Flat to marginally higher |
| Sales volumes | Expected to remain healthy |
MOFSL has also identified capital expenditure progress, the outlook for steel demand and prices, and cost inflation as key factors to monitor when the company releases its results.
Track Live : Nifty Levels Today | Sensex Levels Today
JSW Steel Q2 Results Date and Trading Window
JSW Steel will announce its Q2 FY27 results on Friday, October 23, 2026, according to its exchange filing. The board will consider the unaudited standalone and consolidated financial results for the quarter and half-year ended September 30, 2026.
Following the announcement, the company will hold investor and analyst calls to discuss its financial performance and business outlook.
The trading window for designated persons and their immediate relatives remains closed from October 1 to October 25, 2026, inclusive. The company has not provided an update on a dividend announcement alongside the results schedule.
Read More : Oil Hits $112 Again After Saudi Attacks. Will Petrol and Diesel Get Costlier?
Why Could JSW Steel’s Profit Increase?
Domestic steel prices remain firm
Domestic hot-rolled coil (HRC) and cold-rolled coil (CRC) prices were approximately 21–22% higher year-on-year and 3–4% higher quarter-on-quarter in Q2 FY27, according to the report. Firm prices could support revenue and profitability despite seasonal weakness in some steel products.
| Steel Product | Year-on-Year Price Change | Quarter-on-Quarter Price Change |
|---|---|---|
| Hot-rolled coil (HRC) | +21–22% | +3–4% |
| Cold-rolled coil (CRC) | +21–22% | +3–4% |
| Primary rebar | Not specified | −3% |
| Semi-finished steel (semis) | Not specified | −1% |
Demand from construction, pipes and automobiles
Elara Capital said demand remained resilient, supported by several factors:
-
Channel restocking: Distributors replenished inventories ahead of expected steel price increases.
-
Pipe sector demand: Healthy demand from pipe manufacturers supported steel consumption.
-
Construction recovery: Construction activity improved after a patchy monsoon.
-
Automobile demand: Strong auto-sector demand, particularly for galvanised steel products, supported consumption.
These factors could help sustain sales volumes and revenue, although individual product prices and raw-material costs will influence margins.
JSW Steel Q2 FY27 Results Date and Schedule
JSW Steel has scheduled its board meeting for Friday, October 23, 2026, to consider the unaudited standalone and consolidated financial results for the quarter and half-year ended September 30, 2026. The company is also scheduled to hold an investor and analyst conference call at 5:30 p.m. IST.
| Event | Date or Details |
|---|---|
| Q2 FY27 results announcement | October 23, 2026 |
| Reporting period | July–September 2026 |
| Analyst conference call | October 23, 2026, at 5:30 p.m. IST |
| Trading window closure | October 1–25, 2026 |
| Dividend update | No new declaration confirmed in the supplied report |
The trading-window restriction applies to designated persons and their immediate relatives under the company’s insider-trading compliance framework.
JSW Steel Q1 FY27 Results: Background
JSW Steel reported net profit of ₹4,651 crore for Q1 FY27, down 71.6% sequentially from ₹16,370 crore in the previous quarter. The comparison was affected by an exceptional gain of ₹17,888 crore in Q4 FY26. Revenue from operations fell 7.5% quarter-on-quarter to ₹47,364 crore, while EBITDA increased 8.7% to ₹9,383 crore and the EBITDA margin expanded to 19.8% from 16.9%.
The Q2 results will help investors assess whether stronger steel prices and sales volumes can offset higher raw-material costs and seasonal pricing pressure.
What JSW Steel Q2 Results Could Mean for Investors
JSW Steel’s first-quarter FY27 net profit fell 71.6% sequentially to ₹4,651 crore from ₹16,370 crore in the previous quarter. The comparison was affected by an exceptional gain of ₹17,888 crore in Q4.
Revenue declined 7.5% sequentially to ₹47,364 crore, exceeding the Bloomberg analyst estimate of ₹45,100 crore. EBITDA rose 8.7% to ₹9,383 crore, while the EBITDA margin expanded to 19.8% from 16.9%.