HDFC Mutual Fund has picked up 13.9 lakh Entero Healthcare Solutions shares at ₹1,695 apiece, while the Prasid Uno Family Trust has now sold 32.18 lakh shares in the September quarter. The bigger market question is whether the institutional buying can absorb a much larger shareholder exit as Entero trades near its recent peak.
A ₹236-crore block deal has put Entero Healthcare Solutions back on the market radar, but the headline transaction is only one part of the story.
HDFC Mutual Fund bought 13.90 lakh shares, equivalent to 3.19% of Entero’s equity, from Prasid Uno Family Trust on September 18 at ₹1,695 per share. The transaction was worth approximately ₹235.6 crore, according to NSE block-deal data reported by ET and Moneycontrol.
Entero shares, meanwhile, closed Friday at ₹1,732.30, rising 3.94% from the previous close of ₹1,666.60. That means the stock ended roughly 2.2% above the block-deal price. The move is notable, but the market cannot attribute the entire price reaction to HDFC MF’s purchase because the trade was a negotiated secondary-market transaction.
The more important detail is what happened on the other side of the trade.
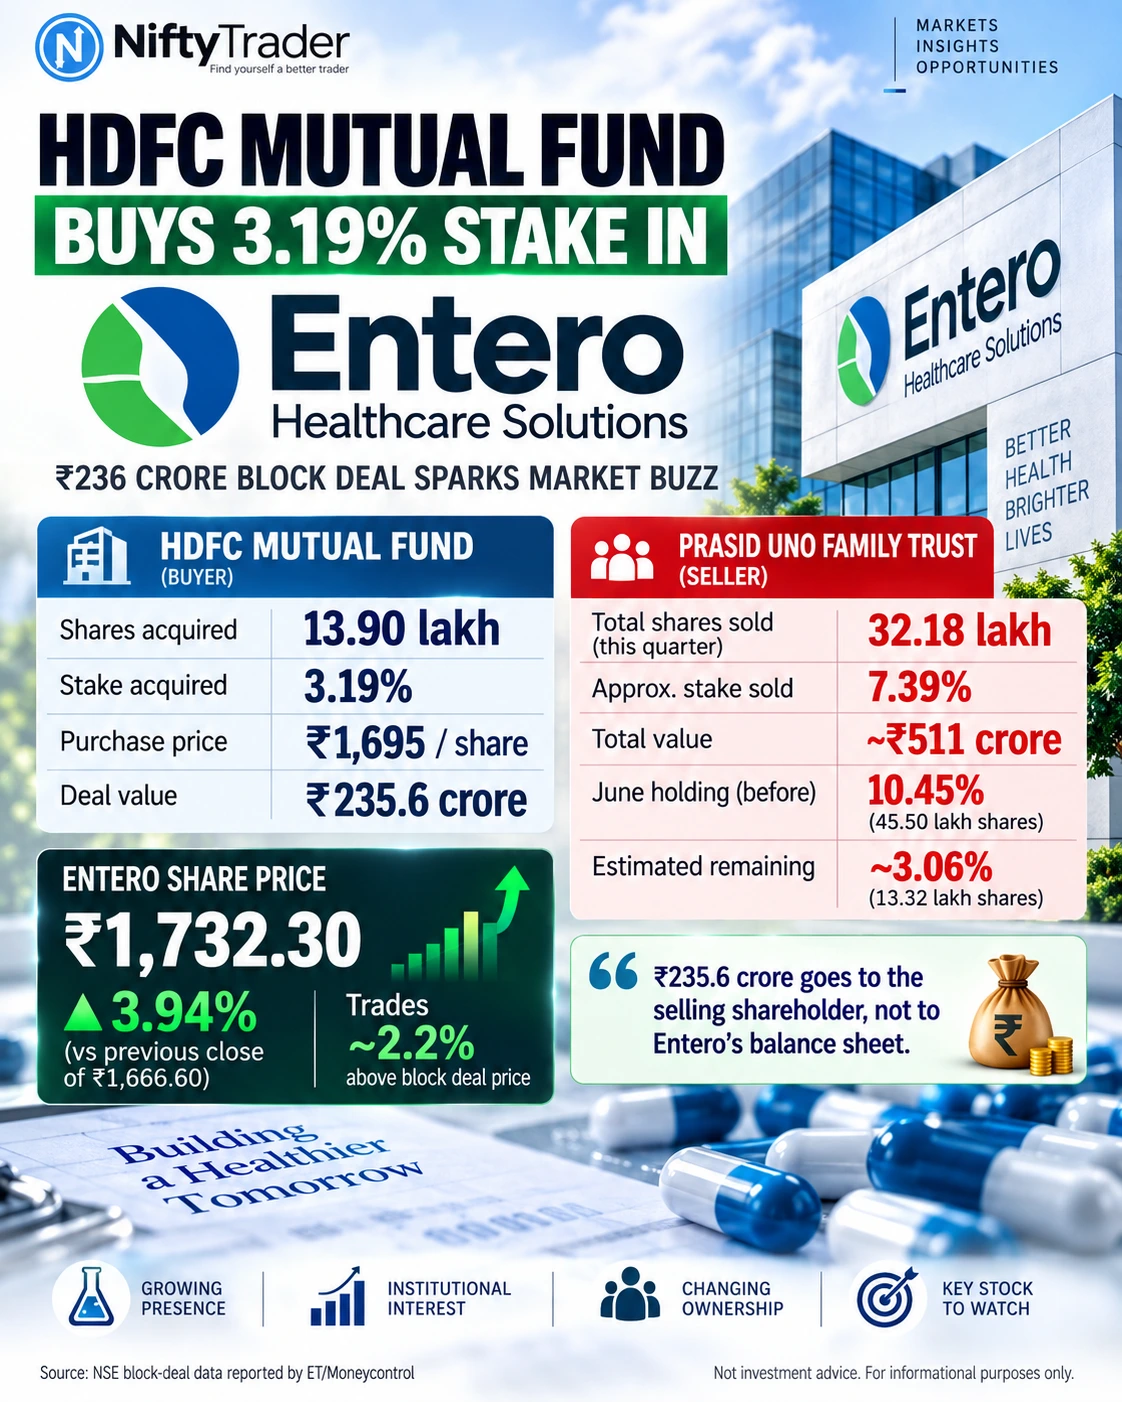
₹236 crore changed hands — but Entero does not get the money
This was a secondary-market transaction between an existing shareholder and an institutional buyer. The ₹235.6 crore therefore goes to the selling shareholder rather than into Entero Healthcare’s balance sheet.
That distinction matters because the deal changes the ownership profile without directly providing the company with fresh capital.
Entero Healthcare block deal: September 18
| Particular | Details |
|---|---|
| Buyer | HDFC Mutual Fund |
| Shares acquired | 13.90 lakh |
| Stake acquired | 3.19% |
| Purchase price | ₹1,695/share |
| Deal value | ₹235.6 crore |
| Seller | Prasid Uno Family Trust |
| Entero NSE close | ₹1,732.30 |
| Day’s gain | 3.94% |
Source: NSE block-deal data reported by ET/Moneycontrol.
One caveat is important: the exchange disclosure identifies HDFC Mutual Fund as the buyer, but it does not establish which individual HDFC MF scheme made the purchase or the investment rationale behind it. The transaction itself is therefore evidence of institutional buying, not evidence of a particular fund manager’s forecast for the stock.
The real story: the family trust has sold 7.39% this quarter
Friday’s deal came after another sizeable round of selling.
Prasid Uno Family Trust had already sold 10.885 lakh shares on August 24 at ₹1,377.80. On September 17, it sold another 7.40 lakh shares through two transactions at around ₹1,693-₹1,695. The September 18 transaction added another 13.90 lakh shares to the disclosed sales.
Together, these disclosed transactions amount to approximately 32.18 lakh shares, or 7.39% of Entero’s equity, during the September quarter.
That is significant against the trust’s 45.50 lakh-share, 10.45% holding as of June 30, 2026. The company’s June shareholding filing records Surbhi Singh as the significant beneficial owner through Prasid Uno Family Trust.
Check Live: Entero Healthcare Solutions Limited IPO
Prasid Uno Family Trust: disclosed selling in the September quarter
| Date | Shares sold | Approx. stake | Price | Approx. value |
|---|---|---|---|---|
| Aug 24 | 10.89 lakh | 2.50% | ₹1,377.80 | ₹150 crore |
| Sep 17 | 7.40 lakh | 1.70% | ~₹1,694 | ₹125.3 crore |
| Sep 18 | 13.90 lakh | 3.19% | ₹1,695 | ₹235.6 crore |
| Total | 32.18 lakh | 7.39% | — | ~₹511 crore |
Sources: reported exchange bulk/block-deal data.
On a simple mathematical basis, if the company’s share capital has remained unchanged, the trust’s June holding of 45.50 lakh shares less the disclosed 32.18 lakh shares would leave roughly 13.32 lakh shares, or about 3.06%.
That should not be treated as a confirmed current holding until the next formal shareholding disclosure is available.
The trust’s association with the Medlife promoter group is also documented in regulatory material. The Competition Commission of India identified Prasid Uno Family Trust alongside Medlife founders Prashant Singh and Tushar Kumar as Medlife promoter shareholders in its 2020 combination review.
Why the timing of the HDFC MF purchase matters
The ownership handover has happened during a period of unusually strong price momentum.
Entero touched ₹1,920 on September 7, its all-time/52-week high on the NSE, before dropping sharply over the following sessions. By September 17, it had closed at ₹1,666.60 after a 3.76% decline, before Friday’s 3.94% rebound to ₹1,732.30. The stock remains about 9.8% below the September peak but roughly 83.5% above its ₹944 52-week low recorded on December 29, 2025.
That creates an unusual market tension:
An existing large shareholder has been steadily reducing exposure at increasingly higher prices, while institutional demand has emerged to absorb part of that supply.
It is not yet clear whether the selling represents portfolio rebalancing, liquidity needs, a planned monetisation, or another shareholder-specific consideration. The disclosure establishes the transaction, but not the reason for it.
The fundamentals give HDFC MF’s purchase a bigger backdrop
The institutional purchase comes when Entero’s operating metrics have been accelerating.
According to the company’s Q1 FY27 investor presentation, consolidated revenue rose 38.2% year on year to ₹1,940.5 crore. Like-for-like growth was 40%, while organic growth was 17.8%. EBITDA increased 94% to ₹97 crore, pushing the EBITDA margin to 5% from 3.6% a year earlier.
The company also reported an improvement in gross margin to 11.4% from 9.9%, while net operating working-capital days improved to 61 from 66. ROCE rose to about 21% from 11.5%, and ROE reached 20.4% versus 9% in Q1 FY26.
Entero Q1 FY27: the numbers behind the stock
| Metric | Q1 FY26 | Q1 FY27 | Change |
|---|---|---|---|
| Revenue | ₹1,403.8 Cr | ₹1,940.5 Cr | +38% |
| Gross Profit | ₹139.6 Cr | ₹221.4 Cr | +59% |
| Gross Margin | 9.9% | 11.4% | +147 bps |
| EBITDA | ₹50.1 Cr | ₹97.0 Cr | +94% |
| EBITDA Margin | 3.6% | 5.0% | +143 bps |
| Consolidated PAT | ₹30.2 Cr | ₹52.1 Cr | +72% |
| PAT attributable to owners | ₹27.8 Cr | ₹38.2 Cr | +37% |
| NWC days | 66 | 61 | Improvement |
Source: Entero Healthcare Q1 FY27 investor presentation.
One number investors should not overlook
The 72% increase in consolidated PAT sounds striking, but the portion attributable to Entero’s equity holders rose 37%, to ₹38.2 crore, because ₹13.9 crore of Q1 profit was attributable to non-controlling interests.
That distinction becomes more relevant as the market values the company on earnings attributable to its own shareholders.
In FY26, Entero reported consolidated revenue of ₹6,591.2 crore, EBITDA of ₹266 crore and profit after tax of ₹145.8 crore. The company had generated ₹96.2 crore of net cash from operating activities during FY26, compared with negative operating cash flow in FY25.
But the growth story comes with a financial pressure point
There is another side to the improving operating picture.
Entero’s consolidated borrowings stood at about ₹566.7 crore at March 2026, compared with ₹298.8 crore a year earlier. In Q1 FY27, finance costs rose to ₹18.1 crore from ₹8.3 crore in Q1 FY26.
The company’s working-capital metrics have improved, which is encouraging, but higher borrowing and financing costs remain a variable to watch as the business expands.
This creates an important expectation gap for the market: the operating business is showing much faster revenue and EBITDA growth, but investors will ultimately need that growth to translate into stronger earnings attributable to shareholders and sustainable cash generation.
Entero is expanding beyond traditional pharma distribution
The company is also building its MedTech business.
Entero says its Q1 FY27 network covered 72,000+ retail customers, 2,300+ hospitals, 475 districts and 138 warehouses, with more than 83,400 SKUs handled.
Management has said its FY27 MedTech revenue is expected to cross ₹1,000 crore, while the presentation highlights in-vitro diagnostics, cardiovascular/orthopaedic devices, imaging and consumables as major areas of focus.
The company also says organic growth is running ahead of the Indian pharmaceutical market: Q1 FY27 organic growth was 17.8%, versus roughly 12% IPM growth in its presentation.
But there is a subtle point here.
Entero’s 20.4% inorganic growth in Q1 FY27 came entirely from calendarisation, according to the company, rather than from new acquisitions during the quarter.
So the headline 38.2%-40% growth rate cannot simply be extrapolated as a recurring acquisition-led growth rate.
The valuation question is getting harder to ignore
At ₹1,732.30, Entero’s market capitalisation was around ₹7,540 crore on September 18.
Using FY26 profit attributable to owners of roughly ₹115 crore and the company’s June share base, the stock was trading at approximately 65.5 times FY26 earnings by a simple calculation.
That does not tell investors whether the valuation is justified or excessive. It does show what the market is already pricing in: continued earnings growth, improving margins and successful execution of the company’s expansion strategy.
The forward-looking risk is therefore straightforward. If revenue momentum slows, margins stop improving, working-capital efficiency weakens or financing costs remain elevated, the distance between expectations and delivered earnings could become more important for the stock.
What the market will watch next
The September 18 transaction leaves investors with several concrete monitorables rather than a simple “HDFC MF bought, therefore bullish” conclusion.
First: whether HDFC MF’s purchase is followed by additional institutional accumulation or was a one-off portfolio transaction.
Second: whether Prasid Uno Family Trust continues to reduce its residual stake.
Third: whether Entero can maintain organic growth near its recent levels while improving EBITDA margins.
Fourth: whether the company’s projected MedTech expansion, including the stated FY27 ₹1,000-crore revenue milestone, translates into sustainable profitability.
Fifth: whether higher borrowings and finance costs remain manageable as the company scales.
Track FII-DII flows and see whether institutional buying is broadening across healthcare stocks
Why this Entero deal is different from a simple block-deal headline
The ₹235.6-crore HDFC MF purchase is certainly large enough to draw attention, but the more informative reading comes from combining three pieces of evidence:
Institutional absorption: HDFC MF bought 3.19% in a single transaction.
Shareholder supply: Prasid Uno Family Trust has disclosed sales equivalent to 7.39% of Entero during the September quarter.
Fundamental momentum: Q1 FY27 revenue grew 38.2%, EBITDA jumped 94%, and operating metrics improved, while financing costs and valuation remain key variables.
That makes the transaction less about one buyer and one seller and more about how Entero’s ownership is changing while the market reassesses the company’s growth trajectory.
The uncertainty is whether the present combination of institutional demand, strong operating growth and elevated valuation can persist at the same time. The next shareholding filing and upcoming quarterly results should provide a clearer read.
Need to Know
| Question | Answer |
|---|---|
| Who bought Entero shares? | HDFC Mutual Fund |
| How much did it buy? | 13.90 lakh shares |
| What stake does that represent? | 3.19% |
| At what price? | ₹1,695 per share |
| Deal value? | About ₹235.6 crore |
| Who sold? | Prasid Uno Family Trust |
| How much has the trust sold this quarter? | About 32.18 lakh shares, or 7.39% |
| Entero Friday close? | ₹1,732.30 |
| Recent record high? | ₹1,920 on September 7, 2026 |
| Q1 FY27 revenue growth? | 38.2% reported; 40% LFL |
| Q1 FY27 EBITDA growth? | 94% |
Sources: Entero Healthcare investor disclosures and exchange-deal data reported by ET/Moneycontrol.
Read Next: US Equity Funds Draw $64B as India Funds Hit 7-Week Outflow High
FAQ
Why did Entero Healthcare shares rise after the HDFC MF deal?
Entero shares rose 3.94% to ₹1,732.30 on September 18 after closing at ₹1,666.60 the previous day. The rise coincided with the disclosed HDFC MF purchase, but the transaction alone does not establish that it caused the entire price move.
Is the HDFC MF transaction fresh investment into Entero Healthcare?
No. It was a secondary-market block transaction between HDFC Mutual Fund and Prasid Uno Family Trust. The cash consideration therefore went to the selling shareholder rather than directly to Entero Healthcare.
How much Entero stake has Prasid Uno Family Trust sold?
Based on disclosed bulk/block transactions, the trust has sold about 32.18 lakh shares, equivalent to 7.39%, during the September quarter.
Does HDFC MF’s purchase mean the stock will rise?
The transaction confirms a large institutional purchase, but it does not establish HDFC MF’s future return expectation or guarantee a particular stock price outcome. The stock’s future performance will depend on earnings, valuation, liquidity, institutional flows and broader market conditions.
What is the key risk after the deal?
The central risk is an expectation gap. Entero is reporting rapid revenue and EBITDA growth, but the stock is trading at a high earnings multiple while finance costs have increased materially. Sustaining growth and converting it into shareholder earnings will be important.
Disclaimer: This article is for informational and educational purposes only. The transaction details and company disclosures are based on exchange/company filings and publicly available reports. Nothing here should be construed as investment advice or a recommendation to buy or sell any security.