RBL Bank Q2 Update: RBL Bank posted 40% year-on-year growth in gross advances in Q2 FY27, while advance growth was 30% after excluding loans extended by its International Banking Unit against FCNR(B) deposits. PNB, Bank of Baroda and AU Small Finance Bank also reported strong operating growth, making deposit mobilisation and funding quality the next key variables for investors.
Bank stocks strengthened on Monday after lenders released provisional Q2 FY27 business updates, but the more important takeaway lies beyond the share-price reaction.
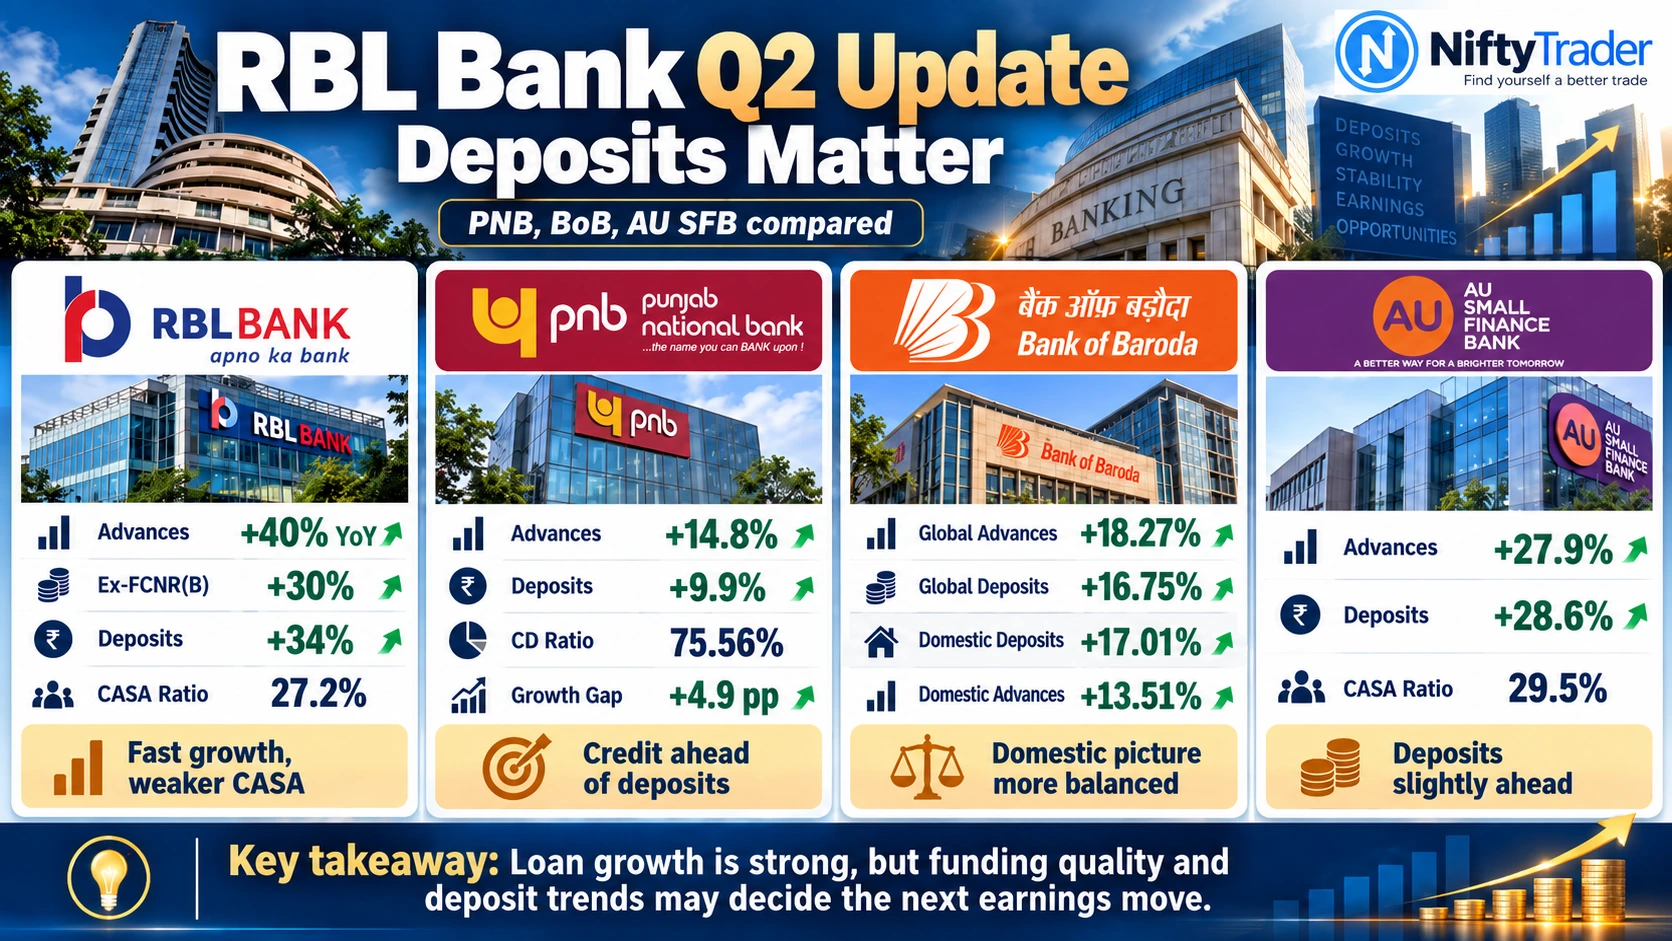
RBL Bank reported the strongest headline advance growth among the four names at 40% year-on-year, while AU Small Finance Bank grew gross advances 27.9%, Bank of Baroda 18.27% and Punjab National Bank 14.8%. The catch is that the quality and composition of the funding behind that growth differ across the banks.
That creates an important expectation gap for the next phase of the banking trade: fast loan growth may support future earnings, but it does not automatically guarantee stronger margins or profits.
Need to Know
- RBL Bank: Gross advances rose 40% YoY to ₹1.43 lakh crore, while advance growth was 30% after excluding loans extended by its International Banking Unit against FCNR(B) deposits.
- PNB: Global advances rose 14.8% YoY to ₹13.43 lakh crore, while total deposits increased 9.9% to ₹17.77 lakh crore.
- Bank of Baroda: Global advances increased 18.27% and global deposits 16.75%; domestic deposits rose 17.01%, while domestic advances grew 13.51%.
- AU Small Finance Bank: Deposits grew 28.6% YoY, gross advances 27.9%, and CASA deposits 29.1%; the CASA ratio stood at 29.5%.
- Sector trend: RBI data showed banking-system credit growing 18.1% YoY against 17.3% deposit growth as of September 15, keeping the funding question relevant.
RBL Bank: The 40% Loan-Growth Number Comes With a Footnote
RBL Bank stands out immediately on the Q2 scorecard.
Gross advances rose 40% YoY to ₹1.43 lakh crore, while deposits increased 34% to ₹1.56 lakh crore. Sequentially, deposits rose 25% and gross advances increased 22%. Wholesale advances jumped 55% YoY.
But investors should not read the 40% figure in isolation.
RBL Bank said advance growth was 30% after excluding loans extended by its International Banking Unit against FCNR(B) deposits. That provides a more comparable reference point for assessing the underlying lending trajectory.
There is another important signal in the funding mix.
CASA deposits rose 14% YoY to ₹42,530 crore, but the CASA ratio declined to 27.2% from 31.9% a year earlier and 29.2% in June 2026. At the same time, RBL’s average liquidity coverage ratio improved to 148% from 127% a year earlier.
So the RBL story has two sides: exceptionally strong credit expansion on one hand, and a lower CASA mix on the other.
The next question is therefore not simply whether RBL can grow loans. It is whether that growth can be sustained while protecting funding costs and margins.
PNB: Credit Growth Is Clearly Ahead of Deposits
PNB’s global business increased about 12% YoY to ₹31.2 lakh crore as of September 30, 2026.
Global advances rose 14.8% to ₹13.43 lakh crore, while total deposits increased 9.9% to ₹17.77 lakh crore.
This produces a 4.9-percentage-point gap between advance growth and deposit growth.
PNB’s global credit-deposit ratio rose to 75.56%, compared with 72.33% a year earlier.
The numbers point to healthy credit demand, but a sustained loan cycle eventually requires a sufficiently strong deposit franchise.
For PNB, investors will therefore be watching whether deposit mobilisation accelerates enough to support the current credit trajectory without materially increasing the cost of funds.
Bank of Baroda: Domestic Numbers Tell a More Balanced Story
Bank of Baroda reported global business of ₹32.64 lakh crore, up 17.45% YoY.
Global advances rose 18.27% to ₹15.12 lakh crore, while global deposits grew 16.75% to ₹17.51 lakh crore.
The domestic picture is particularly useful.
Domestic deposits stood at about ₹14.88 lakh crore, up 17.01% YoY, while domestic advances rose 13.51%. Domestic retail advances, excluding pool purchase, increased 18.67%.
Bank of Baroda also mobilised around $8 billion through the RBI’s concessional FCNR(B) swap window.
For BoB, the appropriate read-through is therefore not to mechanically “normalise” its advance growth in the same way as RBL Bank. Instead, investors should compare global and domestic growth and the contribution of FCNR(B) mobilisation to overall deposit growth.
The domestic figures show a relatively balanced funding picture, with domestic deposit growth running ahead of domestic advances.
AU Small Finance Bank: Deposit Growth Edges Ahead of Loans
AU Small Finance Bank provides the most balanced loan-deposit comparison among the four lenders.
Deposits increased 28.6% YoY to ₹1.70 lakh crore, while gross advances rose 27.9% to ₹1.50 lakh crore. Sequentially, deposits increased 8.1% and advances rose 7%.
The funding mix also improved.
CASA deposits increased 29.1% YoY to ₹50,290 crore, lifting the CASA ratio to 29.5%, compared with 29.4% a year earlier and about 28.8% at the end of June.
This is significant because the bank is not merely growing its loan book. It is simultaneously showing strong deposit mobilisation and broadly stable low-cost deposits.
AU SFB is also transitioning towards a universal-bank model, making the mix and quality of future growth particularly important to investors.
Four Banks, Four Different Q2 Signals
| Bank | Advances Growth | Deposit Growth | Growth Gap | Main Q2 Signal |
|---|---|---|---|---|
| RBL Bank | 40% reported | 34% | +6.0 pp | 30% advances growth ex-FCNR(B); CASA ratio declined |
| AU SFB | 27.9% | 28.6% | -0.7 pp | Deposits slightly ahead; CASA ratio improved |
| Bank of Baroda | 18.27% | 16.75% | +1.52 pp | Strong retail growth; FCNR(B) boosted deposit mobilisation |
| PNB | 14.8% | 9.9% | +4.9 pp | Credit growth well ahead of deposits; CD ratio increased |
Growth-gap figures are simple differences between reported YoY advance and deposit growth and are used only for comparison.
The ranking changes depending on what an investor values.
RBL Bank leads on headline credit growth, but its normalised growth is lower and CASA has weakened.
AU SFB has slightly lower loan growth, yet deposits are keeping pace and CASA is improving.
PNB has one of the widest credit-deposit growth gaps among the four, while Bank of Baroda combines strong global credit growth with relatively strong domestic deposit growth.
Banking Sector Has the Same Tension
The four-bank comparison is part of a larger banking-sector pattern.
RBI data showed banking-system credit growth at 18.1% YoY, against 17.3% deposit growth as of September 15.
Business Standard also reported that FCNR(B) mobilisation provided a significant funding boost to banks during Q2, with nearly $133 billion of deposits mobilised under the special swap window.
This creates a forward-looking risk: the Q2 funding picture may look stronger than the recurring domestic deposit trend once the exceptional FCNR(B) contribution fades from comparisons.
Banks are therefore facing a two-sided equation: credit demand remains firm, but maintaining adequate deposits at competitive funding costs could determine the sustainability of margins.
What Investors Should Watch Before Q2 Results
The business updates are provisional. They do not provide the full earnings picture, which means the next catalyst is the actual quarterly result and management commentary.
NIM and Cost of Funds
Rapid loan growth is helpful only when incremental loans generate sufficient spread. Deposit competition and funding costs can determine how much of that growth reaches the bottom line.
CASA Trajectory
RBL Bank’s CASA-ratio decline and AU SFB’s improvement show why total deposit growth alone is not enough.
Normalised Growth
For RBL Bank, investors should watch advance growth after excluding loans extended by its International Banking Unit against FCNR(B) deposits.
For Bank of Baroda, the more useful comparison is global versus domestic growth, while recognising that FCNR(B) mobilisation supported overall deposit growth.
Asset Quality
Business updates do not provide the complete picture on GNPA, NNPA, slippages, provisions or credit costs. Those figures could materially change the market’s reading of the operating data.
Post-FCNR(B) Deposit Momentum
This could be one of the most important tests for the sector. The key uncertainty is whether deposit mobilisation remains strong enough to support credit growth after the special FCNR(B) funding window is no longer adding to the base.
Monday’s Stock Reaction
The positive market reaction confirms that investors initially welcomed the Q2 operating updates. However, the magnitude of gains varied significantly across the four names.
The stock reaction should be viewed as a market response to provisional operating numbers, rather than as evidence that one bank now has a definitively superior earnings outlook.
The next decisive signals will come from Q2 NIM, profitability, asset quality and management commentary.
What This Means for Investors
The four Q2 updates tell a more interesting story than a simple banking-stock rally.
RBL Bank has the fastest reported advance growth, but its normalised growth is lower and CASA has weakened.
AU SFB shows a more balanced expansion, with deposit growth slightly ahead of advances and CASA improving.
Bank of Baroda reported robust global growth while its domestic deposit growth was stronger than domestic advance growth.
PNB has seen credit growth significantly outpace deposits, even though its global CD ratio remains at a relatively moderate 75.56%.
The bigger opportunity for investors may therefore lie not in identifying which bank grew loans fastest, but in finding which lender can sustain that growth with the strongest funding mix and least margin pressure.
That distinction should become clearer when the banks release their full Q2 financial results.
Read More: HDFC Bank Q2 FY27 Update: Deposits Rise 18.8%, But CASA Trails Time Deposits
FAQ
Which bank reported the highest Q2 FY27 loan growth among these four?
RBL Bank reported the highest headline gross-advance growth at 40% YoY. However, the bank said advance growth was 30% after excluding loans extended by its International Banking Unit against FCNR(B) deposits.
What was RBL Bank’s Q2 FY27 deposit growth?
RBL Bank’s deposits increased 34% YoY to about ₹1.56 lakh crore in Q2 FY27.
What happened to RBL Bank’s CASA ratio?
RBL Bank’s CASA ratio declined to 27.2% from 31.9% a year earlier and 29.2% in June 2026.
What was PNB’s Q2 FY27 credit-deposit ratio?
PNB’s global credit-deposit ratio stood at 75.56% at September-end 2026, compared with 72.33% a year earlier.
Did Bank of Baroda’s domestic deposits grow faster than domestic advances?
Yes. Domestic deposits grew 17.01% YoY, while domestic advances increased 13.51%.
Did AU Small Finance Bank deposits grow faster than advances?
Yes. AU SFB’s deposits increased 28.6% YoY, marginally ahead of its 27.9% gross-advance growth.
Are these final Q2 results?
No. These are provisional business-update figures. Final Q2 results will provide additional information on NIM, net profit, provisions, slippages and asset quality.
Disclaimer
The business figures discussed are provisional and may be subject to review or changes in the final quarterly results. This article is for informational purposes only and does not constitute investment advice.