Poonawalla Fincorp‘s Q2 FY27 profit rose 405% to ₹374.85 crore and shares surged as much as 8% on Monday. Improving asset quality supports the recovery, but portfolio seasoning, funding costs and proposed insurance commission caps will test its durability.
Poonawalla Fincorp shares surged as much as 8% to an intraday high of about ₹484 on Monday, adding an estimated ₹3,200 crore to the company’s market value, after the NBFC reported Q2 FY27 profit of ₹374.85 crore, up 405.2% year-on-year from ₹74.20 crore. But the growth rate flatters a low base.
The sharper signal in the Poonawalla Fincorp Q2 results is return on assets, which climbed to 2.18% from 0.69% a year earlier as assets under management (AUM) grew 55.1% to ₹74,008 crore.
The results landed two days after the RBI’s October 7 rate hike, its first since February 2023, setting up the first real test of whether margin expansion can survive higher funding costs.
Need to Know
- Profit: PAT of ₹374.85 crore, up 405% YoY and 21.8% over Q1 FY27’s ₹308 crore. H1 FY27 PAT is ₹682.56 crore.
- Growth: AUM of ₹74,008 crore, up 55.1% YoY and 10.4% QoQ. New products drove 28% of disbursements.
- Profitability: ROA of 2.18%, up 149 bps YoY. NIM including fees at 9.26%.
- Asset quality: Gross NPA 1.20%, net NPA 0.61%, credit cost 2.19% versus 2.40% in Q1.
- Stock: ₹447.30 at Friday’s close, an intraday high of about ₹484 on Monday. Brokerage targets are split: Motilal Oswal ₹570, Emkay Global ₹410.
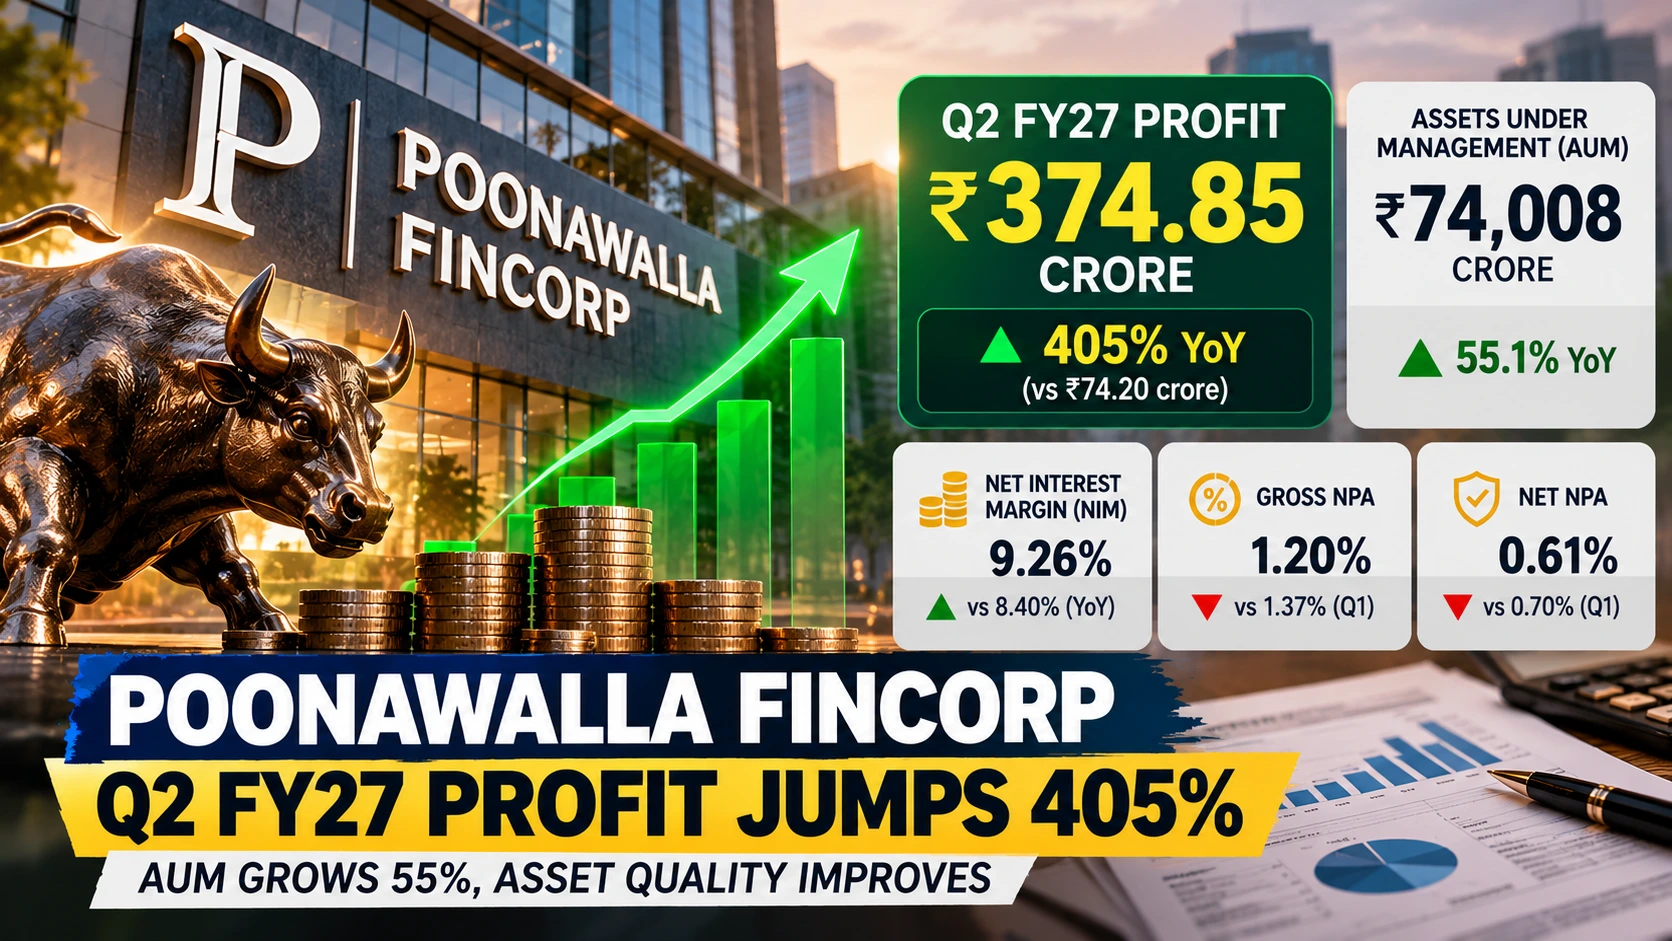
Poonawalla Fincorp Q2 Results at a Glance
| Metric | Q2 FY27 | QoQ | YoY |
|---|---|---|---|
| Profit after tax | ₹374.85 crore | +21.8% | +405.2% |
| Net interest income incl. fees and other income | ₹1,589 crore | +12.3% | +75.6% |
| Pre-provision operating profit | ₹877 crore | +11.8% | about 2.3x |
| Assets under management | ₹74,008 crore | +10.4% | +55.1% |
| NIM incl. fees | 9.26% | +16 bps | +86 bps |
| Return on assets | 2.18% | +20 bps | +149 bps |
| Credit cost | 2.19% | -21 bps | -48 bps |
| Gross NPA | 1.20% | -17 bps | -39 bps |
| Net NPA | 0.61% | -9 bps | -20 bps |
Source: company filing, investor presentation and earnings call. Year-ago operating profit per Anand Rathi Research.
Why the 405% Profit Jump Needs Context
Last year’s base was thin. Poonawalla Fincorp earned just ₹74.2 crore in Q2 FY26, and a year before that it posted a ₹471 crore loss after a one-time provisioning hit on its short-term personal loan book. Rounded figures put the growth at 407%, the number some reports use; exact filing numbers give 405%.
Cleaner yardsticks: profit rose 21.8% from Q1, and pre-provision operating profit of ₹877 crore is about 2.3 times the roughly ₹387 crore reported a year ago.
The company’s filing adds two more checks. Pre-tax profit was ₹501.30 crore against ₹98.89 crore a year ago, about 5.1 times, and total income from operations rose 70.1% to ₹2,624.84 crore. Basic earnings per share climbed to ₹4.27 from ₹0.95, about 349%, which is less than the profit jump because the share count is higher: paid-up equity capital rose about 9%, from ₹161.49 crore to ₹176.12 crore.
The arithmetic behind the leap is revealing. Interest income grew 72.3% to ₹2,415.54 crore, while finance costs rose a slower 62.3% to ₹1,035.45 crore, lifting net interest income about 80% to ₹1,380 crore (a narrower measure than the ₹1,589 crore that includes fees and other income).
Impairment charges rose 34% to ₹346.37 crore, and the credit-cost ratio fell to 2.19%. Because impairment is a quarterly flow and AUM is a period-end balance, their growth rates are not directly comparable; the credit-cost ratio is the cleaner gauge.
Margins Up, Credit Costs Down: The ROA Engine
CEO Arvind Kapil called the quarter “an inflection point in establishing a self-sustaining earnings engine.” Poonawalla Fincorp’s portfolio yield rose about 45 bps QoQ to 14.08% and disbursement yields added roughly 20 bps, keeping NIM above 9% for a third straight quarter. Credit cost fell to 2.19% of average AUM from 2.40% in Q1, 2.51% in Q4 FY26 and 2.67% a year ago. Operating expenses stood at 4.15% of average AUM, reflecting front-loaded spending on collections, AI and gold-loan branches.
Asset Quality Improves, but Analysts Pushed on Seasoning
Gross NPA fell to 1.20% from 1.37% in Q1 and net NPA to 0.61% from 0.70%. Stage 2 assets shrank to 0.94% from 1.03%, notable for a lender whose book grew 10% in one quarter. The share of the latest loan cohort 30 or more days past due after six months, excluding gold loans, improved to 0.35% from 0.67%.
The sharpest question on the call came from an Emkay Global analyst, who noted that 60-65% of the book is under 12 months old and suggested much of the credit cost may be going to write-offs in a benign credit cycle.
Poonawalla Fincorp’s management said newer vintages are performing better, citing a 53% improvement in 12-month 90+ delinquencies on a recent cohort. It argued that Stage 2 can only shrink during rapid growth if underwriting is genuinely tighter.
The New-Product Engine: Gold, Consumer Durables, Digital Loans
New products delivered 28% of disbursements (26% in Q1, 24% in Q4 FY26), more than ₹4,400 crore in all, and now make up 18% of AUM.
| Product | AUM (₹ crore) | Share of AUM |
|---|---|---|
| Prime Personal Loan | 6,662 | 9% |
| Gold Loan | 2,355 | 3% |
| Education Loan | 1,915 | 3% |
| Commercial Vehicle Loan | 1,459 | 2% |
| Consumer Durable Loan | 859 | 1% |
- Gold loans: 550 branches, up from 460 at the end of Q1. Quarterly disbursements rose to ₹1,066 crore from ₹875 crore. Management remains on track to add approximately 400 gold-loan branches during FY27, and new branches typically break even in about 13 months.
- Consumer durables and digital: A network of 20,000+ dealers across 360 locations delivered quarterly disbursements of ₹606 crore, up 40%. The 24×7 digital Prime PL now makes up 42% of personal loan disbursements, up from 38%.
Two Policy Tests: A Rate Hike and Insurance Commission Caps
The RBI raised the repo rate by 25 bps to 5.50% on October 7, its first hike since February 2023, and moved to a stance of calibrated tightening. For a market-funded lender, that is the first real test of margin expansion.
Poonawalla Fincorp’s management pointed to its diversified funding mix: the cost of borrowing was 7.76% in Q2 FY27, up four basis points from the June quarter, while 88.9% of borrowings came from long-term sources, and roughly one-third of borrowings are fixed-rate NCDs. Management also said it had already passed on a 25-basis-point increase in lending rates.
There is a timing catch, however. The reported 7.76% covers the quarter ended September 30, before the RBI raised the repo rate on October 7, so the figures do not yet show the full effect of the hike on funding costs. The next results will offer a clearer test of whether lending yields can keep pace with any rise in funding expenses.
The second policy risk is IRDAI’s September 23 consultation paper on insurance distribution. For insurance sold by lenders alongside loans, it proposes a 2% commission cap on single-premium pure-term policies and 2.5% in the first year and 1% on renewal for multi-year-premium policies.
Other insurance categories carry different proposed limits. It also proposes banning compulsory bundling of insurance with loans. The proposals are not final, and stakeholder comments are due by October 25.
Management told analysts it had anticipated possible fee compression and that core lending spreads and operating leverage should help absorb it. Other income was about ₹209 crore in Q2, roughly 8% of revenue from operations, but the company’s insurance-distribution income is not separately quantified in the headline figures, so its direct exposure cannot be calculated. The earnings effect remains uncertain until the rules are finalised and the company discloses more detail.
Poonawalla Fincorp Share Price: Up 8%, but Still Below Last Year’s Results Day
Friday’s close of ₹447.30 came before the post-market earnings call, so Monday was the first full session to price in the numbers. The intraday surge of as much as 8% to about ₹484 adds an estimated ₹3,200 crore to a market value near ₹39,400 crore at Friday’s close.
The context cuts both ways. The stock closed at ₹526.40 on October 17, 2025, when the Q2 FY26 results were announced. Even at Monday’s intraday high of ₹484, shares remained about 8% below that level despite five times the profit; compared with Friday’s ₹447.30 close, they were roughly 15% lower. The intraday high also sits about 11% below the 52-week high of roughly ₹545.
On the Poonawalla Fincorp share price outlook, brokerages are split. Motilal Oswal retains a ₹570 price target (2.7x September 2028E book value), called Q2 profit in line, and models roughly 44% AUM CAGR and 120% PAT CAGR over FY26-28, reaching RoA of 2.4% and RoE of about 17% by FY28. From ₹484, that target implies about 18% upside. Emkay Global’s target is ₹410, about 15% below ₹484. These are brokerage estimates, not guaranteed outcomes.
What to Watch Next
Key dates: October 14-15, Poonawalla Fincorp meets institutional investors in Singapore. October 21, RBI publishes MPC minutes. October 25, IRDAI comment deadline. December 2-4, next RBI policy meeting.
Three tests will decide whether Monday’s rally holds:
- Credit cost durability. It fell 21 bps in the same quarter that ROA rose 20 bps. Unsecured loans are still 48% of the on-book mix and an analyst on the call put 60-65% of the book at under 12 months old, so a slide back toward Q1’s 2.40% would test the thesis.
- Operating leverage versus expansion. Opex to AUM sits at 4.15%, and about 400 new gold branches bring costs before the 13-month breakeven. Poonawalla Fincorp says cross-selling has only just begun.
- Funding and capital. Poonawalla Fincorp’s capital adequacy is 18.68% (Tier 1 at 17.15%) against a 15% regulatory minimum, while on-book loans grew 24% in six months, from ₹55,951 crore to ₹69,563 crore, after a ₹2,500 crore QIP in April.
The bull case needs credit cost near 2.2%, opex near 4.15% and AUM compounding at the 35-40% management has indicated, all at once. A slip in any one would put the 2.18% ROA under pressure.
Read Next: Stocks to Watch Today Oct 12: HCLTech Q2, DMart Margin Miss, RBI Forex Curbs
FAQ
What were Poonawalla Fincorp’s Q2 FY27 results?
Poonawalla Fincorp’s profit after tax rose to ₹374.85 crore from ₹74.20 crore a year ago and ₹308 crore in Q1. AUM reached ₹74,008 crore, NIM including fees was 9.26% and ROA was 2.18%.
Why did Poonawalla Fincorp shares jump after Q2 results?
Results came after Friday’s close. On Monday investors priced in 55% AUM growth, lower credit cost, falling NPAs and a higher ROA in the same quarter.
Is 405% the right growth figure to focus on?
It reflects a low base, since Q2 FY26 profit was just ₹74.2 crore. Quarter-on-quarter profit growth of 21.8% and operating profit of about 2.3x the year-ago level are cleaner measures. Earnings per share rose about 349%, to ₹4.27 from ₹0.95.
What is Poonawalla Fincorp’s gross NPA?
Gross NPA was 1.20% at September 30, 2026, versus 1.37% in June. Net NPA was 0.61%.
What is the Poonawalla Fincorp share price target after Q2?
Motilal Oswal’s target price is ₹570, while Emkay Global’s is ₹410. Targets are analyst estimates and can change.
This article is for information only and is not investment advice. Please consult a SEBI-registered adviser before investing.