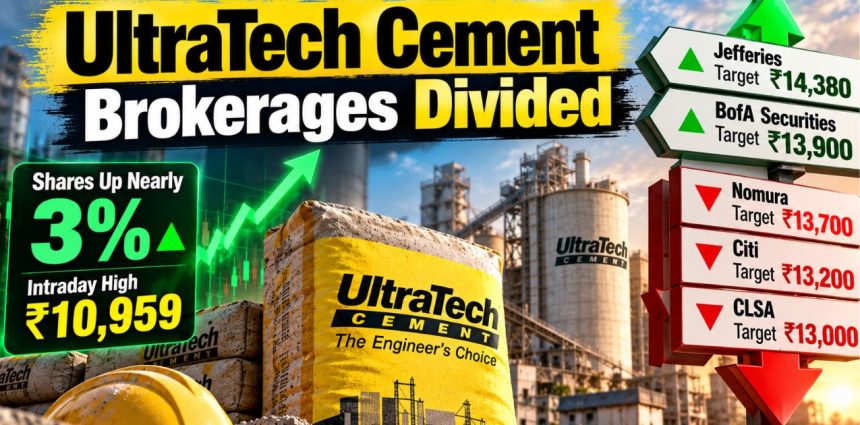
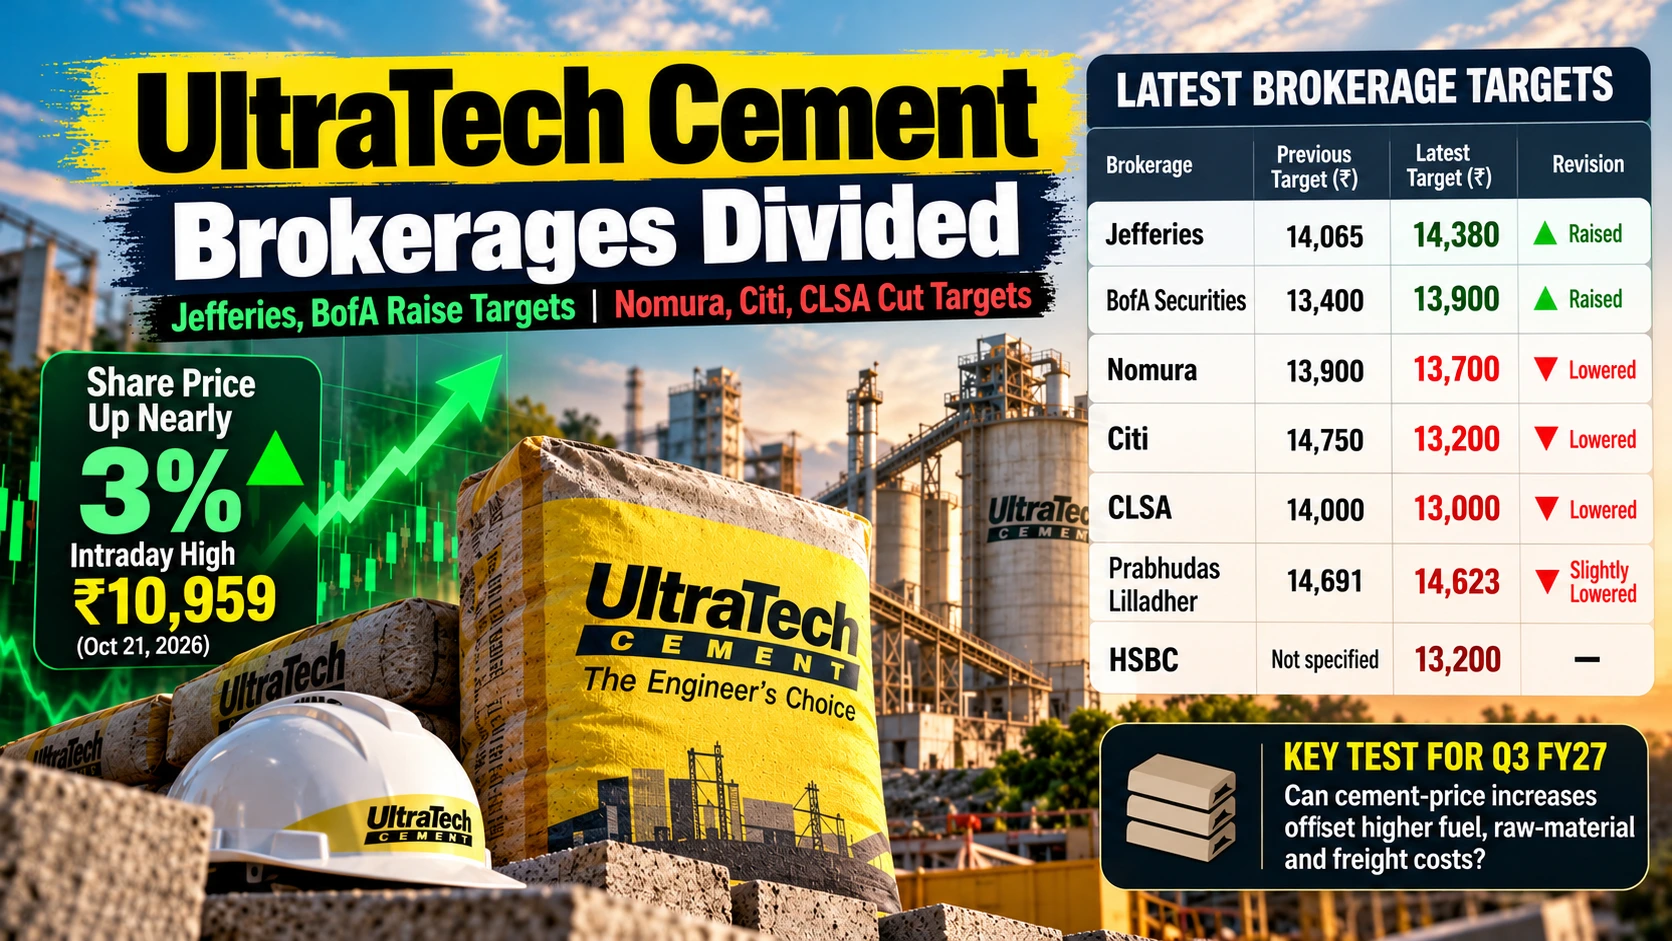
Jefferies and BofA Securities raised their targets, while Nomura, Citi and CLSA cut theirs. The key test is whether cement-price increases can offset higher costs in Q3 FY27.
October 21, 2026
UltraTech Cement shares rose nearly 3% in intraday trade on Wednesday, October 21, touching ₹10,959 as investors reassessed the company following its Q2 FY27 results and a fresh round of brokerage revisions. The recovery came even as analysts remained divided over the stock’s valuation and the timing of an improvement in profitability.
At 10:59 a.m. IST, Business Standard reported a BSE quote of ₹10,879, up 2.44%, and an NSE quote of ₹10,890, up 2.25%. The stock’s intraday high was ₹10,959. These are time-stamped market snapshots, not closing prices.
The latest brokerage assessments show a clear difference in expectations. Jefferies and BofA Securities raised their target prices, while Nomura, Citi, CLSA and Prabhudas Lilladher lowered theirs. HSBC’s reported target price stands at ₹13,200, although the cited report does not specify whether it was revised.
The disagreement centres on a critical earnings question: can stronger cement demand and higher selling prices offset rising fuel, raw-material and freight costs? UltraTech’s sales volumes are growing, but the pace of margin recovery remains uncertain.
UltraTech Cement Share Price: Seven Brokerage Targets Compared
| Brokerage | Previous target | Latest reported target | Revision |
|---|---|---|---|
| Jefferies | ₹14,065 | ₹14,380 | Raised |
| BofA Securities | ₹13,400 | ₹13,900 | Raised |
| Nomura | ₹13,900 | ₹13,700 | Lowered |
| Citi | ₹14,750 | ₹13,200 | Lowered |
| CLSA | ₹14,000 | ₹13,000 | Lowered |
| Prabhudas Lilladher | ₹14,691 | ₹14,623 | Slightly lowered |
| HSBC | Not specified | ₹13,200 | Previous target not established |
Sources: Economic Times’ brokerage report, NDTV Profit’s review and Moneycontrol’s Prabhudas Lilladher report.
The seven published targets range from ₹13,000 to ₹14,623, a difference of ₹1,623 per share. This is a spread between the estimates covered here, not a market-wide consensus or a guaranteed trading range. The estimates may also use different valuation assumptions and time horizons.
The direction of the revisions is equally important. Jefferies raised its target by approximately 2.2%, while BofA Securities increased its estimate by about 3.7%. In contrast, Citi cut its target by around 10.5%, and CLSA reduced its estimate by about 7.1%. Nomura and Prabhudas Lilladher made smaller reductions.
The split suggests that analysts are weighing the same broad operating signals differently: growth in cement volumes and an improvement in selling prices on one side and cost inflation on the other.
Track Live: ULTRATECH CEMENT Option Chain (NSE) — Live OI, PCR & Greeks
Jefferies and BofA Raise Targets as Pricing Momentum Improves
Jefferies raised its target price to ₹14,380 from ₹14,065. Its assessment highlighted volume growth, operating performance and the potential contribution from UltraTech’s next phase of organic capacity expansion.
The company has continued to add cement capacity and strengthen its distribution footprint. In Q2 FY27, domestic grey cement volumes increased 13.8% year-on-year to 35.94 million tonnes. Management has also indicated that another phase of organic expansion is expected to be announced.
For Jefferies, sustained improvement in cement pricing is an important catalyst. Higher capacity can help UltraTech serve more markets and capture demand, but the financial benefit ultimately depends on utilisation, selling prices and the cost of bringing additional capacity online.
BofA Securities raised its target to ₹13,900 from ₹13,400. Its assessment also pointed to demand growth and improved pricing momentum. The brokerage estimated that cement-industry demand grew by about 8% in the first half of the financial year, including approximately 10% in Q2.
Better demand can help manufacturers pass on higher operating costs. However, this remains conditional on pricing discipline across the industry and the ability of customers to absorb higher cement prices.
The two target increases therefore reflect the potential for an earnings recovery, not confirmation that the cost challenge has been resolved.
Why Nomura and Citi Cut Their UltraTech Cement Targets
Nomura lowered its target price to ₹13,700 from ₹13,900, even though Q2 operating EBITDA was approximately 7% above its estimate.
The better-than-expected performance was supported by volume growth and slightly improved realisations. Yet higher fuel and fixed costs pushed operating costs up 7% sequentially, around 5% more than Nomura had anticipated.
The brokerage also reduced its EBITDA estimates for FY27, FY28 and FY29 by 5%, 1% and 1%, respectively, while maintaining its grey cement volume estimates. Its assessment illustrates why stronger sales volumes do not necessarily translate into an equally strong earnings upgrade.
Citi made a larger reduction, lowering its target to ₹13,200 from ₹14,750. Its reported assessment highlighted the continuing cost burden but also pointed to a potential improvement in cement pricing.
Citi noted that spot cement prices were around 5% above the September quarter’s average. That offers a possible route to better realisations in Q3 FY27, provided the improvement persists and is reflected in the prices UltraTech actually earns.
The distinction between spot prices and realised prices matters. Spot prices can rise in selected markets without producing an equivalent increase across the company’s entire sales mix. The timing of price changes and regional competition will influence how much benefit reaches the reported earnings.
CLSA and HSBC Highlight the Cost-versus-Growth Trade-Off
CLSA cut its target price to ₹13,000 from ₹14,000, while its assessment continued to recognise UltraTech’s capacity and broader building-solutions opportunities.
One relevant development is the company’s entry into wires and cables. UltraTech’s official Q2 FY27 release confirms that it launched the Ultravolt business during the quarter and commissioned a manufacturing facility at Jhagadia, Gujarat. This is an existing launch, not merely a planned entry into the category.
The business broadens UltraTech’s building-products portfolio, although its contribution to earnings will depend on execution, distribution and customer adoption over time.
HSBC’s reported target price was ₹13,200. The available brokerage summary does not establish the previous target, so it is not possible to conclude from that report alone that the estimate was unchanged.
HSBC’s assessment also highlighted the effect of higher costs on market-share gains and the possibility that cement-price increases could offset some inflation. Its reported valuation analysis noted that the one-year forward enterprise value-to-EBITDA multiple was below its five-year average of 19.8 times.
This adds another layer to the debate: some analysts see scope for valuation support if profits recover, while others remain cautious about the pace at which better prices will translate into earnings.
Prabhudas Lilladher Watches EBITDA Per Tonne
Prabhudas Lilladher reduced its target slightly to ₹14,623 from ₹14,691.
Its assessment highlighted higher petcoke prices, freight expenses and other operating costs. The brokerage put operating EBITDA at ₹974 per tonne and drew attention to management’s objective of reaching ₹1,400 per tonne by March 2028.
That figure is a management target, not a guaranteed outcome. Reaching it would depend on higher realisations, cost control, volumes and the wider demand environment.
The metric is useful because EBITDA per tonne links the selling price and operating-cost story directly to profitability. If UltraTech’s selling prices rise faster than operating expenses, EBITDA per tonne could improve. If fuel, freight and raw-material costs remain elevated, the recovery may be slower than anticipated.
UltraTech Cement Q2 FY27: Strong Volumes, but Profit Missed Expectations
The September-quarter performance explains why the share-price rebound has not removed the debate over margins.
According to UltraTech’s official Q2 FY27 results, consolidated net sales rose 18.9% year-on-year to ₹23,024 crore from ₹19,371 crore. Consolidated profit after tax increased 21.3% to ₹1,501 crore from ₹1,238 crore.
Domestic grey cement volumes increased 13.8% to 35.94 million tonnes, while capacity utilisation improved to 71% from 66% a year earlier.
Reuters separately reported that profit attributable to owners of the parent was approximately ₹1,494 crore, below the LSEG analyst expectation of ₹1,705 crore. It also reported revenue from operations of approximately ₹23,295 crore and operating EBITDA of ₹974 per tonne. These figures use different reporting measures from the headline figures in UltraTech’s official release and should not be substituted for one another.
The cost picture is central to the earnings debate. Reuters reported that total expenses rose 17.8% year-on-year, while raw-material costs increased 24%.
Consequently, the company delivered strong year-on-year growth but did not satisfy the market’s earnings expectations. This gap between operating growth and the profit outcome helps explain why investors reacted cautiously after the results.
Also Read: UltraTech Cement Q2 FY27: Profit Up 21% YoY, Down 42.5% QoQ
Can Cement-Price Increases Improve Q3 FY27 Margins?
UltraTech’s next results will provide a clearer test of whether better selling prices can offset the cost burden.
The reported improvement in October spot cement prices offers a potential tailwind. Management has also indicated that further price improvement is expected over the following couple of months. Brokerages generally see pricing as an important variable for Q3 profitability.
Three factors will determine whether that optimism translates into stronger earnings.
First, price increases must hold. An improvement in spot prices will matter more if it translates into better realised prices across regions and customer segments.
Second, operating costs must stabilise relative to selling prices. If fuel, petcoke, freight and other expenses rise rapidly, they can absorb a large share of the benefit from higher prices.
Third, demand needs to remain resilient. Housing, infrastructure and private investment can support volumes, but weaker rural activity or a slowdown in construction could make price increases harder to sustain.
The forward-looking risk is that the market may be pricing in a margin recovery before the full earnings benefit becomes visible. If prices hold and costs moderate, UltraTech could improve profitability per tonne. If costs remain high or price increases weaken, earnings expectations may need further adjustment.
Also Check: ULTRATECH CEMENT Options Chart
What UltraTech Cement Investors Should Watch Next
The October 21 rebound shows that the market is reassessing UltraTech after its Q2 results. It does not establish that the earnings concerns have disappeared.
The strongest positive signals are double-digit sales growth, higher cement volumes and improving reported spot prices. The key negatives are the profit miss against analyst expectations, faster growth in raw-material costs and the uneven direction of brokerage target revisions.
For shareholders, the next decisive evidence will come from realised cement prices, fuel and freight costs, operating EBITDA per tonne and the company’s ability to translate capacity growth into profitable sales.
The brokerage spread also shows why target prices should be treated as estimates rather than precise forecasts. Jefferies and BofA Securities are more optimistic in their revisions, while Nomura, Citi and CLSA have become more cautious. HSBC’s reported target is available, but its previous target is not established in the cited report.
UltraTech’s long-term scale remains a strength, but the near-term stock outlook will depend on the quality of its earnings recovery—not volume growth alone.
Read Next: Stocks to Watch Oct 21: Jio IPO Opens; Bajaj Finance, Hindustan Zinc in Focus
Frequently Asked Questions
Why did UltraTech Cement shares rise nearly 3% on October 21, 2026?
The stock touched ₹10,959 in intraday trade as investors reassessed its Q2 FY27 results and new brokerage target prices. The movement was an intraday recovery and should not be treated as the closing return.
Which brokerage has the highest target price in this comparison?
Prabhudas Lilladher has the highest published target among the seven brokerages covered, at ₹14,623 per share. This is an analyst estimate, not a guaranteed future price.
Why did Citi reduce its target price for UltraTech Cement?
Citi lowered its target to ₹13,200 from ₹14,750. Its reported assessment highlighted operating-cost pressures, with the potential benefit from higher cement prices remaining an important condition for future earnings.
What is the biggest risk for UltraTech Cement in Q3 FY27?
The main risk is that fuel, raw-material and freight costs could offset the benefit from higher cement prices. The extent of margin recovery will depend on realised prices, demand and cost trends.
What should investors monitor after the Q2 results?
Important indicators include cement-price realisations, operating EBITDA per tonne, fuel and freight expenses, volume growth and capacity utilisation. The next quarterly results will help show whether pricing improvement is translating into stronger operating profitability.
Disclaimer
This article is for informational and educational purposes only and is not investment advice. Brokerage target prices represent analysts’ estimates and are not guaranteed future market prices. Investors should review company disclosures, assess their own risk tolerance and consult a qualified financial adviser before making investment decisions.