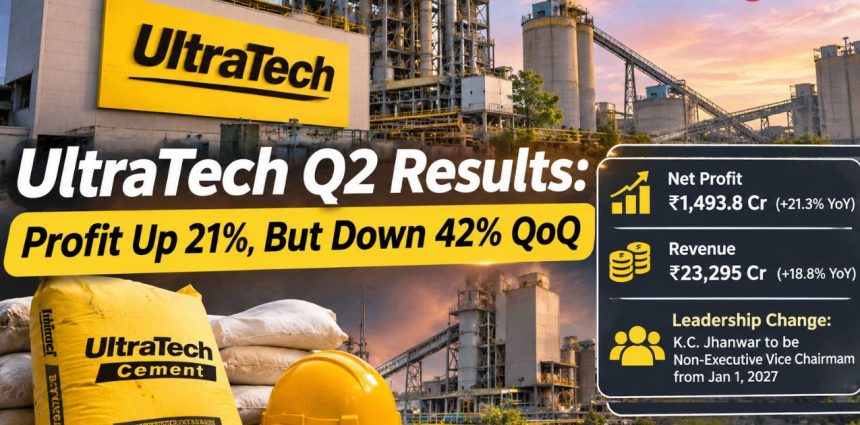
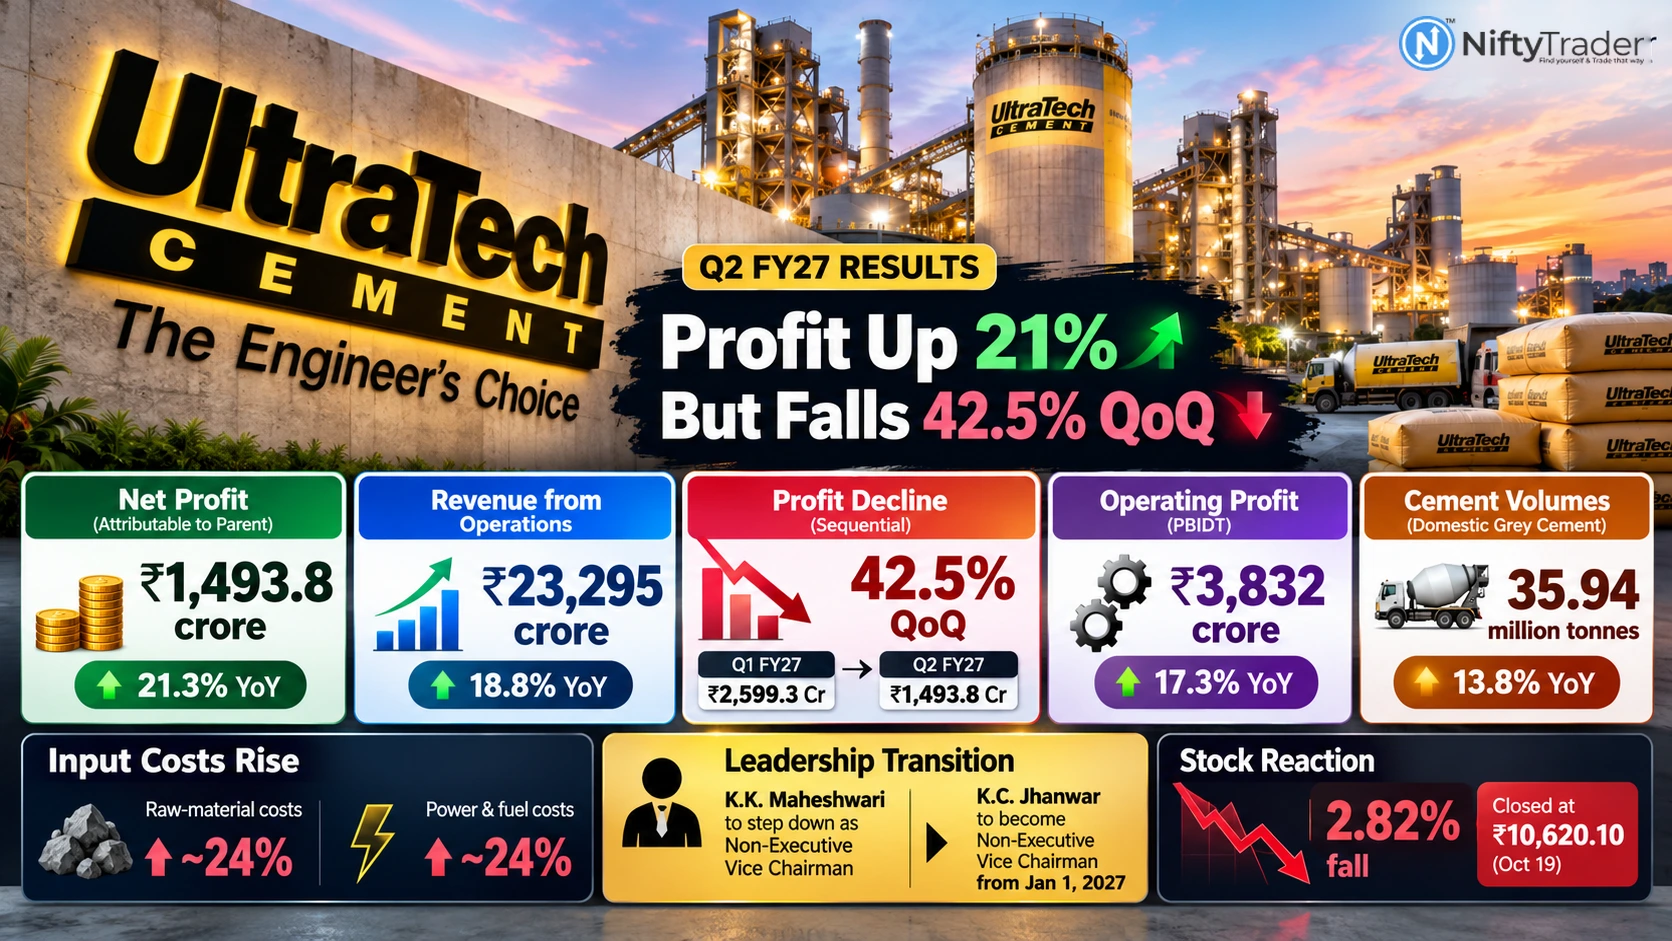
UltraTech Cement’s September-quarter results delivered two different signals: consolidated net profit attributable to parent shareholders rose 21.3% year-on-year to ₹1,493.77 crore, but fell 42.5% from the June quarter. Revenue from operations increased 18.8% to ₹23,295 crore, yet the company missed analysts’ profit expectations and its shares closed 2.82% lower on October 19.
Separately, UltraTech announced a board-level leadership transition, with K.C. Jhanwar set to become Non-Executive Vice Chairman from January 1, 2027, as K.K. Maheshwari steps down from the role.
The concern is not a lack of sales growth. Domestic cement volumes increased 13.8%, but raw-material and power-and-fuel costs climbed around 24% each. The next test for UltraTech Cement’s Q2 FY27 results is whether cement-price increases and stronger construction demand can support operating profitability in the coming quarters.
UltraTech Cement Q2 FY27 Results: 5 Numbers That Matter
According to the company’s official financial results filing, the September-quarter performance included the following:
- Profit attributable to parent shareholders: ₹1,493.77 crore, up 21.3% year-on-year.
- Total consolidated net profit: ₹1,501.38 crore, compared with ₹1,237.98 crore in the year-ago quarter.
- Revenue from operations: ₹23,295.07 crore, up 18.8% year-on-year.
- Operating profit before interest, depreciation and tax (PBIDT): ₹3,832 crore, up 17.3%.
- Domestic grey cement sales volume: 35.94 million tonnes, up 13.8% from 31.58 million tonnes.
UltraTech separately reported consolidated net sales of ₹23,024 crore, an increase of 18.9%. Revenue from operations and net sales are different reported measures and should not be treated as interchangeable.
Track Live: ULTRATECH CEMENT Option Chain (NSE) — Live OI, PCR & Greeks
The Bigger Signal: Profit Rose 21%, but Fell 42.5% From Q1
The year-on-year figures look encouraging, but the sequential comparison tells a more cautious story.
Profit attributable to parent shareholders declined to ₹1,493.77 crore in Q2 FY27 from ₹2,599.28 crore in Q1 FY27, a fall of approximately 42.5%. Revenue from operations dropped 5.5% quarter-on-quarter to ₹23,295 crore from ₹24,648 crore, while PBIDT decreased to ₹3,832 crore from ₹5,146 crore.
This comparison needs context. The September quarter was affected by monsoon-related disruptions, and domestic grey cement volumes were lower than the 39.2 million tonnes reported in Q1. Weather-related disruptions, seasonal demand patterns and the strength of the preceding quarter can all affect sequential results.
The year-on-year picture is materially different. For the first half of FY27, total consolidated net profit reached ₹4,105.10 crore, compared with ₹3,458.89 crore in the corresponding period last year. That represents growth of approximately 18.7%.
What the numbers indicate: UltraTech continues to deliver strong annual growth, but the June-to-September slowdown means investors will want evidence that earnings can strengthen again as seasonal demand improves.
Why Did UltraTech Cement Shares Fall After the Results?
UltraTech Cement shares closed at ₹10,620.10 on October 19, down 2.82% for the session, according to MarketWatch’s closing-market report. The Sensex also declined 1.17%, so the broader market added to the negative backdrop.
However, the company’s earnings miss was a separate concern.
Reuters reported that LSEG data put analysts’ expected profit at approximately ₹1,705 crore. The reported ₹1,493.77 crore attributable to parent shareholders came in about ₹211 crore, or 12.4%, below that estimate.
Revenue told a different story. Revenue from operations of ₹23,295 crore exceeded the LSEG-reported expectation of approximately ₹22,378 crore.
The distinction matters. UltraTech generated more revenue than analysts expected, but it did not convert that performance into the level of profit they had forecast.
The stock also experienced a sharp reversal during the session. Business Standard reported that the share price fell as much as 5.3% from the day’s high after the results before ending the session lower.
The market reaction therefore reflected both a profit shortfall and wider market weakness rather than an absence of business growth.
UltraTech Cement Announces Board-Level Leadership Change
Alongside its Q2 FY27 earnings, UltraTech Cement announced a change in its board composition, effective January 1, 2027.
According to the company’s official stock-exchange filing dated October 19, K.K. Maheshwari will relinquish his position as Non-Executive Vice Chairman from January 1, 2027, citing his current professional engagements and other personal commitments. His accompanying letter also states that he intends to relinquish his position as a Non-Executive Director.
Kailash Chandra Jhanwar, currently UltraTech’s Managing Director, will become Non-Executive Vice Chairman from the same date. His current term as Managing Director ends on December 31, 2026. The board approved his redesignation based on the recommendation of the Nomination, Remuneration and Compensation Committee.
What investors need to know: This is a confirmed board-level transition, but the filing does not name a successor to Jhanwar as Managing Director. Investors may watch for further announcements regarding the executive leadership structure, although the board change alone does not establish a change in the company’s business strategy or operating outlook.
The announcement is a relevant development alongside the earnings report, but its financial implications cannot be determined from the disclosed information alone.
Input Costs Are the Pressure Point
UltraTech’s expense breakdown shows why strong sales growth did not produce a bigger earnings surprise.
Total expenses increased 17.8% year-on-year to ₹21,338.88 crore. Two major cost categories rose faster:
- Cost of materials consumed: ₹4,208.23 crore, up approximately 24.4% year-on-year.
- Power and fuel expenses: ₹5,511.06 crore, up approximately 24%.
These expenses matter because cement production requires substantial energy and raw materials. Higher fuel, power and material costs can absorb some of the additional revenue generated through higher sales volumes.
PBIDT increased 17.3%, below the 18.9% rise in net sales. That gap points to pressure on the operating return generated by each rupee of sales, although it should not be interpreted as a collapse in profitability.
There is a positive counterpoint. Reuters reported that operating EBITDA per tonne improved by ₹60 year-on-year to ₹974. This indicates better operating earnings per tonne even as the overall cost base increased.
The takeaway is nuanced: UltraTech’s larger sales base and per-tonne performance are supporting earnings, but input-cost inflation continues to limit the upside.
Cement Price Hikes Could Decide the Next Quarter
Cement pricing is one of the most important factors to watch after these results.
Reuters reported that analysts at JM Financial estimated average cement prices increased by ₹6–₹7 per bag in the second half of September as manufacturers sought to pass on higher fuel costs.
Analysts have also anticipated further price increases after the festive season as construction activity improves. However, these are industry estimates and expectations, not a confirmed UltraTech management forecast or a guarantee that all price increases will hold.
That distinction is crucial.
Higher prices can help cement manufacturers recover fuel and material costs, but only if demand remains sufficient and customers accept the increases. If construction activity stays weak or announced hikes fail to hold, manufacturers may continue to face pressure on profitability.
After the festive season, investors will therefore be watching three related developments: whether construction demand strengthens, whether higher prices stick, and whether improved realisations translate into better operating margins.
Volumes and Capacity Expansion Remain the Positive Story
Despite the monsoon-affected quarter, UltraTech’s domestic grey cement volumes increased to 35.94 million tonnes from 31.58 million tonnes a year earlier. Capacity utilisation improved to 71% from 66%.
The company also commissioned 3.6 million tonnes per annum of new integrated cement capacity at Petnikota in Andhra Pradesh. Another 1.0 million tonnes per annum was added through debottlenecking at existing plants in Visakhapatnam, Patratu and Nathdwara.
As of September 30, 2026, UltraTech’s consolidated domestic grey cement capacity stood at 204.7 million tonnes per annum. Including overseas operations, global grey cement capacity reached 210.1 million tonnes per annum.
The company remains on track with its target of reaching more than 240 million tonnes per annum of capacity by March 2028.
This expansion increases UltraTech’s ability to serve demand across markets. But added capacity does not automatically guarantee higher profit. The returns depend on how quickly new output is absorbed, the prices the company can realise and the costs of operating and transporting the cement.
Can Green Energy Help Offset Cost Pressure?
UltraTech is also expanding its use of alternative and renewable power.
During Q2 FY27, the company reported a renewable power capacity of 1,580 megawatts and a waste heat recovery system capacity of 444 megawatts.
Together, these sources accounted for 48% of the company’s power mix during the quarter, according to its results-related disclosures.
For a power-intensive industry, a greater contribution from renewable energy and waste heat recovery can improve energy resilience and help reduce dependence on conventional sources. The actual benefit to earnings will depend on operating efficiency, investment costs and prevailing energy prices.
UltraTech also launched UltraVolt, its wires and cables business, broadening its building-products portfolio. The company commissioned a manufacturing facility at Jhagadia, Gujarat, as part of this expansion. However, the available Q2 results do not separately quantify the new business’s financial contribution, so it should be viewed as a longer-term strategic development rather than a demonstrated driver of the quarter’s earnings.
Also Check: ULTRATECH CEMENT Options Chart
What Investors Should Watch After UltraTech Cement Q2 Results
The next earnings update will be important for determining whether the current mix of volume growth and cost pressure begins to improve.
Cement prices: Are recent increases being sustained across regions, or are dealers struggling to pass them on?
Input costs: Do material, power and fuel expenses begin to grow more slowly than revenue?
Demand and utilisation: Does post-monsoon construction activity translate into stronger volumes and better utilisation of installed capacity?
Profitability per tonne: Does UltraTech continue to improve earnings per tonne while expanding capacity?
Management commentary: What does the company indicate about pricing discipline, demand recovery and the pace of capacity expansion?
Executive leadership: Does UltraTech make a further announcement about the Managing Director position before Jhanwar’s current term ends on December 31, 2026?
These measures provide a more complete picture than headline profit growth alone.
UltraTech Cement Q2 FY27 Results: The Bottom Line
UltraTech Cement’s September-quarter performance is a mix of strong annual growth and near-term pressure. Profit attributable to parent shareholders rose 21.3% year-on-year, revenue from operations climbed 18.8%, and domestic grey cement volumes increased 13.8%.
But profit missed the LSEG-reported estimate, sequential earnings fell sharply, and material and power-and-fuel expenses increased around 24% each.
The board-level leadership change adds another development for investors to track, although the announcement does not by itself indicate a change in UltraTech’s operating outlook.
The next phase of the UltraTech story depends on whether stronger construction demand and sustained cement-price increases can help offset those costs. If pricing improves while volumes remain healthy, profitability could strengthen. If cost pressure persists and price hikes are not fully absorbed, earnings growth may remain constrained.
For investors, the most important signal to watch is not simply how much cement UltraTech sells, but how much profit it can generate from each tonne as demand and pricing evolve.
Read Next: Hindustan Zinc Q2 FY27 Results: ₹6,412 Crore Profit Faces a New Test After Cost Guidance Cut
Frequently Asked Questions
1. What was UltraTech Cement’s Q2 FY27 profit?
UltraTech Cement reported total consolidated net profit of ₹1,501.38 crore. Profit attributable to parent shareholders was ₹1,493.77 crore, up 21.3% year-on-year.
2. Why did UltraTech Cement shares fall after the results?
The company missed the LSEG-reported analyst profit estimate despite stronger-than-expected revenue. Higher material and power-and-fuel expenses, along with weakness in the broader market, also shaped the share-price reaction.
3. Why did UltraTech Cement’s profit fall quarter-on-quarter?
Parent-attributable profit declined approximately 42.5% from Q1 FY27. Lower sequential revenue and volumes contributed to the slowdown, with the September quarter affected by monsoon-related disruptions.
4. What should investors watch after the Q2 results?
Investors should track cement-price increases, raw-material and fuel costs, post-monsoon demand, capacity utilisation and operating profit per tonne. These factors will help determine whether annual earnings growth can be sustained.
5. What leadership change did UltraTech Cement announce?
K.K. Maheshwari will relinquish his position as Non-Executive Vice Chairman effective January 1, 2027. Kailash Chandra Jhanwar, whose Managing Director term ends on December 31, 2026, has been approved to become Non-Executive Vice Chairman from January 1. The filing does not name a successor to Jhanwar as Managing Director.
Disclaimer: This article is for informational purposes only and is not a recommendation to buy or sell any security.