Banks bid ₹1,50,735 crore in the seven-day auction as tighter daily CRR rules complicate liquidity management. The funding operation does not signal a policy-rate cut.
October 19, 2026
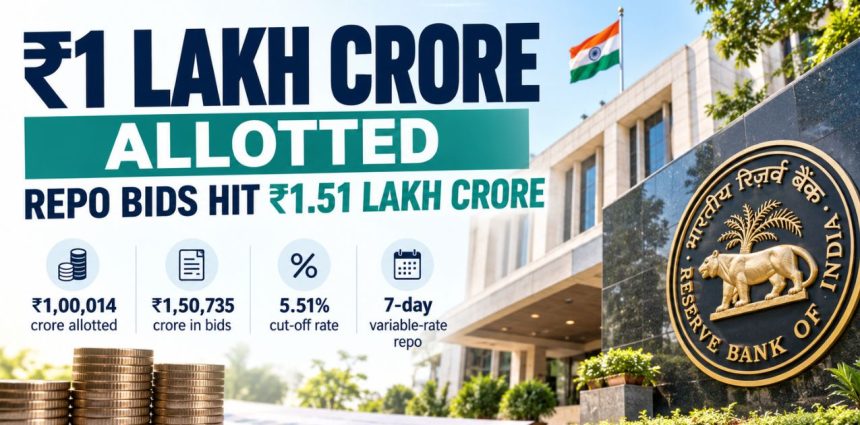
The Reserve Bank of India (RBI) allotted ₹1,00,014 crore in its seven-day variable-rate repo auction on Monday, October 19, after banks submitted bids worth ₹1,50,735 crore. The result shows demand substantially exceeded the notified amount, even as the central bank continues to manage liquidity through tighter daily cash-reserve requirements and other operations.
The RBI had notified ₹1 lakh crore for the auction. The cut-off rate was 5.51%, while the weighted-average rate was 5.52%. The seven-day operation is scheduled to mature on October 26, making the funding temporary rather than a permanent addition to banking-system liquidity.
The result comes after the RBI raised the minimum daily cash reserve ratio (CRR) maintenance requirement from 90% to 99% of the prescribed requirement, effective from the fortnight beginning October 16. The overall CRR remains unchanged at 3%.
The timing creates a significant question for money markets: why did banks bid around 1.51 times the notified amount when the banking system had recently reported substantial surplus liquidity?
Market participants cited in a Reuters report published by The Economic Times linked the operation to tax-related outflows and the tighter daily reserve requirement. That is a market interpretation of the RBI’s motive, not a separately confirmed explanation from the central bank. The auction result establishes strong bidding for this operation, but it does not by itself prove that the entire banking system is facing a cash shortage.
Also Read: RBI Repo Rate Hiked to 5.5%, First Increase Since 2023
Need to Know
- Actual allotment: ₹1,00,014 crore, effectively the full notified amount of ₹1 lakh crore.
- Total bids received: ₹1,50,735 crore, around 1.51 times the notified amount.
- Auction rates: The cut-off rate was 5.51%, and the weighted-average rate was 5.52%.
- Maturity: The seven-day operation is scheduled to mature on October 26, 2026.
- CRR change: Minimum daily maintenance rose from 90% to 99% of the prescribed CRR from October 16; the overall CRR remains 3%.
- Policy implication: The operation provides temporary liquidity and does not automatically mean lower loan rates, lower EMIs or a reversal of monetary tightening.
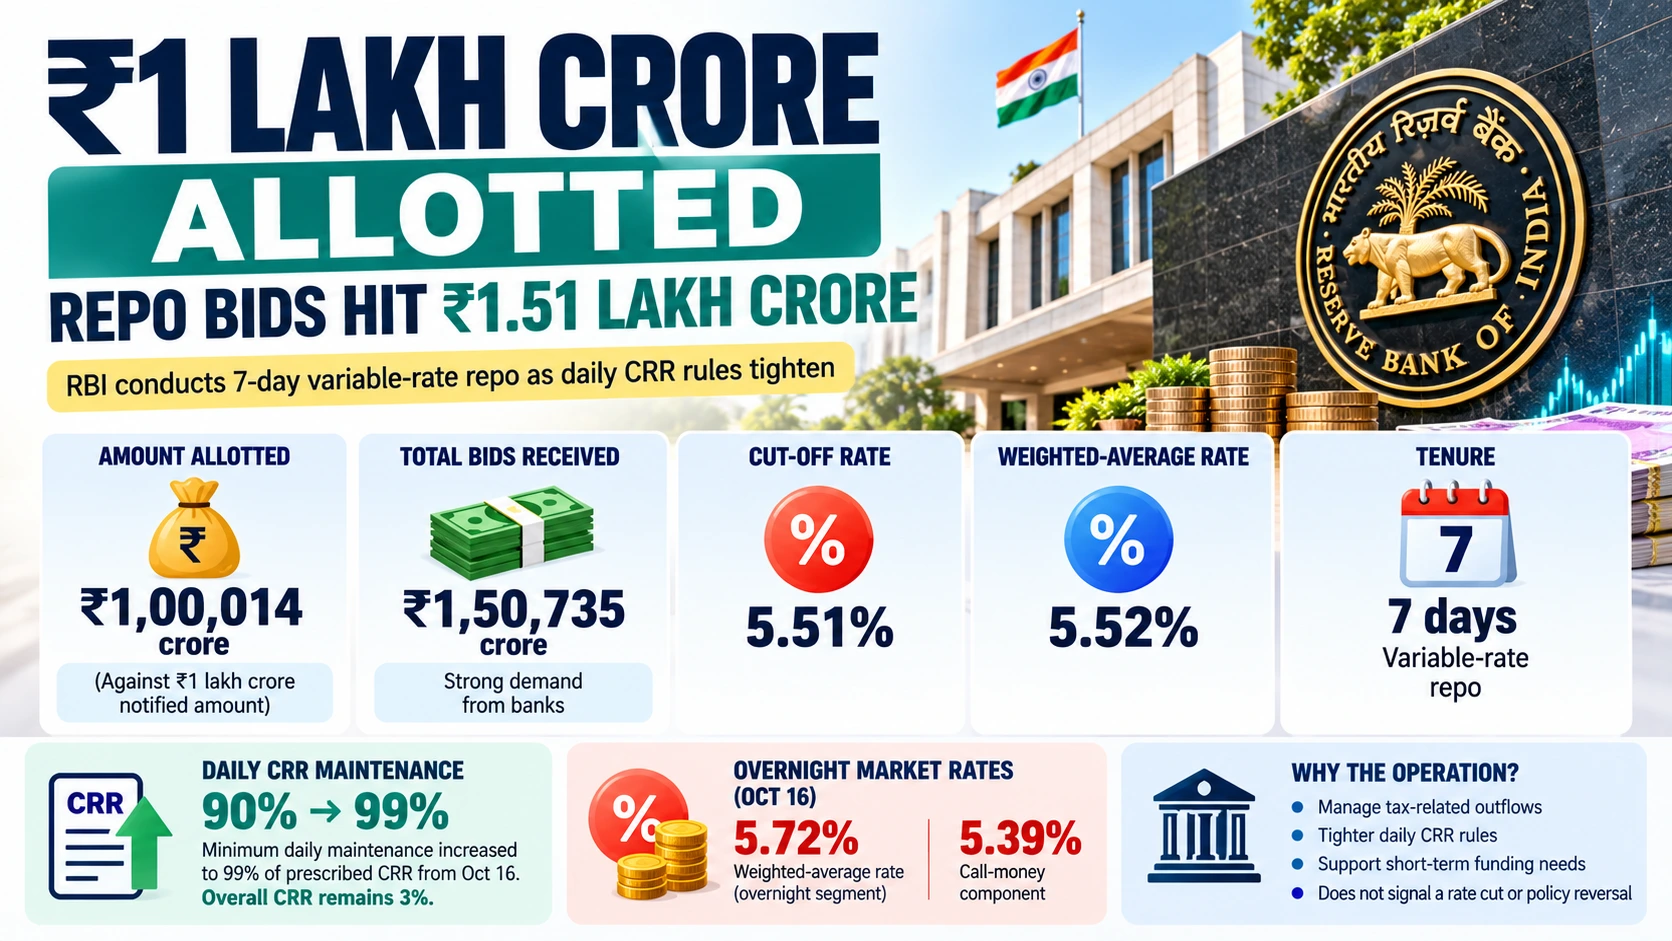
Source: RBI’s official October 19 auction result and RBI money-market operations data for October 16.
RBI repo auction: What the numbers reveal
| Auction detail | October 19 result |
|---|---|
| Notified amount | ₹1,00,000 crore |
| Total bids received | ₹1,50,735 crore |
| Amount allotted | ₹1,00,014 crore |
| Cut-off rate | 5.51% |
| Weighted-average rate | 5.52% |
| Tenure | 7 days |
| Scheduled maturity | October 26, 2026 |
Banks submitted bids worth approximately ₹50,735 crore more than the notified amount. That works out to roughly 50.7% more than the amount offered, indicating strong demand for funds in this particular auction.
The distinction between bids and allotments matters. Banks collectively requested substantially more money than the RBI made available, but the central bank allotted approximately the notified amount. The result is evidence of significant auction demand; it is not, on its own, a measure of the banking system’s total liquidity deficit.
The cut-off rate of 5.51% was one basis point above the 5.50% policy repo rate, while the weighted-average rate was two basis points higher. These figures show that the auction cleared close to the policy benchmark.
The RBI’s official auction-result release confirms the notified amount, bids, allotment and both rates.
Why the RBI tightened daily CRR rules
The repo auction follows an RBI notification dated October 9 that changed how closely banks must maintain their prescribed cash reserves each day.
From the reporting fortnight beginning October 16, scheduled banks must maintain at least 99% of their prescribed CRR on each day, compared with the previous minimum of 90%. The overall CRR remains 3% of net demand and time liabilities.
This distinction is crucial. The RBI has not increased the overall CRR to 99%. It has raised the minimum daily maintenance requirement to 99% of the existing prescribed reserve.
Previously, banks had more room to hold a lower reserve balance on certain days and compensate through higher balances elsewhere in the reporting fortnight, subject to the applicable average requirement. The revised rule reduces that operational flexibility.
CRR balances are maintained with the RBI and do not earn interest. Maintaining a larger share of the prescribed reserve each day can therefore affect how banks manage available funds and their short-term funding requirements.
The RBI’s notification, RBI/2026-27/290 dated October 9, states that the minimum daily maintenance requirement was increased after a review of prevailing liquidity conditions.
This makes the timing of the repo operation important. Market participants have linked the funding window to the combined effect of tax-related outflows and reduced flexibility under the new reserve rule. However, the rule change and the auction result should not be treated as proof of a system-wide shortage of funds.
The liquidity puzzle: Why bid heavily when surplus cash exists?
India’s banking system had recently reported a substantial aggregate liquidity surplus. On October 9, Moneycontrol reported that average daily surplus liquidity under the liquidity adjustment facility had stood at ₹5.9 lakh crore since the previous monetary policy meeting in August. Its report also put the system-wide surplus at about ₹3.92 lakh crore on the preceding Thursday.
These are dated aggregate measures, not a guarantee that every bank has surplus cash available on every day.
Liquidity can be unevenly distributed. Tax payments, government balances, settlement obligations and interbank flows may temporarily leave some lenders requiring funds even when the wider system has a surplus. Tighter daily CRR maintenance can make those timing mismatches harder to manage.
This is why the auction result is worth watching. Banks submitted ₹1,50,735 crore in bids against a ₹1 lakh crore notified amount, and the RBI allotted approximately the full amount.
But strong bidding should be interpreted carefully. It indicates that participating banks collectively sought substantial funds through the auction. It does not establish how much each bank needed, whether all bids reflected immediate cash shortages, or whether the banking system as a whole had shifted into a deficit.
The key question is whether the repo operation smooths short-term funding conditions or whether further operations become necessary as liquidity flows change.
Overnight rates show another side of the story
RBI money-market data for October 16 offer useful context because the reported overnight rates differed across market segments.
The weighted-average rate for the combined overnight market segment was 5.72%, while the separate call-money component averaged 5.39%. The two figures measure different segments and must not be used interchangeably.
The overnight segment includes call money, triparty repo, market repo and corporate-bond repo transactions. Call money is only one component of that wider market.
The RBI’s policy corridor at the time was bounded by the Standing Deposit Facility (SDF) rate of 5.25% and the Marginal Standing Facility (MSF) rate of 5.75%, with the policy repo rate at 5.50%. The combined overnight-segment rate of 5.72% was close to the top of the corridor, while the call-money rate remained below the policy repo rate.
The reported transaction-rate range of 4.00% to 6.00% for the combined overnight segment is not the same as the RBI’s policy corridor. It records the observed range of transactions across the included instruments.
The same October 16 data showed net absorption of approximately ₹1,51,299 crore through that day’s RBI operations, including ₹1,58,474 crore placed through the SDF. This daily operating flow should not be confused with the aggregate banking-system liquidity surplus.
Together, the figures illustrate why liquidity management is not simply a matter of whether the system has excess funds. The timing of flows, distribution of cash and cost of overnight funding can all matter.
Source: Money Market Operations as on October 16, 2026, based on RBI and Clearing Corporation of India data.
Why the repo operation does not reverse monetary tightening
The latest auction needs to be viewed against the RBI’s broader policy direction.
On October 7, the Monetary Policy Committee increased the policy repo rate by 25 basis points to 5.50% and changed its stance to calibrated tightening. The RBI’s policy communication said that rate cuts were off the table in the near term, with the next move dependent on economic and inflation developments.
The central bank has also used operations that absorb liquidity. It announced a ₹25,000 crore open-market government-securities sale in October as part of its efforts to manage surplus liquidity.
A repo operation and an outright bond sale work differently. The repo provides temporary funds against eligible collateral; an outright sale of government securities absorbs liquidity from the banking system.
These measures are not necessarily contradictory. The RBI can supply short-term funds to address immediate funding needs while using other instruments to manage excess liquidity and maintain the transmission of monetary policy.
For that reason, the October 19 repo auction should not be read as a policy-rate cut or a clear signal that the RBI has abandoned its tighter stance.
What the auction means for banks, borrowers and investors
Banks: The operation gives eligible banks access to short-term RBI funding. The benefit depends on their cash positions, funding needs, auction rates and the cost of alternative borrowing. The higher daily CRR maintenance requirement may continue to influence how banks manage reserves.
Depositors: The auction does not automatically mean fixed-deposit rates will fall. Deposit pricing depends on competition for deposits, funding requirements and banks’ expectations for future interest rates.
Home-loan and other borrowers: The operation does not directly reduce the policy repo rate, which remains 5.50%. Lending rates and EMIs depend on each loan’s benchmark, reset terms and lender decisions. Some floating-rate loans may adjust when their contractual reset dates arrive, but the repo operation itself does not trigger an EMI cut.
Bank-stock investors: Strong repo bidding is not a standalone reason to expect bank shares to rise. Short-term liquidity may support cash management, but profitability still depends on deposit costs, lending spreads, loan growth, asset quality and valuations.
Bond investors: The temporary infusion may influence short-term funding conditions, but longer-term government bond yields also reflect expected inflation, future policy rates, government borrowing and investor demand. Liquidity relief alone does not guarantee falling bond yields.
Investors can also monitor institutional flows through the NiftyTrader FII-DII Tracker, although institutional equity flows are a separate indicator from banking-system liquidity.
What happens when the seven-day repo matures?
The operation is scheduled to mature on October 26. The funds therefore provide short-term support rather than a permanent addition to the banking system’s liquidity.
By maturity, tax-related outflows and other cash flows may have eased—or further funding needs may have emerged. If pressure persists, the RBI could conduct additional operations, depending on prevailing conditions and its policy objectives.
Three indicators will be important: subsequent RBI auction announcements, changes in overnight funding rates and updated liquidity data.
The allotment itself confirms that banks sought substantial funding through the October 19 auction. What remains uncertain is how much the operation will alter short-term market conditions and whether further support will be required after the funds mature.
For now, the result highlights the balance the RBI is trying to manage: providing funds when banks need short-term liquidity while maintaining tighter daily reserve rules and a calibrated-tightening policy stance.
The central takeaway is that banks took almost the full notified repo amount, but the auction is a liquidity-management measure—not evidence of a policy reversal or a guaranteed drop in borrowing costs.
Read Next: Stocks to Watch Today, Oct 19: YES Bank’s ₹5,217-Crore AT1 Risk, HDFC Bank and More
Frequently asked questions
1. How much did the RBI allot in the October 19 repo auction?
The RBI allotted ₹1,00,014 crore against a notified amount of ₹1 lakh crore. Banks submitted bids worth ₹1,50,735 crore. The cut-off rate was 5.51%, and the weighted-average rate was 5.52%. The operation has a seven-day tenure and is scheduled to mature on October 26.
2. Why did banks bid more than the amount offered?
Banks collectively submitted bids equal to about 1.51 times the notified amount. Market participants linked the timing to tax-related outflows and tighter daily CRR maintenance. However, strong bids do not by themselves prove that the banking system had a cash deficit.
3. Has the RBI raised the CRR to 99%?
No. The overall CRR remains 3% of banks’ net demand and time liabilities. The change effective from October 16 increased the minimum daily maintenance requirement from 90% to 99% of the prescribed CRR.
4. What do the 5.72% overnight rate and 5.39% call-money rate mean?
RBI data for October 16 show a weighted-average rate of 5.72% for the combined overnight market segment and 5.39% for the call-money component. The former includes multiple overnight funding instruments; the latter covers call-money transactions alone.
5. Will the RBI repo operation reduce home-loan EMIs?
Not automatically. The auction supplies temporary liquidity but does not reduce the 5.50% policy repo rate. Any change in a borrower’s interest rate depends on the loan benchmark, contractual reset date and the lender’s pricing decision.
6. Does the auction mean the RBI has reversed monetary tightening?
No. The RBI raised its policy repo rate to 5.50% on October 7 and adopted a calibrated-tightening stance. The temporary repo operation should be assessed separately from the broader direction of monetary policy.
7. When will the repo funds mature?
The operation has a seven-day tenure and is scheduled to mature on October 26, 2026. Subsequent liquidity conditions and any additional RBI operations will determine how funding conditions evolve after maturity.
Disclaimer: This article is for informational purposes only and is not investment advice. Auction outcomes and liquidity conditions can change; readers should verify official RBI disclosures and consider their financial circumstances before making investment decisions.