Capital Gains Tax Relief: SEBI’s LTCG Tax Proposal Could Change India’s Investment Landscape
Could a major tax relief proposal bring foreign investors back to the Indian stock market? The Securities and Exchange Board of India (SEBI) has reportedly recommended removing long-term capital gains (LTCG) tax for foreign investors as the government looks to revive equity market sentiment and attract overseas capital.
According to two sources familiar with the matter, SEBI has also proposed tax relief for domestic mutual fund investors who switch from existing schemes to new ones. The recommendations form part of the regulator’s pre-budget representations ahead of the Union Budget in February.
However, these proposals are not binding. The final decision rests with the government.
Track Live : GIFT Nifty Live – Today Price, Chart, Timings and Nifty Opening Signal
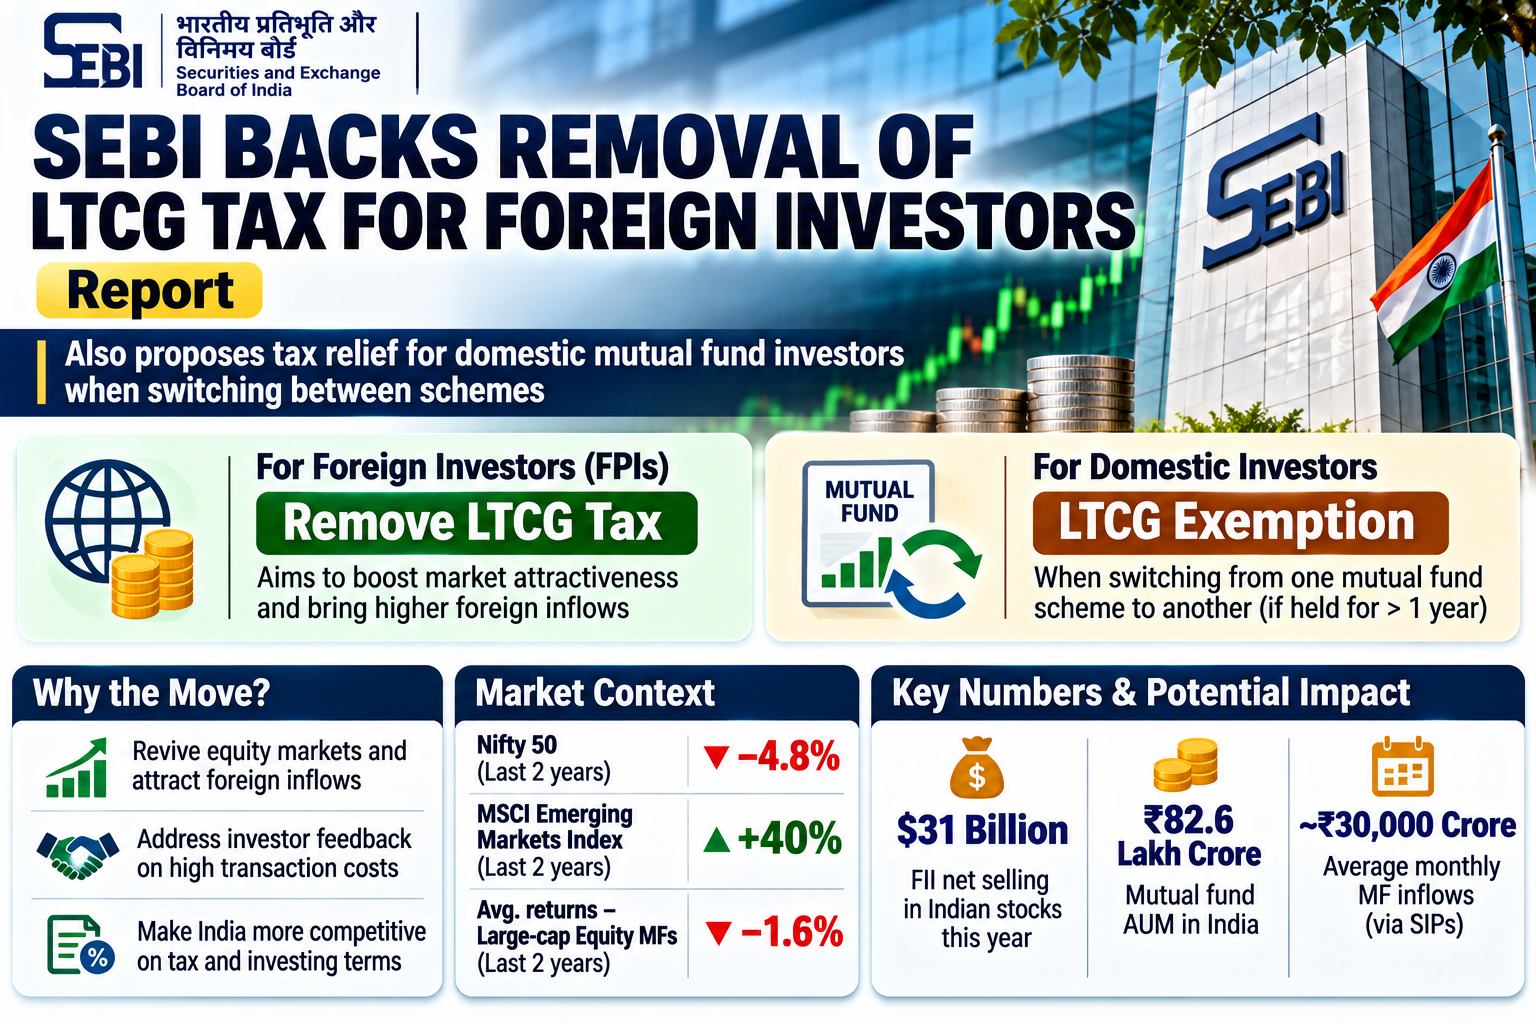
Capital Gains Tax Relief : Why SEBI Wants the Government to Scrap LTCG Tax for Foreign Investors
Currently, investors pay 12.5% LTCG tax on eligible securities held for more than one year. Short-term capital gains tax stands at 20%, apart from securities transaction tax and withholding taxes on dividends.
SEBI has highlighted that transaction costs associated with investing in Indian equities are among the highest across jurisdictions.
Removing LTCG tax for foreign investors could improve the attractiveness of Indian equities and potentially encourage fresh foreign portfolio investment (FPI) inflows.
Brokerage firm Jefferies has indicated that reducing capital gains taxes could support foreign investment in Indian markets.
IIFL estimates that scrapping capital gains tax could increase foreign investors’ returns by approximately 2.3 percentage points.
| Market indicator | Reported figure |
|---|---|
| Foreign investor stock selling in 2026 | $31 billion |
| Nifty 50 performance over two years | -4.8% |
| MSCI Emerging Markets performance over two years | +40% |
| IIFL estimated improvement in foreign investor returns from removing capital gains tax | 2.3 percentage points |
How much could foreign investors benefit?
Brokerage firm IIFL estimates that scrapping capital gains tax could improve foreign investors’ returns by approximately 2.3 percentage points.
For example, consider a hypothetical eligible long-term capital gain of ₹1 crore.
| Particulars | Current LTCG tax | Proposed exemption |
|---|---|---|
| Capital gain | ₹1 crore | ₹1 crore |
| Basic LTCG tax at 12.5% | ₹12.50 lakh | Nil |
| Gain after basic LTCG tax | ₹87.50 lakh | ₹1 crore |
SEBI’s two major tax proposals
The recommendations cover two different categories of investors: foreign portfolio investors and domestic mutual fund investors.
| Proposal | What SEBI has reportedly recommended | Potential benefit |
|---|---|---|
| Foreign investors | Remove LTCG tax on equity investments | Improve post-tax returns and attract foreign capital |
| Domestic mutual funds | Exempt eligible switches between schemes from LTCG tax if units are held for more than one year | Encourage investors to remain invested |
The recommendations were submitted as part of SEBI’s confidential pre-Budget representations. They are not binding on the government.
Track Live : NSE Option Chain — Live | BSE Option Chain — Live Sensex & Bankex Options Data Today
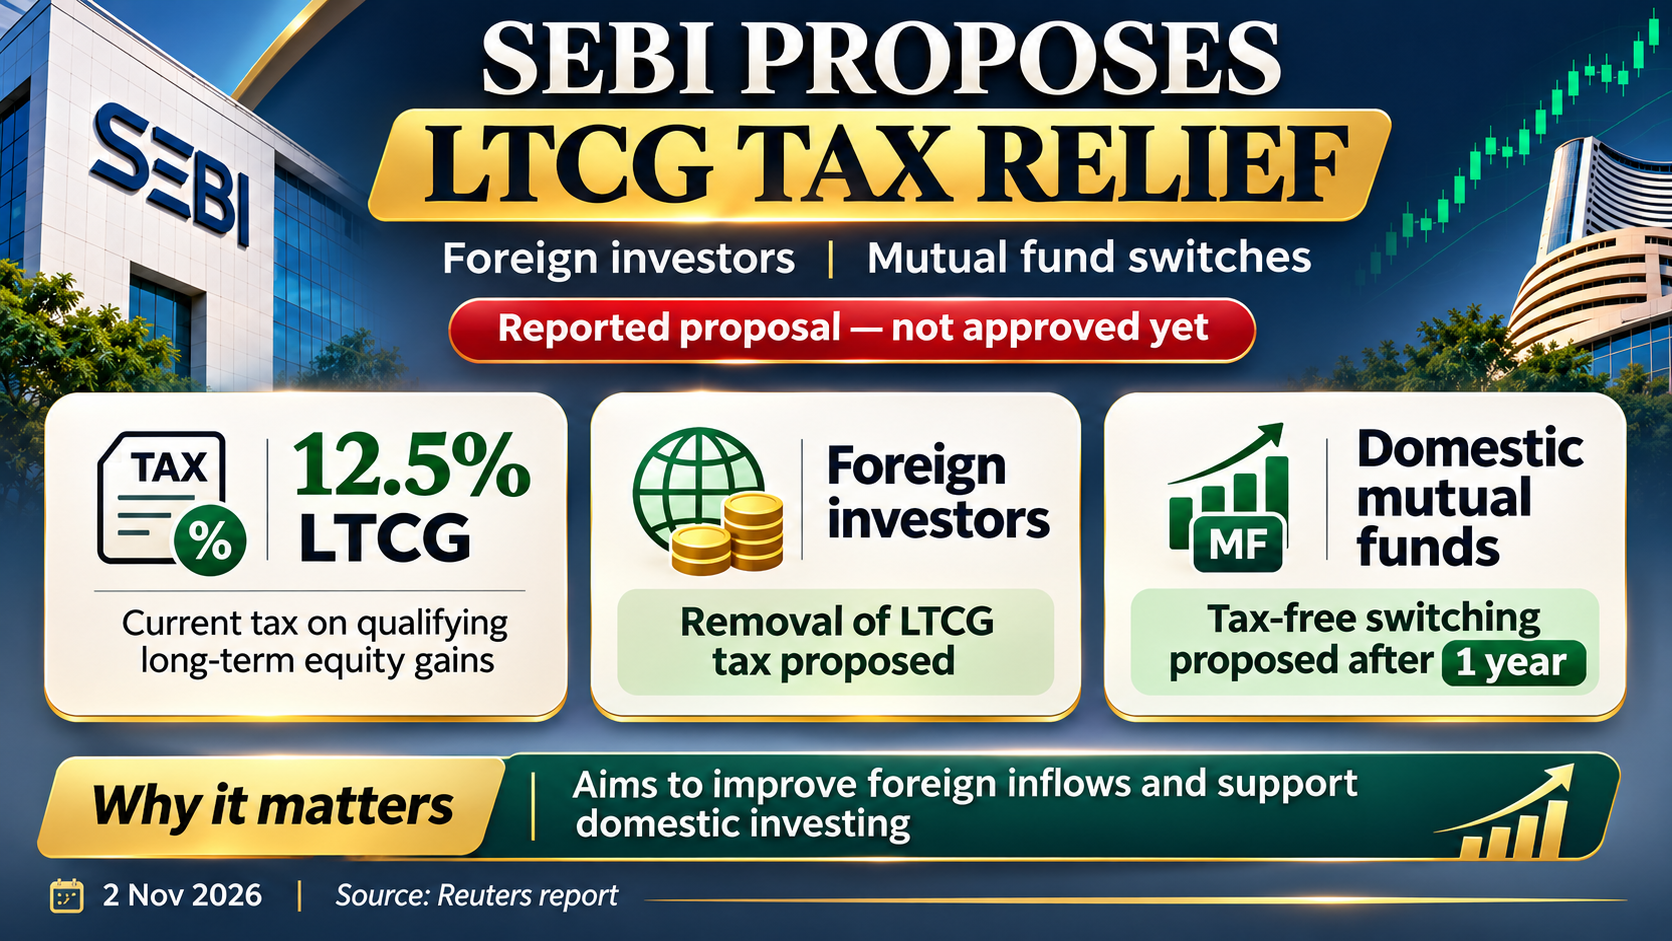
Current LTCG and STCG tax rates in India
This is an important detail to include because readers need to understand the tax relief being proposed.
| Type of capital gains | Current tax rate | Holding period |
|---|---|---|
| Long-term capital gains (LTCG) | 12.5% | More than 12 months |
| Short-term capital gains (STCG) | 20% | 12 months or less |
These rates apply to eligible listed equity investments subject to applicable conditions. Securities Transaction Tax (STT), applicable surcharges and cess, and dividend withholding taxes can add to the overall tax burden.
Domestic Mutual Fund Investors Could Also Receive Tax Relief
SEBI’s proposal is not limited to foreign investors. The regulator has reportedly suggested exempting domestic mutual fund investors from LTCG tax when switching between schemes, provided the existing units have been held for more than one year.
Currently, switching mutual fund schemes generally triggers capital gains tax because the transaction is treated as a redemption followed by a fresh investment.
The proposed exemption could make portfolio rebalancing more tax-efficient and encourage investors to remain invested in domestic mutual funds.
India’s mutual fund industry currently manages approximately ₹82.6 lakh crore in assets under management, with monthly investment schemes attracting an average of ₹30,000 crore in inflows.
The proposal could therefore have significant implications for the domestic investment industry.
Read More : Reliance Share Price: Goldman Sachs Sees 58% Upside as Value Tops Rs17 Lakh Crore
Example of the proposed benefit:
| Particulars | Current treatment | Proposed treatment |
|---|---|---|
| Original investment | ₹10 lakh | ₹10 lakh |
| Value at switching | ₹13 lakh | ₹13 lakh |
| Capital gain | ₹3 lakh | ₹3 lakh |
| LTCG tax on switch | Applicable, subject to exemption and conditions | Proposed to be deferred/exempted |
| Tax at the time of switching | Taxable event | No immediate LTCG tax, if proposal is approved |
Why does SEBI want to encourage domestic mutual fund investors?
Indian mutual funds have become an important source of domestic equity market investment.
| Indicator | Reported figure |
|---|---|
| Indian mutual fund industry AUM | ₹82.6 lakh crore |
| Monthly investment inflows through systematic investment schemes | Approximately ₹3,000 crore |
| Average large-cap equity mutual fund returns over the reported two-year period | -1.6% |
What Could the SEBI LTCG Proposal Mean for Stock Market Investors?
If the government accepts the recommendations, lower taxation could improve India’s competitiveness against other emerging markets.
Foreign investors may find Indian equities more attractive, potentially supporting FPI inflows, market liquidity and investor sentiment.
For traders, any positive developments around the Union Budget could become a market sentiment trigger. Banking, financial services and large-cap stocks could attract attention if foreign investment returns strengthen.
Domestic mutual fund investors could also benefit from greater flexibility when switching schemes without an immediate LTCG tax burden.
However, investors should remember that SEBI’s recommendations are not approved policy changes yet.
What happens next? Union Budget 2027 will be important
SEBI’s recommendations have been submitted ahead of the Union Budget scheduled for February 2027.
The next steps are:
-
The Finance Ministry will consider SEBI’s recommendations.
-
The government will evaluate the potential impact on tax revenues and investment flows.
-
Any changes will need to be formally announced and implemented through the appropriate budgetary and legislative process.
There is currently no official confirmation that the government will accept either proposal.
Finance Minister Nirmala Sitharaman has previously acknowledged investor concerns regarding LTCG and STT, but the government has not committed to reducing these taxes.
SEBI’s LTCG Tax Proposal: Four Additional Important Details Investors Should Know
The reported proposal to remove long-term capital gains (LTCG) tax for foreign investors has a wider significance beyond reducing their tax burden. India’s taxation history, international tax practices, currency fluctuations and potential government revenue implications are all important factors in understanding why SEBI is pushing for tax reforms ahead of the Union Budget 2027–28.
Here are the four additional points explained in detail, with information you can incorporate into your news article.
Historical background: How India’s LTCG tax changed from 2004 to 2024
India has changed its long-term capital gains tax policy on listed equities several times over the past two decades.
The government abolished LTCG tax on qualifying listed equity transactions in 2004 when Securities Transaction Tax (STT) was introduced. However, the exemption did not continue permanently.
-
2003: Temporary LTCG exemption introduced
The Union Budget 2003–04 introduced a temporary exemption for qualifying listed equity shares acquired on or after March 1, 2003, and sold after being held for at least one year.
-
2004: LTCG tax abolished
In the Union Budget 2004–05, the government abolished LTCG tax on qualifying listed equity transactions and introduced STT on stock exchange transactions. The new framework became operational on October 1, 2004.
-
2018: LTCG tax reintroduced at 10%
Finance Minister Arun Jaitley reintroduced LTCG tax through Section 112A. Gains exceeding ₹1 lakh from eligible listed equities and equity-oriented mutual funds were taxed at 10%, without indexation.
-
2024: LTCG tax increased to 12.5%
Finance Minister Nirmala Sitharaman increased the rate from 10% to 12.5% in the July 2024 Budget. The annual exemption threshold was also increased from ₹1 lakh to ₹1.25 lakh.
The short-term capital gains tax on eligible STT-paid equity transactions was also increased from 15% to 20% in July 2024.
International comparison: How Singapore, Hong Kong, the UAE and the US tax foreign investors
One of the major arguments behind SEBI’s recommendation is that India competes with international financial markets for overseas investment.
Some competing financial centres generally do not impose capital gains tax on investment gains of the same nature, although their tax rules and eligibility conditions differ.
Singapore: The Inland Revenue Authority of Singapore (IRAS) generally treats gains from selling shares and financial instruments as non-taxable capital gains. However, profits from trading activities can be taxable depending on the nature of the transactions.
Hong Kong: The territory generally does not tax capital gains. However, profits classified as revenue income or arising from trading activities can attract profits tax.
UAE: The Federal Tax Authority states that individuals are not subject to UAE corporate tax on dividends, capital gains and other investment income earned from owning shares or securities in their personal capacity.
United States: The IRS generally does not tax capital gains earned by non-resident aliens whose presence in the country is below 183 days in a calendar year. However, exceptions apply, including certain effectively connected income and other specific circumstances.