Nifty 50 Gainer SBI Shares Gain 1% as Brokerages See Strong Loan Growth and 25% Upside Potential
State Bank of India (SBI) shares moved higher on Thursday, emerging among the top gainers on the Nifty 50, after two leading global brokerages maintained their positive outlook on the country’s largest lender. CLSA and Goldman Sachs see opportunities for further growth in SBI’s loan book, supported by corporate capital expenditure, retail lending and an improving profitability outlook.
The bullish assessments have renewed investor attention on SBI’s growth strategy and earnings potential. However, with the stock already outperforming the broader market in 2026, investors will be watching whether the bank can translate its ambitious credit growth guidance into sustained profitability.
Track Live : NSE Option Chain — Live | BSE Option Chain — Live Sensex & Bankex Options Data Today
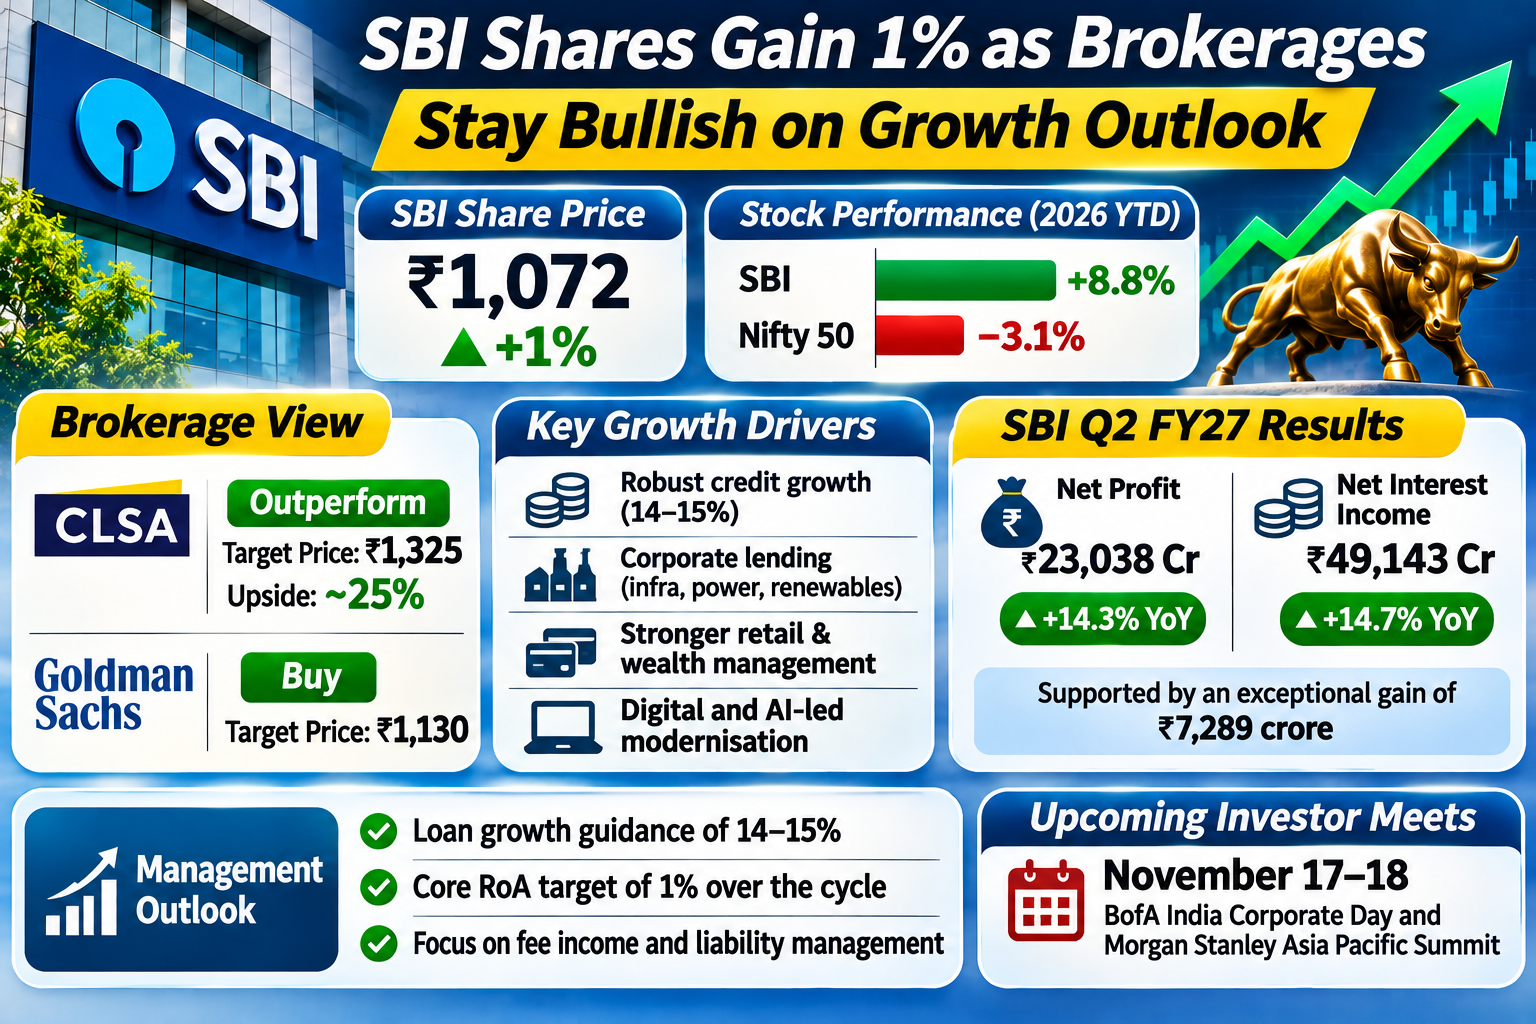
Nifty 50 Gainer: SBI Share Price Rises 1% as Brokerages Maintain Bullish Ratings
SBI shares gained around 1% in morning trade on Thursday, reaching approximately ₹1,072 and placing the stock among the leading Nifty 50 gainers. The bank’s market capitalisation stood at nearly ₹9.9 lakh crore.
The stock has advanced 8.8% so far in 2026, compared with a 3.1% decline in the Nifty 50 over the same period. This relative outperformance reflects investor interest in the lender’s earnings prospects and its ability to capture credit demand across business segments.
The latest positive commentary from CLSA and Goldman Sachs followed management interactions with institutional investors. Both brokerages highlighted SBI’s growth opportunities, while management acknowledged that matching the banking system’s projected credit expansion could be challenging because of the bank’s relatively large existing loan base.
SBI Share Price Rises 1%: Key Market Details
SBI shares were trading around ₹1,072 during Thursday morning deals, gaining approximately 1%.
The stock has reportedly gained 8.8% in 2026, outperforming the Nifty 50, which declined around 3.1% over the same period.
| Market Indicator | Details |
|---|---|
| Company | State Bank of India |
| Share price | ₹1,072 |
| Intraday gain | Around 1% |
| 2026 stock performance | +8.8% |
| Nifty 50 performance | -3.1% |
| Market capitalisation | Approximately ₹9.9 lakh crore |
| NSE symbol | SBIN |
The buying interest followed positive commentary from brokerages regarding SBI’s credit growth, profitability and long-term business opportunities.
Goldman Sachs Sees Opportunities in Retail Lending and Wealth Management
Goldman Sachs maintained its ‘Buy’ rating on SBI with a target price of ₹1,130 per share. Its assessment highlighted the bank’s plans to expand lending to self-employed individuals, strengthen wealth management operations and improve cross-selling across its customer base.
The brokerage also pointed to opportunities to deepen corporate and retail banking relationships. SBI’s plans to modernise operations through artificial intelligence and digital initiatives could further support efficiency and customer engagement.
Management retained its credit growth guidance of around 15%, while indicating that actual growth could exceed this level by a few percentage points.
| Business Area | SBI’s Focus |
|---|---|
| Retail lending | Expand loans to self-employed customers |
| Wealth management | Strengthen investment and advisory services |
| Cross-selling | Increase products offered to existing customers |
| Corporate banking | Deepen relationships with businesses |
| Digital banking | Improve customer experience |
| Artificial intelligence | Modernise banking operations |
Management has indicated that credit growth could reach around 15%, with the possibility of exceeding this level by a few percentage points.
Track Live : Nifty Levels Today | Sensex Levels Today
SBI Q2 Results Provide Support to the Investment Case
SBI’s latest quarterly performance has added to the positive brokerage commentary. The lender reported a 14.3% year-on-year increase in net profit to ₹23,038 crore in the second quarter.
The profit figure included an exceptional gain of ₹7,289 crore, an important factor investors should consider when assessing the sustainability of reported earnings growth.
Net interest income (NII) increased 14.7% to ₹49,143 crore, exceeding the CNBC-TV18 poll estimate of ₹47,901 crore. Strong NII growth indicates that the bank continues to benefit from its lending operations.
The bank reported a 14.3% year-on-year increase in consolidated net profit to ₹23,038 crore.
| Financial Metric | Q2 FY27 | YoY Growth |
|---|---|---|
| Net profit | ₹23,038 crore | +14.3% |
| Net interest income | ₹49,143 crore | +14.7% |
| Exceptional gain | ₹7,289 crore | — |
Net interest income exceeded the CNBC-TV18 poll estimate of ₹47,901 crore, indicating healthy growth in the bank’s core interest-earning business.
However, investors should note that the reported net profit also included an exceptional gain of ₹7,289 crore. Therefore, underlying profitability should be assessed separately from headline earnings growth.
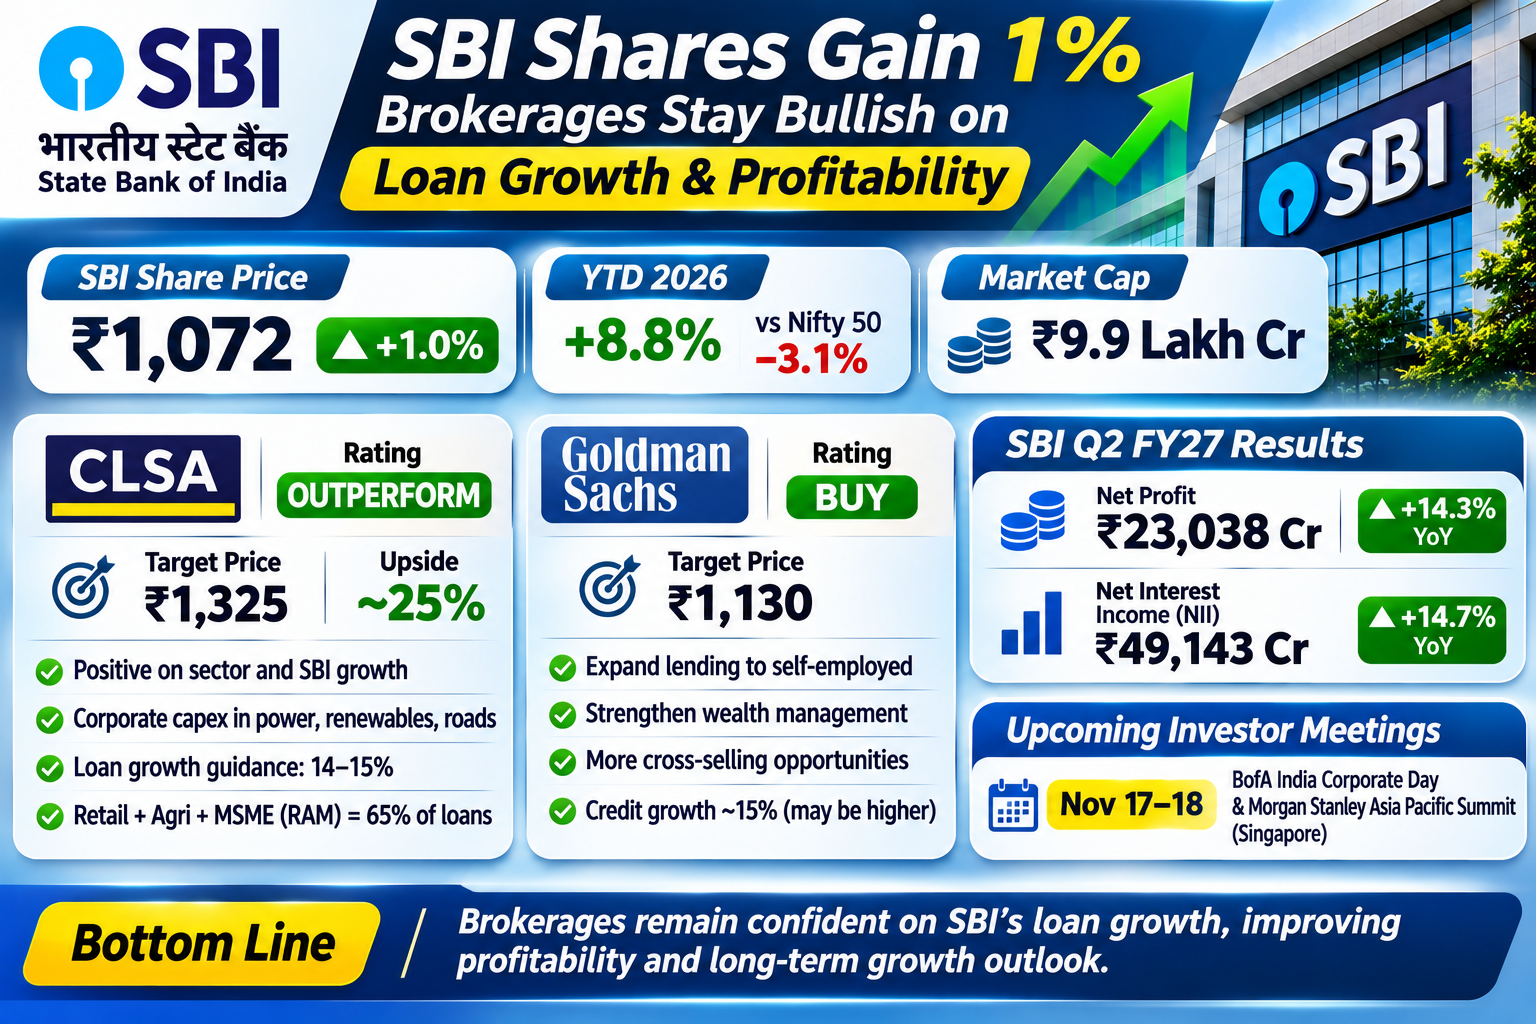
CLSA Sees 25% Upside in SBI, Highlights Corporate Lending Opportunities
CLSA has maintained an Outperform rating on SBI with a target price of ₹1,325 per share, indicating an estimated upside of approximately 25% from the reference price cited in the brokerage commentary.
Following its interaction with SBI management during a US investor roadshow, CLSA highlighted opportunities emerging from India’s corporate capital expenditure cycle.
Key areas of potential loan growth include:
-
Thermal power projects.
-
Renewable energy investments.
-
Road and infrastructure development.
-
Corporate lending to large businesses.
-
Retail, agriculture and MSME financing.
SBI has retained its FY27 loan growth guidance of 14%–15%, with retail, agriculture and MSME (RAM) loans accounting for approximately 65% of its domestic loan portfolio.
Read More : Why India’s Festive Shopping Boom Fell Short as Smartphone Sales Dropped
SBI’s Loan Growth and Profitability Outlook: What Investors Should Watch
SBI’s management has retained its FY27 credit growth guidance of 14%–15%, supported by demand across retail, agriculture, MSME and corporate lending.
The bank is also targeting core RoA of around 1% over the business cycle.
| Key Indicator | Management Outlook |
|---|---|
| Credit growth | 14%–15% |
| RAM loans | Around 65% of domestic loans |
| Core RoA target | Approximately 1% |
| Corporate lending | Growth from infrastructure capex |
| Fee income | Focus on improving non-interest income |
| Digital banking | Greater use of AI and technology |
SBI to Meet Institutional Investors in Singapore
SBI is scheduled to participate in institutional investor meetings in Singapore on November 17 and 18, 2026.
The meetings include:
-
BofA India Corporate Day.
-
Morgan Stanley Asia Pacific Summit.
These interactions could provide investors with further insights into SBI’s lending strategy, profitability targets, deposit growth and future business opportunities.
The meetings are also important because international investors are closely monitoring the bank’s ability to sustain growth while improving returns on assets.
Here’s What Happened Today and Why Traders Reacted
The immediate trigger for the stock’s gains was the continued confidence expressed by CLSA and Goldman Sachs in SBI’s business outlook.
CLSA retained its ‘Outperform’ rating and set a target price of ₹1,325 per share. This implies potential upside of approximately 25% from Wednesday’s closing price. The brokerage highlighted opportunities in corporate lending as investment activity begins to pick up across sectors such as thermal power, renewable energy and roads.
However, capital expenditure among mid-sized companies remains relatively modest, suggesting that corporate loan demand may not strengthen uniformly across the economy.
SBI has retained its loan growth guidance of 14–15%. Retail, agriculture and MSME (RAM) loans account for approximately 65% of its domestic loan portfolio, providing the bank with multiple sources of credit expansion.
Management also reiterated its ambition to achieve a core return on assets (RoA) of 1% over the business cycle. Higher fee income and more effective liability management are expected to support this profitability objective.
What SBI Investors Should Watch Next
SBI is scheduled to meet institutional investors in Singapore on November 17 and 18, participating in the BofA India Corporate Day and Morgan Stanley’s Asia Pacific Summit.
These meetings could provide further insight into management’s expectations for loan demand, margins, corporate lending and digital banking investments.
For investors, the key question is whether SBI can sustain credit growth near its 14–15% guidance while improving core profitability. CLSA’s ₹1,325 target and Goldman Sachs’ ₹1,130 target reflect positive brokerage expectations, but they are not guaranteed returns. Future performance will depend on loan demand, asset quality, margins and the bank’s ability to convert growth into recurring earnings.