HAL Q2 FY27 Results on November 12: Why Investors Are Watching Closely
Hindustan Aeronautics Limited (HAL) is preparing to announce its September quarter results, with investors closely tracking whether stronger aircraft deliveries and execution of defence orders will translate into higher revenue and profitability.
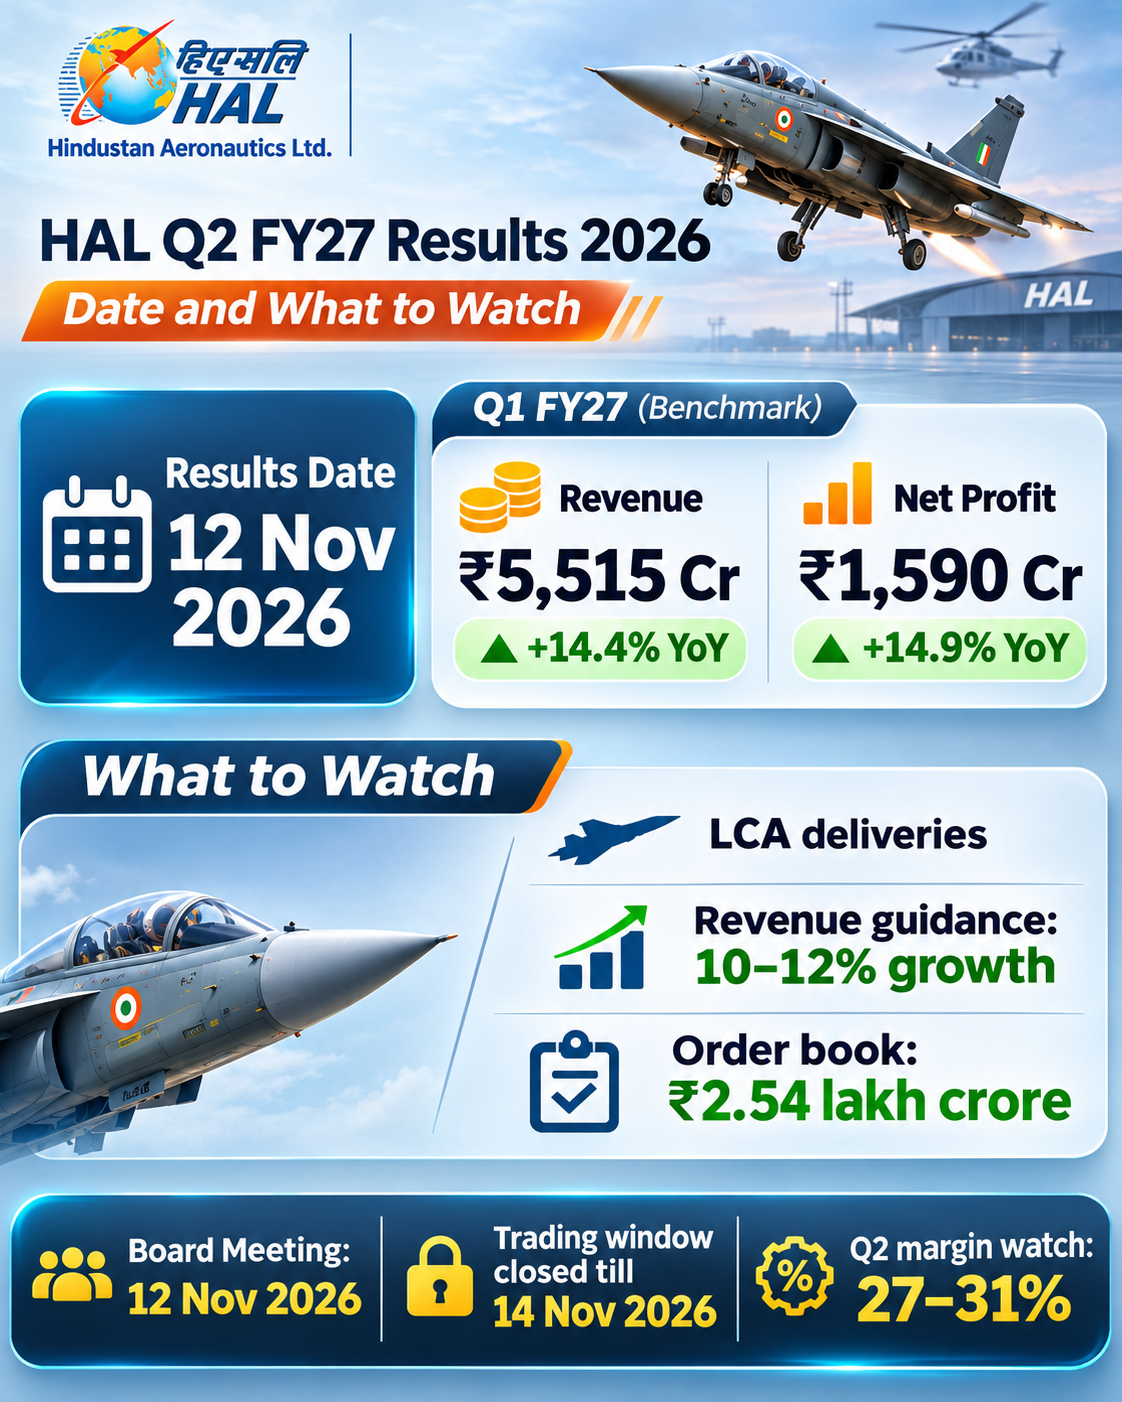
The defence public sector undertaking (PSU) has scheduled its board meeting for Thursday, November 12, 2026, to consider and approve its unaudited Q2 and H1 FY27 financial results.
The upcoming earnings announcement is particularly important because HAL enters the quarter with an order book exceeding ₹2.54 lakh crore. Investors will be looking for signs that the company can accelerate execution, improve deliveries and maintain its operating margins.
Track Live : Results Calendar — NSE & BSE
HAL Q2 Results Date, Trading Window and Important Details
HAL Q2 FY27 earnings announcement.
The company has not specified an exact announcement time. Investors should monitor the NSE and BSE filings for the official results.
The trading window restriction applies to insiders and designated persons until 48 hours after the financial results are declared.
The company communicated the meeting through its exchange filing dated October 27, 2026.
| Metric / Event | Details |
|---|---|
| Company | Hindustan Aeronautics Limited |
| NSE Symbol | HAL |
| Q2 FY27 Results Date | November 12, 2026 |
| Day | Thursday |
| Board Meeting | November 12, 2026 |
| Reporting Period | Q2 and H1 FY27 |
| Trading Window Closure | Until November 14, 2026 |
| Q1 FY27 Revenue | ₹5,515.17 crore |
| Q1 FY27 Net Profit | ₹1,589.66 crore |
| Q1 Revenue Growth | 14.4% YoY |
| Q1 Net Profit Growth | 14.9% YoY |
What time will HAL announce its results?
HAL has not confirmed a specific announcement time. The results are expected following the board’s deliberations, and investors should monitor the company’s NSE and BSE filings for the official announcement.
The previous Q1 FY27 results were filed on August 12 at approximately 2:07 PM IST, but this does not establish the timing for the upcoming announcement.
Track Live : NSE Option Chain — Live | BSE Option Chain — Live Sensex & Bankex Options Data Today
HAL Q2 FY27 Earnings Estimates: Revenue and Profit in Focus
Brokerage estimates suggest that HAL could report healthy year-on-year growth in Q2 FY27.
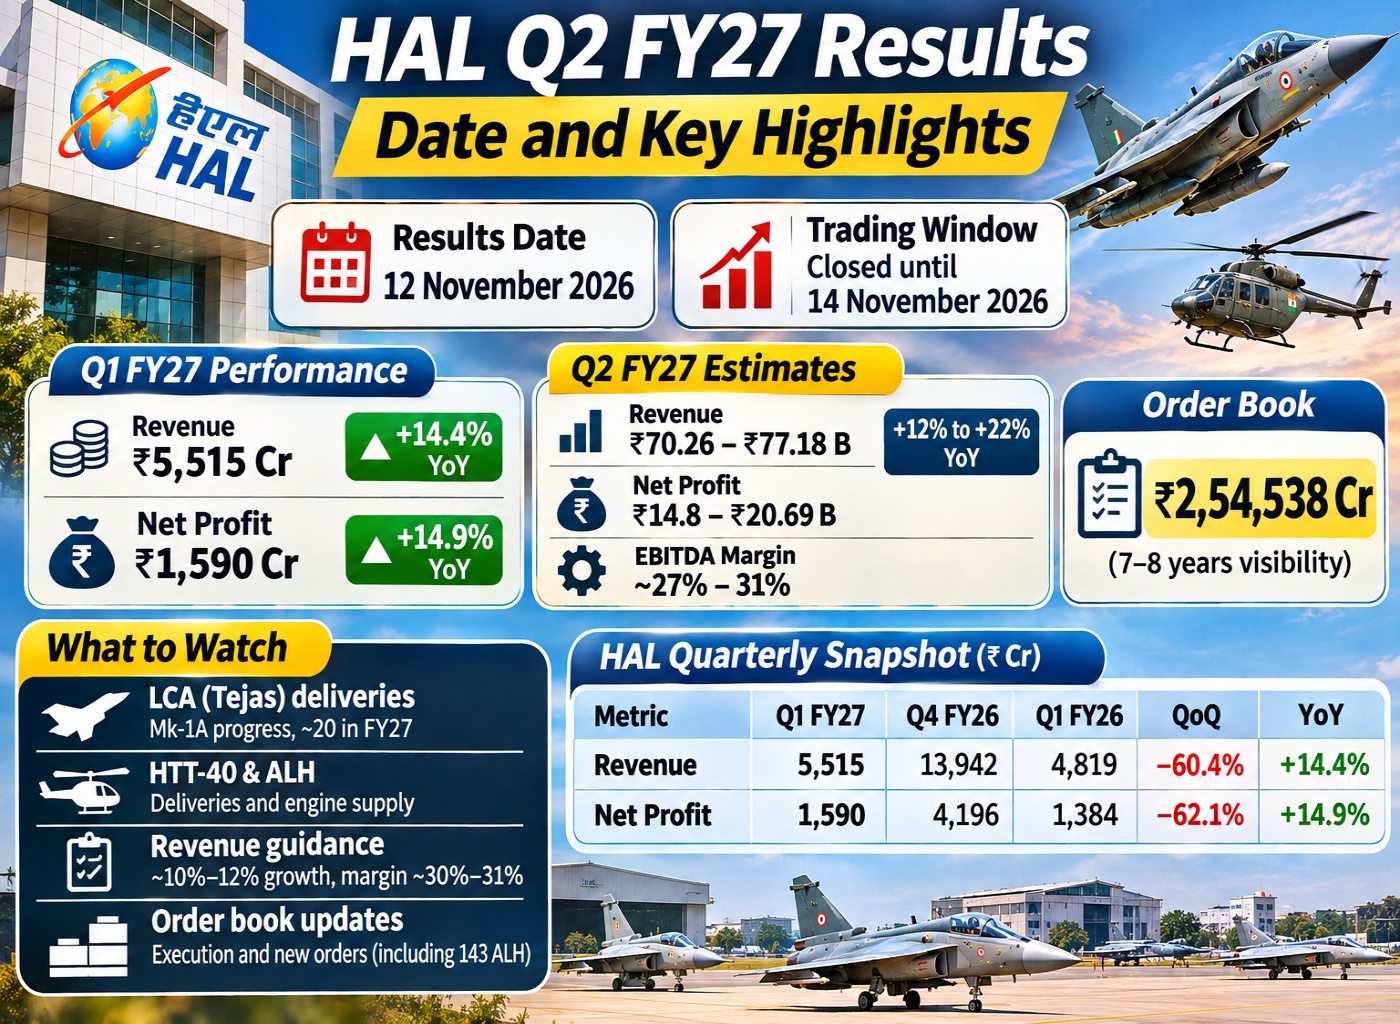
Revenue expectations range between ₹7,026 crore and ₹7,718 crore, with the average estimate at approximately ₹7,436 crore.
Analysts expect net profit to remain between ₹1,480 crore and ₹2,069 crore. EBITDA margins are expected to range between 27% and 31%, broadly in line with management’s full-year guidance of 30% to 31%.
The key question is whether improved execution and aircraft deliveries can support revenue growth without putting pressure on profitability.
HAL Q2 FY27 Results: What Are Brokerages Expecting?
Market expectations indicate that HAL could report strong year-on-year growth in its September quarter earnings, supported by aircraft deliveries, manufacturing revenue and defence programme execution.
According to JM Financial’s Q2 FY27 preview:
| Financial Metric | Q2 FY27 Estimate | Expected Growth |
|---|---|---|
| Revenue | ₹8,106.1 crore | +22.3% YoY |
| Net Profit | ₹2,024.7 crore | +21.8% YoY |
| EBITDA Margin | 26.5% | Lower sequentially |
Another brokerage assessment from Kotak Institutional Equities projects approximately 14% revenue growth and an EBITDA margin of around 26.1%.
The difference between estimates reflects varying assumptions about aircraft deliveries, manufacturing revenue and profitability.
What could drive revenue growth?
-
Deliveries of LCA Tejas FOC Mk1 aircraft.
-
HTT-40 trainer aircraft deliveries.
-
Dhruv NG helicopter deliveries.
-
Higher manufacturing revenue.
-
Continued repair and overhaul (ROH) activities.
HAL Q1 FY27 Results: Financial Performance at a Glance
HAL reported double-digit year-on-year growth in revenue and net profit during the June quarter.
However, both revenue and profitability declined sharply compared with the March quarter, reflecting the company’s historical concentration of deliveries towards the end of the financial year.
| Financial Metric | Q1 FY27 | Q4 FY26 | Q1 FY26 |
|---|---|---|---|
| Revenue (₹ crore) | 5,515.17 | 13,942.40 | 4,819.01 |
| Total Income (₹ crore) | 6,415.41 | 15,092.97 | 5,566.10 |
| Profit Before Tax (₹ crore) | 2,122.72 | 5,570.61 | 1,844.03 |
| Net Profit (₹ crore) | 1,589.66 | 4,196.04 | 1,383.77 |
| Basic EPS (₹) | 23.77 | 62.74 | 20.69 |
The key year-on-year developments were:
-
Revenue increased 14.4%.
-
Net profit advanced 14.9%.
-
Quarterly EPS increased from ₹20.69 to ₹23.77.
These figures provide the baseline against which investors will assess the September quarter performance.
Track Live : Nifty Levels Today | Sensex Levels Today
HAL Management Guidance and ₹2.54 Lakh Crore Order Book Under Spotlight
Revenue guidance and operating margins will be another major area of focus.
During the previous earnings call, Director (Finance) and CFO Barenya Senapati indicated that HAL was targeting revenue growth of at least 10% to 12% during FY27.
He also said the company expected EBITDA margins to remain around 30% to 31%.
HAL reported an order book of ₹2,54,538 crore at the end of FY26, following fresh orders worth ₹97,028 crore, including the 97 LCA Mark-1A aircraft contract for the Indian Air Force.
Investors will also watch developments concerning 143 Advanced Light Helicopters, HTT-40 trainer aircraft and the supply of Honeywell engines.
Management had targeted delivery of more than 20 HTT-40 trainers during FY27.
Read More : Nifty 50 at 8-Month High, Sensex Climbs 1.4% as Crude Slides After Diwali Break
HAL Q1 FY27 Results Provide a Base for Comparison
HAL reported revenue from operations of ₹5,515.17 crore in Q1 FY27, increasing 14.4% year-on-year from ₹4,819.01 crore.
Net profit advanced 14.9% to ₹1,589.66 crore compared with ₹1,383.77 crore in the corresponding quarter last year.
However, revenue declined 60.4% sequentially, while net profit dropped 62.1% compared with Q4 FY26. This highlights the importance of understanding HAL’s quarterly delivery schedules and the impact of seasonality on reported earnings.
What to Watch in HAL’s Q2 FY27 Results
1. Tejas Mk1A deliveries and GE engine supplies
The most important operational development will be the progress of the Light Combat Aircraft (LCA) Tejas Mk1A programme.
HAL has faced delays in delivering the aircraft because of constraints involving GE Aerospace’s F404-IN20 engine supplies, alongside radar and missile integration requirements.
In September 2026, reports indicated that HAL had received 10 engines from GE, while approximately 30 aircraft airframes had been assembled.
HAL Chairman and Managing Director K Ravi subsequently indicated that the company hoped to deliver at least 10 Tejas Mk1A aircraft by the end of 2026.
2. Revenue growth and FY27 management guidance
HAL’s management has indicated an FY27 revenue growth target of approximately 10%–12%.
The company has also guided towards operating EBITDA margins of around 30%–31%.
Investors will examine whether the company can maintain this guidance despite execution challenges and changes in its manufacturing revenue mix.
The September quarter’s revenue performance will provide an important indication of whether HAL is progressing towards its annual targets.
3. Order book crosses ₹2.54 lakh crore
HAL ended FY26 with an order book of approximately ₹2,54,538 crore, providing significant long-term business visibility.
The order book includes major defence programmes, particularly the 97 additional LCA Tejas Mk1A aircraft ordered for the Indian Air Force.
Management has also indicated the potential for approximately ₹90,000 crore of additional orders over the next two years, including helicopter and repair-and-overhaul programmes.
4. HTT-40 and helicopter programme execution
The Hindustan Turbo Trainer-40 (HTT-40) programme is another important growth opportunity.
HAL has indicated plans to deliver more than 20 HTT-40 trainers during FY27, supported by improved availability of Honeywell engines.
Investors will also track Dhruv NG helicopter deliveries and other aircraft-engine programmes.
The successful execution of these projects could diversify HAL’s manufacturing revenue beyond the Tejas fighter programme.
5. EBITDA margins and profitability
Despite expectations of strong revenue growth, profitability margins could remain under pressure.
JM Financial expects HAL’s EBITDA margin to decline to approximately 26.5% during Q2 FY27, compared with 27.7% in Q1 FY27.
Kotak Institutional Equities has projected a margin of around 26.1%.
The main factor to monitor will be the contribution of manufacturing revenue compared with higher-margin repair-and-overhaul activities.
What HAL Q2 Results Could Mean for Investors and Traders
HAL’s November 12 earnings announcement could influence sentiment across defence stocks.
Better-than-expected revenue, stable EBITDA margins and progress on Tejas deliveries could strengthen investor confidence. Positive commentary on GE engine supplies and order execution may also support the long-term investment outlook.
However, weaker margins, delivery delays or cautious management guidance could trigger profit booking in HAL shares.
Investors should avoid focusing only on headline net profit. Revenue growth, operating margins, cash flows and execution timelines will be equally important.