Inox Clean Energy is preparing for another attempt to tap India’s public markets, but the business heading towards a potential IPO is significantly larger than the platform presented in its first draft filing in 2025.
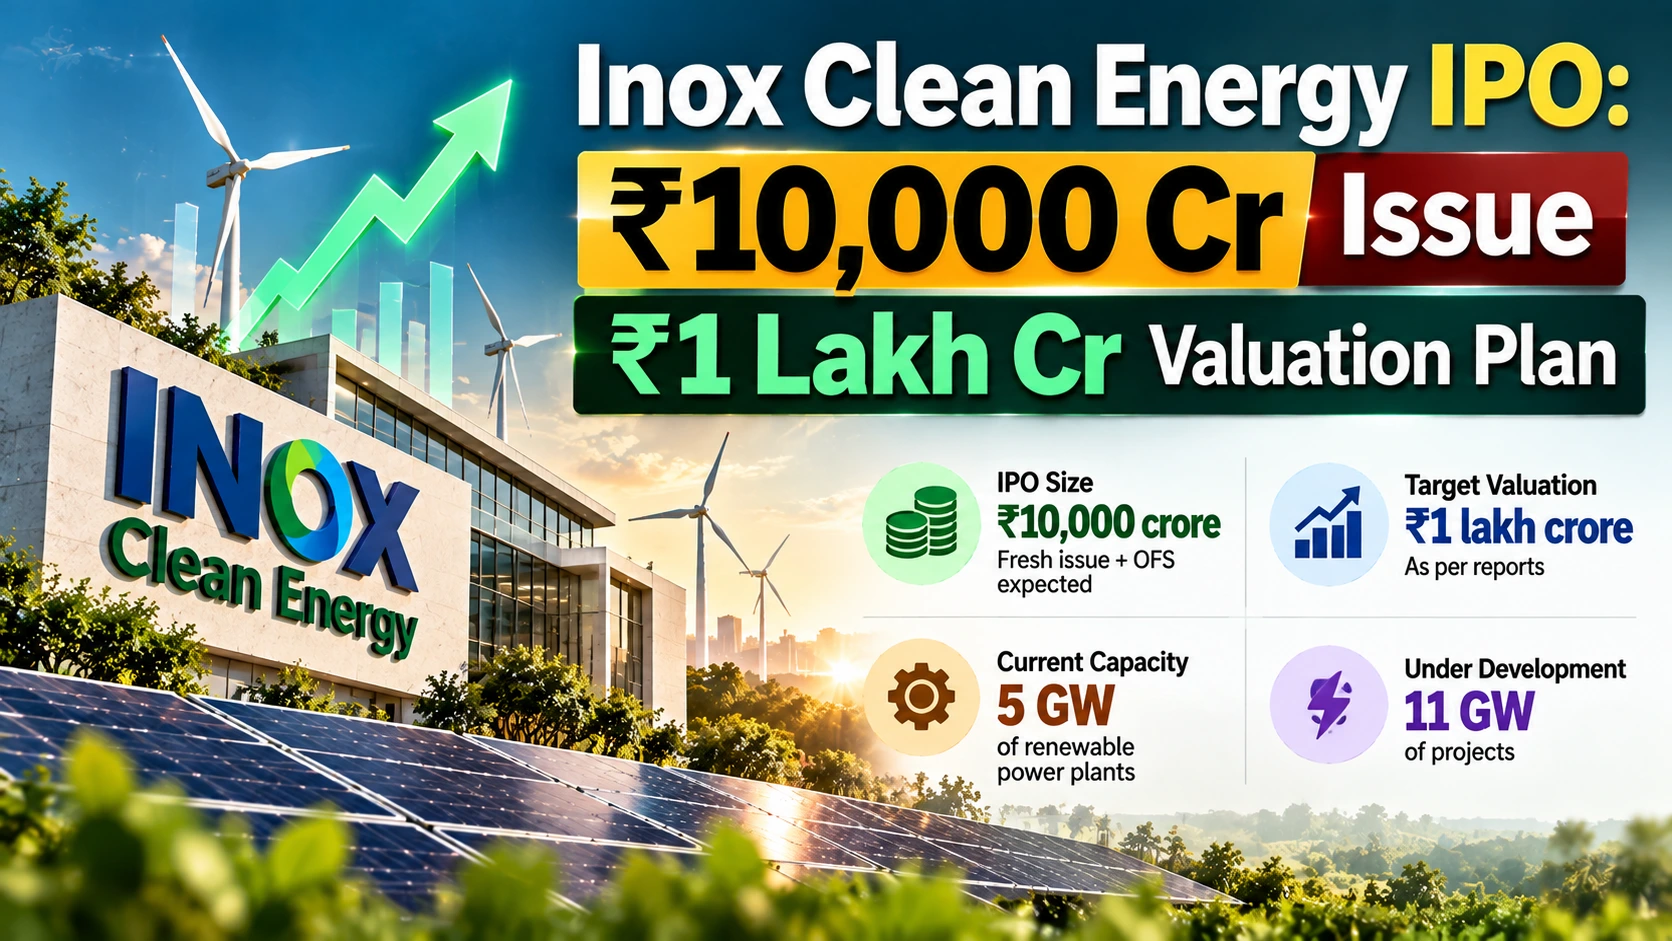
According to people familiar with the matter cited by The Economic Times on September 25, 2026, Inox Clean Energy is likely to file a draft red herring prospectus (DRHP) for around ₹10,000 crore with SEBI. The proposed offering is expected to comprise both a fresh issue of shares and an offer for sale (OFS) by existing shareholders.
The potential issue would make Inox Clean one of the largest private-sector renewable-energy IPO candidates in India. Government-backed NTPC Green Energy also raised ₹10,000 crore in its November 2024 IPO, giving the proposed Inox issue a useful benchmark.
The bigger change, however, is the scale of the underlying business. The latest ET report says Inox Neo Energies, Inox Clean’s renewable power generation arm, now operates renewable power plants with a total capacity of 5 GW, while another 11 GW of projects are under development.
Track Live: Inox Green Energy Services Limited – IPO Dates
₹10,000 Crore IPO: Bigger Than Its First Attempt
Inox Clean first confidentially filed IPO papers in July 2025 for a proposed issue of around ₹6,000 crore, with reports then pointing to a valuation of roughly ₹50,000 crore. The draft papers were withdrawn on December 5, 2025, after the company raised substantial pre-IPO capital and expanded its renewable and solar-manufacturing businesses through acquisitions.
The latest reported ₹10,000 crore issue would therefore be around 67% larger than the earlier ₹6,000 crore plan. More importantly, the business being taken to market is now materially different from the one described in the original filing.
| IPO indicator | 2025 plan | Latest reported plan |
|---|---|---|
| Proposed IPO size | ~₹6,000 crore | ~₹10,000 crore |
| Filing status | Withdrawn on Dec 5, 2025 | Fresh DRHP expected |
| Issue structure | Earlier proposal | Fresh issue + OFS expected |
| Reported valuation | ~₹50,000 crore | ~₹1 lakh crore |
| Promoter ownership | >90% reported | ~95% reported |
| Potential dilution | >10% reported earlier | ~10% reported |
The latest issue size, valuation, dilution, price band and allocation between fresh shares and OFS are not final and will depend on the new DRHP and subsequent regulatory process.
The ₹1 Lakh Crore Valuation Question
The valuation is emerging as one of the most closely watched parts of the potential IPO.
Moneycontrol reported that Inox Clean is seeking a valuation of around ₹1 lakh crore, with a dilution of roughly 10%. However, because the proposed IPO is expected to include both a fresh issue and an offer for sale, the final valuation and dilution cannot be inferred directly from the ₹10,000 crore headline issue size.
There is nevertheless a striking valuation progression.
In January 2026, Inox Clean and Inox Solar tied up around ₹3,100 crore of equity funding at a pre-money valuation of roughly ₹50,000 crore.
In July, Rising Sun Holdings, the family office investment vehicle associated with Adar Poonawalla, invested ₹700 crore at a reported valuation of ₹70,000 crore.
A ₹1 lakh crore IPO valuation would therefore represent a substantial increase from those earlier private-market markers. But the transactions occurred at different stages of Inox Clean’s expansion and may involve different capital structures and securities. The comparison is consequently useful as a trend, not as a like-for-like valuation chart.
From Vena Acquisition to a 5 GW Renewable Platform
The Vena Energy India acquisition has been one of the biggest drivers of Inox Clean’s expansion.
In August 2026, Inox completed the acquisition of Vena Energy India’s renewable platform. The acquired business included about 1 GW of operating renewable capacity, 1.7 GW of advanced-stage solar and wind projects, 1.2 GWh of advanced-stage BESS projects, and an additional 2.7 GW of solar and wind development pipeline plus 1.3 GWh of BESS.
At the time of the transaction, Inox said the acquisition was expected to take its operating and near-operational portfolio to about 4 GW and its development pipeline beyond 12 GW.
The latest position is larger: ET now reports 5 GW of operating renewable generation capacity and another 11 GW under development.
That shift is important because it shows how quickly the company’s asset base has evolved between the original IPO filing and the latest proposed issue.
Solar Manufacturing Adds a Second Growth Engine
Inox Clean is not solely a renewable power-generation platform. Its Inox Solar subsidiary is also rapidly expanding across solar manufacturing.
The company says Inox Solar has scaled to 6 GW of solar module manufacturing capacity, split between 3 GW in India and 3 GW in the United States. It also plans additional manufacturing capacity, including solar cells.
Its US expansion came through the acquisition of Boviet Solar’s US assets for an enterprise value of approximately $750 million. The deal provided 3 GW of operational TOPCon module manufacturing capacity and a binding agreement for another 3 GW of TOPCon cell capacity expected to be commissioned by December 2026.
For the longer term, Inox Clean is targeting 10 GW of installed renewable IPP capacity and 11 GW of integrated solar manufacturing capacity by FY28.
Acquisition Spree Continues Ahead of IPO
The Vena transaction was not an isolated deal.
Inox Clean has acquired or announced transactions involving platforms such as Macquarie-owned Vibrant Energy, SunSource Energy, SkyPower and Wind World India’s IPP assets. Moneycontrol has described the company as having announced or completed 10 strategic acquisitions over the past year.
The acquisition strategy has helped the company move rapidly up the renewable-energy value chain, but it also creates an important execution question for public-market investors: how efficiently can the enlarged portfolio be integrated and financed?
The company has continued to examine further acquisitions. In September, it was reported to be nearing a ₹2,500 crore enterprise-value acquisition of Athena Renewables, while Inox was also identified as a leading contender for Brookfield’s 550 MW Bikaner renewable-energy portfolio. Neither transaction should be treated as completed unless formally announced.
Funding Before the IPO
Inox Clean has also built a sizeable private funding base ahead of the proposed public issue.
The January equity round raised around ₹3,100 crore from investors including CalPERS, SUN Group Global, Authum Investments and Akash Bhansali.
Rising Sun Holdings subsequently invested ₹700 crore at a reported ₹70,000 crore valuation.
In August, Motilal Oswal Group committed ₹1,500 crore through compulsorily convertible debentures, with ₹1,000 crore initially invested, according to the reported transaction details. The capital is intended to support Inox Clean’s growth and inorganic expansion.
This funding history matters because the eventual DRHP will show how much of the capital requirement has already been funded privately and how much the company now wants to raise from public shareholders.
Why the IPO Could Matter to India’s Primary Market
A ₹10,000 crore issue would arrive at a time when India’s IPO market remains highly active despite tension in the secondary market.
Mainboard IPOs raised about ₹73,674 crore between January and August 2026, according to PRIME Database data cited by Outlook Business. At the reported ₹10,000 crore size, the Inox issue would be equivalent to roughly 13.6% of that January-August fundraising total.
That makes the proposed transaction large enough to become a meaningful test of appetite for another capital-intensive renewable-energy platform, particularly as investors weigh growth expectations against valuation and execution risk.
Also Check: Latest IPO GMP Today (Live IPO Grey Market Premium)
What Investors Need to Watch
The next major trigger is the new DRHP.
That document should establish the actual fresh-issue and OFS composition, the financial statements reflecting the acquisition spree, the company’s debt position, details of its use of proceeds and the valuation framework.
Investors will also need to separate historical performance from management targets. Inox Clean has projected EBITDA of approximately ₹5,000 crore in FY27 and ₹12,000 crore in FY28, but these are forward projections rather than reported historical earnings.
The expectation gap is therefore important: the company has expanded dramatically in a short period, but public-market investors will ultimately price the earnings, cash generation, leverage and execution required to support that larger platform.
Bottom Line
Inox Clean Energy’s proposed ₹10,000 crore IPO represents a much bigger public-market proposition than its withdrawn ₹6,000 crore plan of 2025.
The renewable platform now has 5 GW of operating capacity and 11 GW under development, while solar manufacturing has expanded to 6 GW of module capacity across India and the US.
The reported ₹1 lakh crore valuation would put the company on a substantially higher valuation marker than the ₹50,000 crore pre-money valuation reported in January and the ₹70,000 crore valuation reported in July.
But the biggest uncertainty remains the same: the ₹10,000 crore issue, valuation, dilution, fresh-issue/OFS split and IPO timetable are still reported plans until the new DRHP is filed.
For the market, the more important question may ultimately be whether Inox Clean’s rapid acquisition-led expansion can translate into the earnings and cash flows needed to justify the valuation investors will face at the IPO stage.
Read Next: PB Fintech Crashes 36%, NSE Debuts at ₹1,800: Stocks to Watch Sep 25