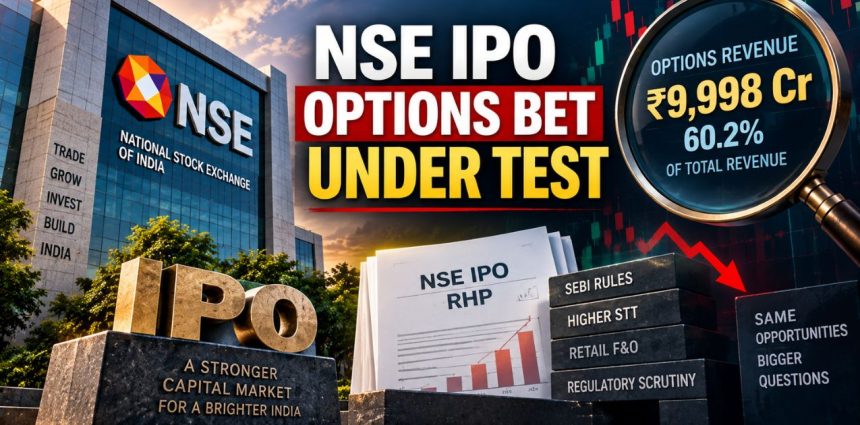
Synopsis: NSE’s red herring prospectus shows transaction charges made up 78.65% of FY26 operating revenue, with equity options alone contributing about 60.2% and equity futures another 8.3%, together about 68.5%.
That concentration sits at the centre of the exchange’s IPO story as SEBI’s phased-in derivatives framework, a higher STT and a shrinking retail F&O base raise questions about how durable that revenue base will be.
The National Stock Exchange’s initial public offering opens for subscription on Thursday, September 17, 2026, and closes on September 21, at a price band of Rs 1,700–Rs 1,785 per share.
The issue is entirely an offer for sale of Rs 22,561.57 crore. Anchor bidding takes place on September 16, allotment is expected on September 22, and listing is tentatively set for September 24 on both the BSE and NSE.
Buried in the filing is a number that matters more than listing-day arithmetic: F&O trading together accounted for about 68.5% of NSE’s FY26 revenue from operations, with options alone responsible for roughly 60.2%.
That concentration is becoming an important lens through which investors are assessing the country’s largest exchange going public, just as its most profitable business line is also among its most closely regulated.
Also Read: NSE IPO Shrinks Before Launch: ₹22,561 Crore Offer, Key Changes
NSE IPO: Issue Details at a Glance
| Detail | Figure |
|---|---|
| Subscription opens | September 17, 2026 |
| Subscription closes | September 21, 2026 |
| Anchor investor bidding | September 16, 2026 |
| Price band | Rs 1,700 – Rs 1,785 per share |
| Lot size | 8 shares (Rs 13,600–Rs 14,280 per lot) |
| Issue size | Rs 22,561.57 crore |
| Issue structure | 100% Offer for Sale (OFS); no fresh capital to NSE |
| Shares on offer | 12.64 crore equity shares (cut from an earlier 14.9 crore) |
| Implied market cap (upper band) | ~Rs 4.42 lakh crore |
| Allotment | September 22, 2026 |
| Listing | September 24, 2026 (BSE) |
Grey market premium is deliberately left out of this table; it’s unofficial, dealer-quoted, and can move daily.
Worth flagging separately: the deal has visibly shrunk from earlier market chatter. Reports through August pegged NSE’s valuation at up to Rs 5.26 lakh crore (~$55 billion) on an issue size approaching Rs 30,000 crore.
The RHP settles meaningfully lower, a roughly 15% cut in shares offered and an implied market cap near Rs 4.42 lakh crore, after several selling shareholders, including SBI and Bank of Baroda, trimmed their OFS quantities.
Check Live: NSE IPO | NIFTYTRADER
Revenue Anatomy: How NSE Actually Makes Money
NSE’s revenue from operations stood at Rs 16,601.31 crore in FY26, down 3% from Rs 17,140.68 crore in FY25, though still above FY24’s Rs 14,780.01 crore.
Transaction charges, the fee NSE levies on every trade executed on its platform, remain overwhelmingly the largest contributor, and within that bucket, options trading alone does most of the heavy lifting.
Where FY26 Revenue From Operations Came From
| Revenue stream | FY26 amount | Share of revenue from operations |
|---|---|---|
| Transaction charges — total | ₹13,057 crore | 78.65% |
| — Equity options | ₹9,996 crore | ~60.2% |
| — Equity futures | ₹1,370 crore | ~8.3% |
| — Cash market | ₹1,555 crore | ~9.4% |
| — Other transaction segments | ₹137 crore | ~0.8% |
| Data connectivity & data feeds | ₹1,129 crore | ~6.8% |
| Listing services | ₹352 crore | ~2.1% |
| Index licensing | ₹152 crore | ~0.9% |
| Other operating revenue | Balance | — |
| Revenue from operations | ₹16,601.31 crore | 100% |
*Calculated as total transaction-charge revenue minus separately disclosed equity-options and equity-futures revenue. It is not a standalone RHP-reported category; treat it as an implied estimate covering cash market, currency/commodity derivatives, the mutual fund platform, the wholesale debt market and interest-rate futures combined.
Two things are easy to conflate and shouldn’t be: revenue from operations (Rs 16,601 crore) is not total income (Rs 18,713.37 crore in FY26, down ~2% from Rs 19,176.83 crore in FY25), which adds treasury and other income on top of the operating business.
Per the DRHP, NSE’s market dominance varies by segment: it holds roughly 93% of India’s cash-equity turnover, 99.79% of equity-futures turnover, and 74.71% of equity-options premium turnover — a reminder that the F&O concentration story is really an options concentration story more than a futures one.
The Regulatory Overhang: Why F&O Concentration Worries Investors
This is the crux of the “risk” side of the RHP, and it isn’t hypothetical, it’s already partly visible in the numbers. Revenue from transaction charges declined 4.24% in FY26, while futures revenue fell a sharper 14.31%.
The RHP attributes this to lower average daily traded value across cash, futures and options, it does not explicitly pin the decline on any single regulatory measure, so treat that as a contributing backdrop rather than a proven cause.
That backdrop has been building since late 2024:
- October 1, 2024: SEBI issued Circular SEBI/HO/MRD/TPD-1/P/CIR/2024/132, introducing a revised equity-index derivatives framework, higher minimum contract values, rationalised weekly expiries, upfront premium collection and added risk monitoring, with individual provisions phased in over the following months.
- November 20, 2024: the higher contract-value rule and one-weekly-expiry-per-exchange rule took effect, raising minimum index contract values from roughly Rs 5–10 lakh to Rs 15–20 lakh (NSE retained weekly expiry only on Nifty; BSE only on Sensex).
- February 1, 2025: upfront collection of options premiums from buyers came into force.
- May 2025: NSE’s RHP cites a further round of equity-index derivatives framework changes from SEBI.
- April 1, 2026: STT on futures rose from 0.02% to 0.05% of contract value; on options, from 0.10% to 0.15% of premium value.
Separately, the July 2025 SEBI enforcement action against proprietary trading firm Jane Street, which barred the firm from Indian markets and impounded roughly $566 million in alleged unlawful gains, triggered a sharp, short-lived dip in index-options turnover.
It’s a useful illustration of how reactive derivatives liquidity can be to a single enforcement action, but it shouldn’t be read as an explanation for NSE’s broader FY26 revenue trend, which reflects a longer stretch of regulatory and volume changes rather than one event.
The cumulative retail impact shows up in government data: unique retail participants in the F&O segment fell around 20% to 78.6 lakh in FY26 from 98.1 lakh in FY25, according to figures Minister of State for Finance Pankaj Chaudhary provided in a written reply to the Rajya Sabha.
NSE isn’t insulated on the trading-member side either. Its top 10 trading members contributed 47%, 45.60%, 46.78%, 44.48% and 45.26% of revenue from operations in Q1FY27, Q1FY26, FY26, FY25 and FY24 respectively. Any migration of a handful of large members to rival venues would disproportionately hit revenue.
Cash Market Pivot: Is Volume Migrating, or Just Shrinking?
A common read on this story is that trading activity is simply relocating from derivatives to cash equities as speculative F&O flow gets squeezed out. Exchange-level data only partly supports that. Combined NSE-BSE average daily cash-market turnover actually fell about 6% year-on-year in FY26 to roughly Rs 1.13 trillion, hardly evidence of a cash-market boom absorbing the derivatives slowdown.
What the data shows more clearly is fewer, larger trades and a rival gaining ground. According to exchange-data analysis reported by Business Standard, NSE’s average trade size rose to about Rs 31,545 from Rs 29,046 a year earlier, while BSE’s climbed to roughly Rs 22,822 from Rs 18,720.
Separately, NSE’s own F&O turnover fell around 18% in FY26, even as market-share data cited by HDFC Securities shows BSE’s notional derivatives market share rising from about 38% in September 2025 to 44% by March 2026, with its options-premium share climbing from 24.4% to 26.1%.
HDFC Securities’ derivatives analyst Nandish Shah has attributed the slowdown to a combination of the SEBI lot-size hike pricing out smaller participants and generally subdued market sentiment over the past year, rather than to a clean migration of volume into cash equities. In short: the pie for smaller traders got smaller, it didn’t simply move next door.
Other Risks Flagged in the RHP
- Regulatory scrutiny: NSE itself faced no SEBI enforcement action from inspections in Q1FY27 or the preceding three fiscal years, but SEBI did initiate enforcement action against two of its subsidiaries in that window.
- Technology and operational risk: the RHP cites the February 24, 2021 outage, when a Storage Area Network failure at NSE Clearing, alongside index and surveillance systems, halted all trading segments for nearly five hours and 24 minutes, even though the core trading system itself wasn’t affected.
- Listing pipeline dependence: the number of IPOs on NSE fell to 219 in FY26 from 242 in FY25. Listing-services revenue still grew, however, up 12.30% to Rs 352 crore in FY26 from Rs 314 crore in FY25, suggesting bigger-ticket listings partly offset the lower count.
- Macro sensitivity: the RHP separately flags slower GDP growth, inflation, interest-rate moves, currency depreciation, a potential sovereign-rating downgrade, and global geopolitical or commodity shocks as factors that could dent investor participation broadly.
Also Check: IPO – Latest & Upcoming IPOs List 2026 | Check Live BSE NSE IPOs
Financial Snapshot: Profitability Holding Up, Margins Compressing
| Metric | FY26 | FY25 | Change |
|---|---|---|---|
| Total income | Rs 18,713.37 crore | Rs 19,176.83 crore | down ~2% |
| Revenue from operations | Rs 16,601.31 crore | Rs 17,140.68 crore | down ~3% |
| Operating EBITDA | Rs 11,097.90 crore | Rs 12,646.88 crore | down ~12% |
| Operating EBITDA margin | 66.85% | ~74% | compressed ~7 pts |
| Profit after tax | Rs 10,302.06 crore | Rs 12,187.69 crore | down ~15.5% |
| Q1 FY27 total income | Rs 5,252.17 crore | Rs 4,798.45 crore (Q1FY26) | up ~9.5% YoY |
| Q1 FY27 PAT | Rs 3,120.08 crore | — | — |
The margin compression is arguably as important as the revenue decline itself: NSE’s operating EBITDA margin fell from about 73.8% to 66.85% year-on-year.
What NSE IPO Investors Should Watch After Listing
- F&O volume: whether derivatives activity stabilises now that SEBI’s framework is fully phased in, or continues to soften.
- Options revenue mix: whether the RHP-flagged decline in weekly index options is offset by other options products or simply continues.
- Non-transaction revenue: whether data connectivity, listing, index licensing and clearing keep growing fast enough to reduce reliance on transaction charges over time.
- Market share: whether NSE retains its near-total dominance in cash and futures as BSE continues gaining ground in parts of the derivatives market.
- Top-member concentration: whether the ~45-47% revenue contribution from NSE’s top 10 trading members holds steady or narrows.
Need to Know
- NSE IPO opens September 17 and closes September 21, price band Rs 1,700–Rs 1,785, entirely an Offer for Sale, NSE receives none of the proceeds.
- Transaction charges made up 78.65% of FY26 operating revenue; options alone contributed 60.2%, futures another 8.3%, and F&O combined is about 68.5%.
- FY26 revenue from transaction charges fell 4.24%, and futures revenue fell 14.31%, against a backdrop of SEBI’s phased derivatives framework and the April 2026 STT hike, though the RHP attributes the decline to lower traded volumes broadly, not to any single rule.
- Retail F&O participation dropped roughly 20% in FY26 (Rajya Sabha data); the top 10 trading members still account for nearly half of NSE’s revenue from operations.
- Cash-market data doesn’t clearly support a “money just moved to cash equities” narrative; cash turnover also softened in FY26, while BSE gained relative derivatives share.
- Operating EBITDA margin compressed from ~74% to 66.85% YoY; PAT fell ~15.5%, though Q1 FY27 total income is already up YoY.
Read Next: RBI Blocks Tata Sons’ Exit. Why Tata Stocks Jumped 20%
Disclaimer: This article is for informational purposes only and does not constitute investment advice or a recommendation to subscribe to the NSE IPO or buy/sell any security. Investors should review the official NSE RHP and assess the IPO’s valuation, regulatory, market and business risks independently.