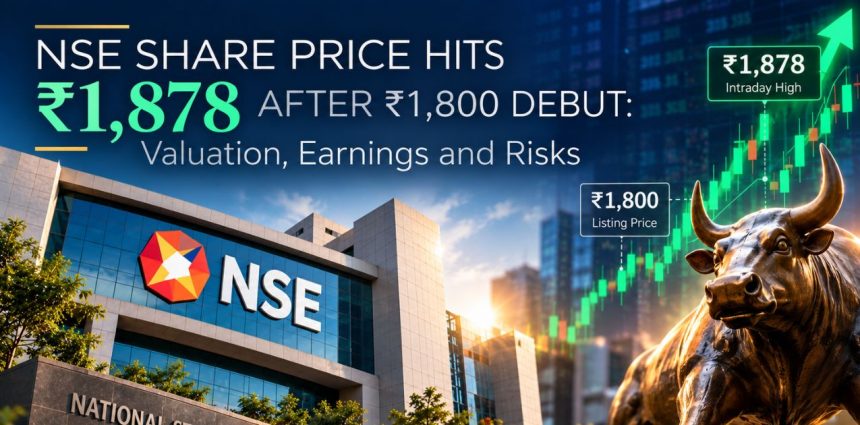
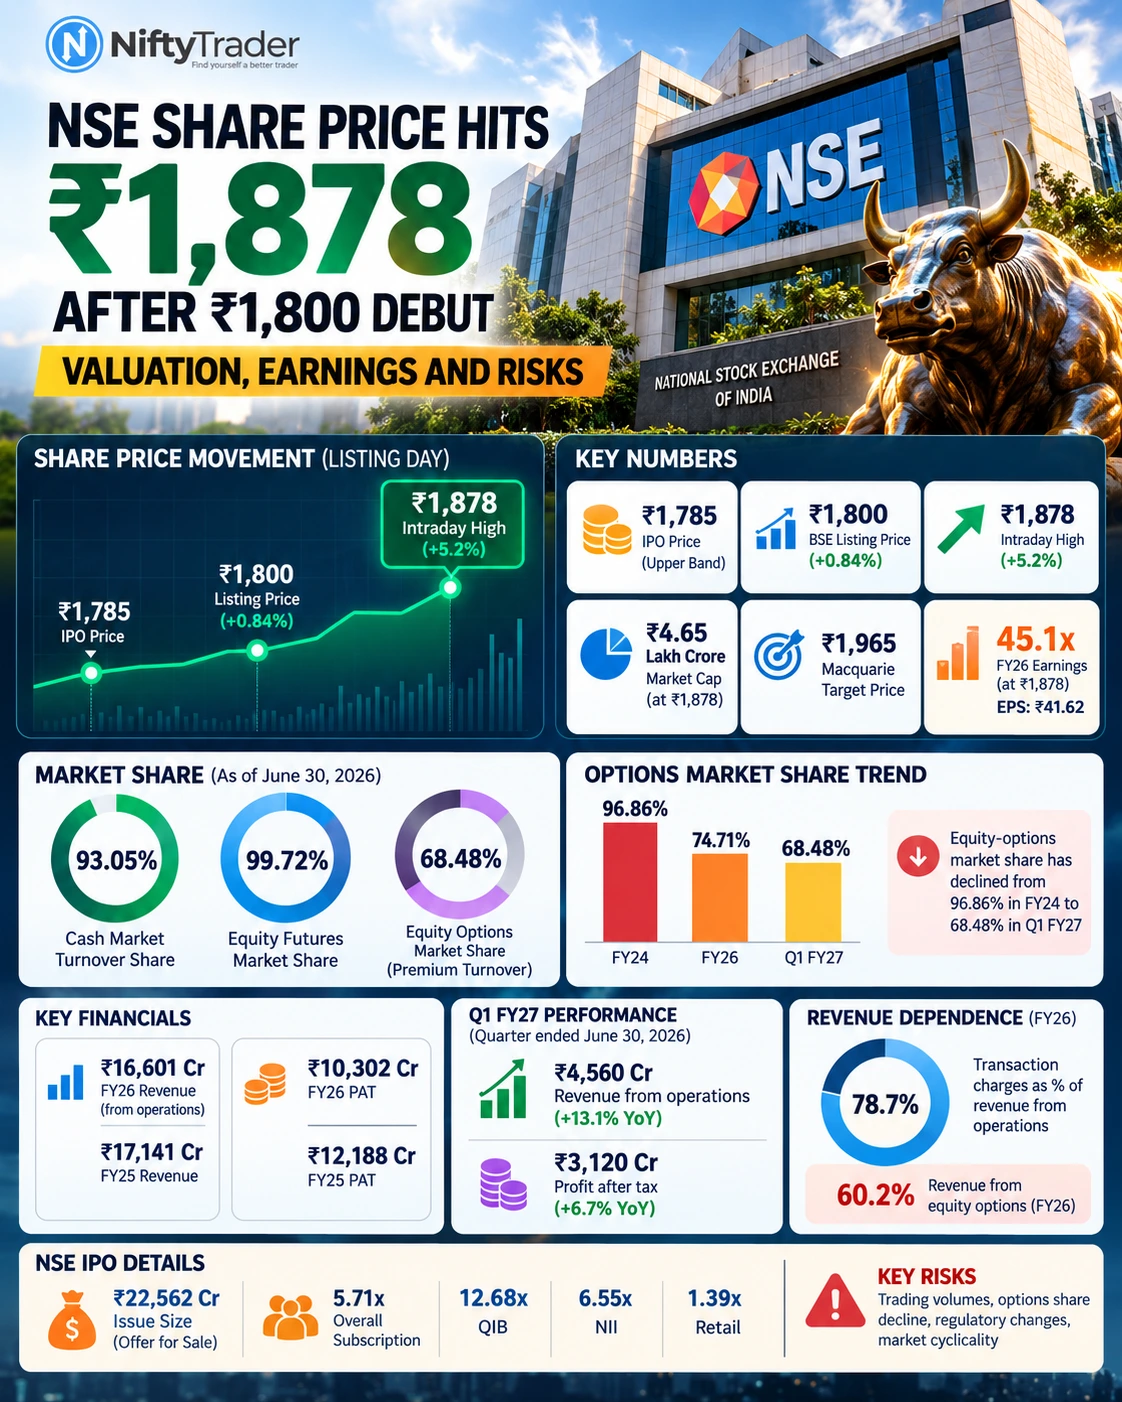
NSE shares listed at ₹1,800 on the BSE, a 0.84% premium to the ₹1,785 IPO price, before climbing to an intraday high of ₹1,878, or 5.2% above the issue price, in early trade. With Macquarie’s ₹1,965 target now much closer, investors are weighing NSE’s dominant market position against its trading-volume dependence, options-market-share decline and regulatory risks.
National Stock Exchange of India (NSE) shares have begun their public-market journey with a relatively modest debut followed by a sharper early rally.
The stock listed on the BSE at ₹1,800 per share, a 0.84% premium to its ₹1,785 IPO price. Moneycontrol subsequently reported an intraday high of ₹1,878, equivalent to a 5.2% gain from the issue price, in its 10:23 AM IST update on September 24.
That move put NSE’s market capitalisation at roughly ₹4.65 lakh crore, using the post-issue share count implied by its IPO valuation.
The bigger story, however, is not the listing gain itself.
At ₹1,878, NSE is already trading at more than 45 times FY26 earnings based on diluted EPS of ₹41.62. Macquarie has placed a ₹1,965 target, meaning the gap between the early market price and that target is far narrower than it was at the IPO price.
The expectation gap is therefore becoming harder to ignore: NSE has one of India’s strongest market franchises, but the stock increasingly needs sustained earnings growth to justify the premium investors are assigning to it.
CHECK LIVE: NSE IPO | NIFTYTRADER
NSE share price: IPO price, listing and early rally
| NSE price marker | Value |
|---|---|
| IPO price band | ₹1,700–₹1,785 |
| Final issue price | ₹1,785 |
| BSE listing price | ₹1,800 |
| Listing premium | 0.84% |
| Reported early intraday high | ₹1,878 |
| Gain from IPO price at ₹1,878 | 5.2% |
| Macquarie target | ₹1,965 |
The listing price itself was far from spectacular.
That is important because NSE’s grey-market premium had cooled sharply ahead of the debut. Business Standard reported that the grey-market premium had fallen to around 2% from a much higher level during the subscription period.
Grey-market pricing is unofficial and should not be treated as equivalent to exchange-traded price discovery. Still, the sequence highlights a change in expectations: the IPO generated substantial demand, but investors did not receive the dramatic opening pop that earlier unofficial indicators had implied.
The post-listing rally then shifted attention toward the stock’s underlying valuation.
NSE is entering the market with extraordinary scale
NSE’s most important asset is its market position.
For the three months ended June 30, 2026, NSE had a 93.05% share of India’s cash-market turnover, 99.72% in equity futures, and 68.48% in equity options based on premium turnover.
Its investor and participant base is also enormous, with 132.37 million unique registered investors, 261.36 million registered investor accounts, 1,328 trading members and 3,005 listed entities as of June 30, 2026.
That scale creates a strong liquidity and network-effect advantage: market participants tend to gravitate toward venues where liquidity is deepest, which can reinforce the existing leadership position.
But there is an important tension inside that dominance.
NSE’s options market share has fallen sharply
NSE remains the dominant derivatives exchange in India, yet its equity-options market share based on premium turnover has declined materially.
| Period | NSE equity-options share |
|---|---|
| FY24 | 96.86% |
| FY25 | — |
| FY26 | 74.71% |
| Q1 FY27 | 68.48% |
The progression from 96.86% in FY24 to 74.71% in FY26 and 68.48% in the June 2026 quarter deserves investor attention.
The decline in share should not automatically be read as a collapse in the options business. What matters is the combination of overall options-market growth, NSE’s absolute volumes, market share and the fees generated from those volumes.
For shareholders, the question is whether a very large market can continue growing fast enough to offset any gradual loss of market share.
That is one of the most important operating indicators to monitor after NSE’s listing.
Trading activity remains central to NSE’s revenue
NSE’s business is highly profitable and asset-light, but it is not insulated from market cycles.
Transaction-related revenue accounts for roughly 78.7% of FY26 revenue from operations, according to figures disclosed around the IPO. Options are also a major contributor to that revenue pool.
This means NSE can benefit enormously when trading participation and derivatives activity expand.
The reverse is also true.
A sustained slowdown in trading volumes, changes in product structures or regulatory measures affecting derivatives can have an immediate impact on transaction revenue.
That dependence gives the stock a distinctive combination of high margins and high market sensitivity.
FY26 profit declined, but Q1 FY27 showed renewed growth
NSE’s FY26 financials provide another important part of the valuation debate.
According to the restated financial information in the IPO documentation, NSE reported:
| Financial metric | FY26 | FY25 |
|---|---|---|
| Revenue from operations | ₹16,601 crore | ₹17,141 crore |
| Profit for the year | ₹10,302 crore | ₹12,188 crore |
| Diluted EPS | ₹41.62 | ₹49.24 |
That means FY26 revenue and profit were both below FY25 levels.
However, the more recent quarterly numbers were stronger.
For the quarter ended June 30, 2026, NSE reported revenue from operations of about ₹4,560 crore and profit after tax of roughly ₹3,120 crore, representing year-on-year increases.
The market is therefore looking beyond the FY26 slowdown.
The key uncertainty is whether the recent earnings improvement can become a sustained trend capable of supporting the valuation now being placed on the stock.
What NSE shares are worth at ₹1,878
Using FY26 diluted EPS of ₹41.62, the implied P/E changes rapidly as the share price moves.
| Share price | Approx. FY26 P/E |
|---|---|
| ₹1,785 IPO price | 42.9x |
| ₹1,800 listing price | 43.3x |
| ₹1,878 early high | 45.1x |
| ₹1,965 Macquarie target | 47.2x |
The calculation shows why the listing-day rally matters.
At ₹1,785, investors were paying roughly 43 times FY26 earnings. At ₹1,878, the multiple rises above 45 times, assuming FY26 EPS remains the reference point.
This does not determine whether NSE is expensive or cheap. It shows the earnings hurdle embedded in the share price.
The faster profits grow, the easier it becomes for the valuation to normalise through earnings. If profit growth disappoints, the market has less room to absorb a premium multiple.
Macquarie sees a longer growth runway
Macquarie has initiated coverage on NSE with an Outperform rating and a ₹1,965 target price.
The brokerage expects approximately 12% revenue CAGR from FY26 to FY30, supported by non-transaction revenues, new products and continued participation in India’s financialisation.
Macquarie has also pointed to NSE’s deep liquidity, technology infrastructure, network effects and market leadership as key strengths. It expects margins to remain resilient in the mid-70% range.
The target price needs to be viewed in the context of the live market price.
At ₹1,800, ₹1,965 represented around 9.2% above the listing price.
At ₹1,878, that difference falls to about 4.6%.
The shrinking gap does not invalidate Macquarie’s research view. It simply means that some of the target’s implied upside has already been absorbed by the listing-day move.
Regulation remains a forward-looking risk
NSE’s earnings cannot be analysed independently of market regulation.
Changes to derivatives rules, contract structures, transaction taxes and market mechanisms can influence both volumes and the economics of trading.
The securities transaction tax on derivatives was increased from April 1, 2026. NSE is also adapting to the Closing Auction Session (CAS) introduced for eligible securities from August 3, 2026.
Macquarie has highlighted CAS as a near-term factor to monitor as market participants adapt to the new framework, with potential pressure on cash equities, derivatives and margin-trading volumes during the adjustment period.
For investors, that is a forward-looking risk rather than a historical issue.
The exchange operates within a regulatory framework that can change the economics of its core products even when management execution remains strong.
The IPO itself did not bring fresh capital into NSE
The NSE IPO was entirely an offer for sale (OFS) of existing shares.
The issue size at the upper price band was about ₹22,562 crore, based on the underlying issue value of approximately ₹22,561.57 crore. Business Standard reported the issue as ₹22,562 crore and noted that it consisted entirely of an OFS.
This means NSE itself does not receive the IPO proceeds as fresh equity capital.
For investors, that makes the post-listing valuation even more closely tied to the underlying business, profitability and growth outlook rather than a new capital deployment programme funded by the IPO.
Institutional demand was strong, but retail participation was more muted
The IPO received an overall subscription of 5.71 times.
QIB demand was particularly strong at 12.68 times, while the NII category was subscribed 6.55 times and the retail portion 1.39 times.
The overall figure therefore masks a substantial difference between institutional and retail demand.
That distinction matters because strong institutional participation provides evidence of demand for the issue, but it does not guarantee the secondary-market performance of the stock after listing.
The subsequent share price still has to be supported by earnings, market activity and valuation.
Limited free float could amplify early volatility
Another feature that makes NSE unusual on listing day is its relatively small initial free float.
Reuters had reported before the debut that only about 5.48% of pre-offer capital was expected to be freely tradable at launch.
A limited available float can magnify price movements when buying or selling interest changes sharply.
Therefore, early NSE price action may reflect not only fundamental reassessment but also the immediate supply-demand balance in the stock.
That makes it risky to treat the first few sessions as a definitive valuation signal.
NSE shares will also trade on MSEI
NSE shares are trading on the BSE from September 24 and have also been admitted by the Metropolitan Stock Exchange of India (MSEI) under its “Permitted to Trade” category from the same date.
MSEI’s circular confirms the admission, while noting that securities under this category do not have the same listing-agreement disclosure framework applicable to fully listed securities.
The additional venue could broaden trading access, but it should not be mistaken for a direct change in NSE’s underlying operating performance.
ALSO READ: NSE Stock Set for Additional Listing on Metropolitan Stock Exchange of India Starting September 24
What NSE investors need to watch after listing
The NSE listing has moved the conversation from IPO demand to public-market valuation.
For existing IPO allottees, the key consideration is the relationship between the current market price and their long-term expectations for NSE’s earnings.
For fresh investors, the starting valuation is now higher than the IPO price.
For short-term traders, the limited free float and listing-day price discovery could create additional volatility.
For long-term investors, the more important indicators are likely to be:
Trading volumes: Transaction revenue remains central to NSE’s business.
Options market share: The decline from 96.86% in FY24 to 68.48% in Q1 FY27 warrants monitoring.
Non-transaction revenue: Growth here could reduce NSE’s dependence on trading activity.
Earnings growth: Profit growth needs to keep pace with the valuation over time.
Regulation: Derivatives rules, taxes and market-structure changes can influence volumes independently of management execution.
NSE listing: the real test starts after the debut
The first session has established two facts.
NSE has attracted substantial investor demand, and its share price has moved above both the IPO price and the ₹1,800 listing level.
But the more important test is now ahead.
At ₹1,878, investors are paying about 45 times FY26 earnings while Macquarie’s ₹1,965 target leaves a relatively modest gap.
At the same time, NSE retains an exceptionally powerful competitive position, generates very high margins and is benefiting from the continued expansion of India’s capital markets.
That creates the central market tension around the stock:
NSE’s franchise is already proven. The open question is how quickly earnings can grow from here—and whether that growth can keep up with the expectations embedded in the post-listing price.
Need to Know
- NSE listed on the BSE at ₹1,800, a 0.84% premium to its ₹1,785 IPO price.
- Moneycontrol reported an intraday high of ₹1,878, up 5.2% from the issue price, in its 10:23 AM IST update.
- At ₹1,878, NSE’s implied FY26 P/E is about 45.1x using EPS of ₹41.62.
- Macquarie has a ₹1,965 target and expects roughly 12% revenue CAGR through FY30.
- NSE held 93.05% cash-market share, 99.72% equity-futures share and 68.48% equity-options share in Q1 FY27.
- The IPO was subscribed 5.71 times, led by QIB demand of 12.68 times.
- The issue was an OFS of about ₹22,562 crore, so NSE itself did not receive fresh IPO capital.
📊 NSE Stock in One Line
Dominant franchise, higher valuation: NSE’s market position is formidable, but the stock now needs sustained earnings growth to support its post-listing multiple.
Read Next: NSE Debut, ₹811 Cr BDL Order, Exide’s 6 GWh Battery Plant: Stocks in Focus Today Sep 24
Disclaimer
This article is for informational and educational purposes only and should not be construed as investment advice or a recommendation to buy, sell or hold NSE shares. Investors should independently evaluate valuation, earnings growth, market conditions, regulatory changes and their own risk profile before making investment decisions.