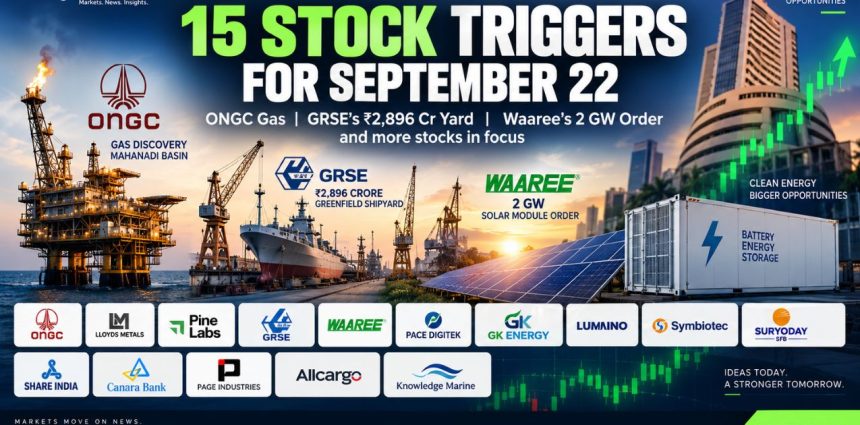
Fresh corporate disclosures put ONGC, Lloyds Metals, Pine Labs, GRSE, Waaree Energies, Pace Digitek and nine other stocks in focus. But the market reaction may depend on how quickly each headline translates into earnings, cash flow or price discovery.
Market data as of the September 21, 2026, close unless stated otherwise.
Fresh corporate disclosures from September 21 have put 15 stocks in focus for Tuesday’s trade, spanning an offshore gas discovery, a ₹2,896 crore greenfield shipyard, a 2 GW solar-module order, battery-storage contracts, fundraising plans, quarterly earnings and a major block deal.
The immediate market question, however, is not simply which announcement is the biggest.
It is how much of each announcement can actually translate into earnings, cash flow, capacity utilisation or near-term price discovery.
The distinction matters. ONGC has found gas, but commercial development still requires appraisal. Waaree Energies has secured a 2 GW module order, but the contract value has not been disclosed. GRSE has approved ₹2,896 crore of capex, but the earnings benefit lies ahead. Pine Labs faces a potentially large secondary share sale, where the block price could matter more to Tuesday’s trading than the company’s underlying growth story.
Meanwhile, BESS-related names such as Pace Digitek and GK Energy are receiving fresh order visibility just as India’s energy-storage investment cycle expands.
Monday market setup: Nifty clears 23,400, but resistance remains ahead.
Indian benchmark indices ended higher on Monday.
The Nifty 50 closed at 23,414.30, gaining 67.90 points or 0.29%, while the Sensex settled at 74,858.99, up 564.03 points or 0.76%. The provisional closing-auction levels were slightly higher at 23,429 and 74,894.86, which explains the different closing numbers appearing in some market reports.
The Nifty has been attempting to build a short-term recovery after a prolonged period of weakness. Market commentary for Tuesday places the immediate resistance zone around 23,500–23,600, with 23,300 and 23,000 viewed as important downside reference levels.
The overnight backdrop is firmer. GIFT Nifty was trading above 23,500 in the early Tuesday trade, suggesting a positive start if the indication holds into the opening bell. Asian stocks were also higher, helped by strength in US technology shares.
But the setup is not without uncertainty. Crude remains a key variable, with Brent around the $100-a-barrel zone, while geopolitical and global trade developments can still alter risk appetite quickly.
That leaves a clear market tension for Tuesday: stronger global cues are supporting the opening setup, but domestic equities still need to sustain momentum through resistance levels while company-specific catalysts compete for attention.
Check Live: NIFTY50, SENSEX, GIFT NIFTY
The 15 stocks to watch on September 22
| Stock | September 21 development | Key market variable |
|---|---|---|
| ONGC | Gas discovery in Mahanadi Offshore Basin | Appraisal and commercial viability |
| Lloyds Metals | ₹190 crore DRI expansion + ₹1,550 crore NCD programme | Capacity utilisation and financing |
| Pine Labs | Mastercard Asia-Pacific stake sale | Block price and supply pressure |
| GRSE | ₹2,896 crore Raichak shipyard capex | Execution and future capacity utilisation |
| Waaree Energies | 2 GW solar-module supply order | Contract value and execution |
| Pace Digitek | ₹488.46 crore BESS award | Execution by December 2026 |
| GK Energy | 150 MW/300 MWh BESS award | Project commissioning and contracted revenue |
| Lumino Industries | Q1 profit up about 32% | Margin and order-book conversion |
| Symbiotec Pharmalab | Q1 profit down about 53% | Margin recovery |
| Suryoday SFB | Up to ₹400 crore NCD issue | Capital cost and capital adequacy |
| Share India Securities | ₹200 crore warrant proposal | Final terms and dilution |
| Canara Bank | (P)Baa3 rating for $3 billion MTN programme | Future international debt issuance |
| Page Industries | Dubai court dismissed YFT claim in current state | Further litigation developments |
| Allcargo Global | August LCL volume down 7% YoY | Yield versus volume |
| Knowledge Marine | CARE outlook upgraded to Positive | Credit profile and execution |
1. ONGC: Gas discovery creates a fresh exploration trigger
Oil and Natural Gas Corporation reported a gas discovery at the MN-DW18-1-H-D well in the Mahanadi Offshore Basin, around 43 km off Odisha’s Konark coast.
The discovery was made on September 18 under ONGC’s Samudra Manthan exploration campaign. The well reached a total depth of about 1,623 metres, with gas encountered in the 1,441–1,452 metre interval. Initial flow and reservoir-pressure observations were described as encouraging.
The location could be strategically relevant because the well is relatively close to the Odisha coastline. ONGC has indicated that this proximity could offer potential for earlier monetisation, subject to appraisal and commercial evaluation.
That last qualification is important.
Discovery does not yet equal production
The market may initially focus on the word “discovery”. The financial value of the announcement, however, will depend on what happens next.
ONGC has not yet established from the disclosed information:
- commercially recoverable reserves;
- sustainable production capacity;
- the development investment required;
- the final development timetable; or
- the expected contribution to future earnings.
The expectation gap is therefore straightforward: the exploration headline arrives immediately, while the earnings impact remains dependent on further technical and commercial assessment.
For Tuesday, the market may therefore watch whether the stock reacts simply to the discovery headline or starts pricing in a larger exploration and monetisation narrative.
2. Lloyds Metals: ₹190 crore plant expansion comes alongside ₹1,550 crore NCD plan
Lloyds Metals and Energy has approved capacity expansion at its Direct Reduced Iron, or DRI, facilities at Ghugus in Chandrapur district and Konsari in Gadchiroli district, Maharashtra.
The company plans to invest approximately ₹140 crore at Ghugus and ₹50 crore at Konsari, taking the total investment to ₹190 crore. The expansion is expected to be completed within one year and will be funded through internal accruals.
But the same board meeting also approved a significantly larger financing programme.
The company will consider two NCD issues of up to ₹600 crore and ₹950 crore, respectively, taking the aggregate proposed debt issuance to ₹1,550 crore.
Why the two announcements need to be separated
The ₹190 crore capex programme is an operating expansion.
The ₹1,550 crore NCD proposal is a financing decision.
They may form part of the same broader growth strategy, but investors will need to assess them differently.
For the DRI expansion, the variables are:
capacity → commissioning → utilisation → production → margins.
For the NCD programme, the questions shift toward:
coupon → maturity → leverage → interest cost → capital allocation.
That creates another expectation gap. A larger plant can improve production capacity, but the benefit to profit depends on utilisation, steel/DRI realisations, input costs and the pace of commissioning.
3. Pine Labs: ₹892 crore block deal puts price discovery in focus
Pine Labs could be one of the most immediate trading-sensitive names on Tuesday.
Mastercard Asia-Pacific Pte. Ltd. is set to sell up to 4.97 crore Pine Labs shares, representing approximately 4.31% of the company, through a block deal.
The reported floor price is ₹179.50 a share. Pine Labs closed Monday at ₹193.70, putting the floor at a discount of about 7.33%. At the floor price, the transaction is worth roughly ₹892 crore. The deal is scheduled for September 22.
The selling shareholder held the same 4.97 crore shares as of June 2026, meaning the proposed transaction would represent an exit from its disclosed holding.
The trading question is different from the business question
Pine Labs recently delivered strong operating growth. Its consolidated first-quarter profit rose to around ₹19.6 crore from ₹4.8 crore, while revenue from operations increased about 19.6% year on year.
The company has also been expanding across merchant payments, acquiring, affordability and related financial infrastructure. Its FY26 investor presentation highlighted growth in mid-market and smaller merchants, overseas acquiring and newer payments/data products.
So Tuesday presents a classic market tension:
strong operating narrative versus immediate secondary share supply.
The block-deal clearing price and the market’s ability to absorb the stake may determine the early price action more directly than the company’s longer-term growth profile.
4. GRSE: ₹2,896 crore Raichak shipyard is a bigger capacity bet
Garden Reach Shipbuilders and Engineers approved a ₹2,896 crore capital budgetary outlay for a greenfield shipyard at Raichak in West Bengal’s South 24 Parganas district.
The proposed facility is intended to expand GRSE’s shipbuilding capacity across both naval and commercial segments. The approval came at the board’s September 21 meeting.
The number becomes more interesting when compared with the earlier Raichak plan.
GRSE had previously disclosed a Raichak investment estimate of around ₹2,500 crore. The latest ₹2,896 crore approval is therefore about ₹396 crore, or nearly 16%, higher than that earlier estimate.
Why the capex matters
This is not simply another order announcement.
It is a bet on future capacity.
The financial payoff should arrive through greater shipbuilding throughput over time rather than instantly after the board approval.
That makes the market’s next questions relatively straightforward:
- How quickly will the facility be constructed?
- How will the project be funded?
- When will the additional capacity become operational?
- How much utilisation can GRSE achieve?
- What kind of naval and commercial orders will ultimately flow through the facility?
GRSE’s existing order pipeline makes execution capacity particularly relevant. The company had reported a sizeable shipbuilding order book entering FY27, including a large naval component.
The headline number is ₹2,896 crore. The eventual earnings question is how much incremental productive capacity that investment creates.
5. Waaree Energies: 2 GW order strengthens visibility, but value is undisclosed
Waaree Energies has received an order to supply 2 GW of solar modules to a leading domestic solar developer.
The order was received on September 21, 2026, is described as a one-time arrangement and will be executed across FY27 and FY28. The company has not disclosed the commercial value of the contract.
The absence of a disclosed rupee value creates an important information gap.
A 2 GW order is clearly substantial in capacity terms. But investors cannot convert that figure into an exact revenue or margin contribution without knowing the agreed commercial consideration.
That makes Waaree a good example of the article’s broader theme:
A large operating headline does not automatically equal a precisely measurable earnings impact.
Waaree entered FY27 with a reported unexecuted order book of approximately ₹61,500 crore, giving the latest order a place within an already substantial backlog.
The company’s broader expansion strategy is also extensive. Its investor materials have outlined large planned investments across modules, cells, ingot-wafer manufacturing, BESS, inverters and power infrastructure.
The forward-looking risk is therefore not simply order availability. It is execution at scale while managing capex, working capital, margins and demand across multiple energy-transition businesses.
6. Pace Digitek: ₹488.46 crore BESS award adds near-term execution pressure
Pace Digitek’s material subsidiary Lineage Power Private Limited has secured a Letter of Award worth ₹488.46 crore, inclusive of taxes, from NTPC GE Power Services Private Limited.
The award covers supply, delivery, testing and supervision of erection, testing and commissioning of 5.015 MWh BESS containers, along with battery-management and energy-management systems. The contract also includes a 12-year comprehensive maintenance contract.
The project is scheduled for completion by December 31, 2026.
The maintenance component gives the order a longer tail beyond the initial supply and commissioning work.
Pace Digitek has been expanding its BESS manufacturing and project capabilities, making the latest contract relevant to the company’s strategy of moving further into the energy-storage value chain.
Why execution matters
The order value sounds significant relative to the company’s size, but the market will ultimately need to see:
order → manufacturing → delivery → commissioning → revenue recognition → cash collection.
The relatively tight completion deadline makes project execution a particularly important variable.
7. GK Energy: 150 MW/300 MWh project brings unusually clear contracted visibility
GK Energy has received a Letter of Award from Maharashtra State Electricity Distribution Company Ltd. for setting up 150 MW/300 MWh of Battery Energy Storage Systems in Maharashtra with viability-gap-funding support.
The project has a reported 15-year contractual period, with annual income of approximately ₹42.84 crore, while completion is targeted within 18 months.
This makes the GK Energy announcement different from Waaree’s solar-module order.
Waaree has disclosed capacity but not contract value.
GK Energy has disclosed capacity, project duration and reported annual income visibility.
For the market, the focus may therefore be on commissioning, funding structure and whether the company delivers the project within the agreed timeline.
The BESS opportunity is also becoming strategically important for GK Energy, which has identified energy storage as part of its longer-term renewable-energy expansion.
8. Lumino Industries: Q1 profit rises about 32%
Lumino Industries reported first-quarter FY27 results showing net profit of about ₹40 crore, up roughly 32% year on year, alongside revenue growth.
Operating EBITDA was reported at around ₹71 crore, with EBITDA margin improving to approximately 13.6%.
The company’s total order book stood around ₹3,059 crore, comprising approximately ₹1,046 crore of manufacturing orders and ₹2,013 crore of EPC orders as of June 30, according to the company’s reported results.
Lumino is also progressing with capacity expansion at its Ranihati facility, with phased capacity additions planned from H2 FY27.
The market will therefore have two numbers to assess:
profit growth now versus capacity growth ahead.
The question is whether the current margin improvement can remain intact as the company scales its order book and manufacturing base.
9. Symbiotec Pharmalab: Revenue rises, profit falls — the clearest margin warning
Symbiotec Pharmalab provides the opposite earnings signal.
The company reported first-quarter revenue growth, but net profit fell by roughly 53% year on year. Reported EBITDA also declined and the EBITDA margin contracted materially from the year-ago level.
Contemporaneous market reporting put consolidated revenue at around ₹218 crore and net profit at around ₹14.1 crore, with EBITDA margin down from roughly 28.5% to around 20.7%.
That creates a straightforward expectation gap:
top-line growth has continued, but profitability has not kept pace.
For investors watching the stock after the earnings disclosure, the key issue is whether margin pressure is temporary or whether it signals a more persistent change in product mix, costs or operating leverage.
10. Suryoday Small Finance Bank: Up to ₹400 crore Lower Tier II NCD programme
Suryoday Small Finance Bank’s board has approved raising up to ₹400 crore through Lower Tier II non-convertible debentures, with a specific approval for an initial tranche of up to ₹200 crore.
The instruments are proposed to be rated, listed, unsecured, subordinated, transferable and redeemable, and are intended to qualify as Lower Tier II capital.
For the stock market, the key issue is therefore not conventional equity dilution.
Instead, investors will likely monitor:
- the eventual pricing of the NCDs;
- the cost of capital;
- the impact on the bank’s capital position; and
- how the additional capital supports balance-sheet growth.
The first ₹200 crore tranche will provide the more immediate funding-market signal, while the full ₹400 crore authorisation indicates the potential scale of the broader programme.
11. Share India Securities: ₹200 crore warrants, ₹120 crore new subsidiary investment
Share India Securities has approved a proposal to raise up to ₹200 crore through a preferential issue of convertible warrants.
The board has also approved the incorporation of a new subsidiary and investment of up to ₹120 crore in the proposed entity.
The crucial point is that the final terms have not yet been fully established.
The Finance Committee has been authorised to finalise the detailed fund-raising terms, while investor names and other issue details are expected to be determined subsequently.
That means the ₹200 crore number should not yet be treated as the final economic impact on existing shareholders.
The market will need to see the eventual issue price, number of warrants, investor participation and conversion structure before calculating potential dilution.
12. Canara Bank: Moody’s gives provisional Baa3 rating to $3 billion MTN programme
Canara Bank has received a provisional (P)Baa3 senior-unsecured rating from Moody’s Ratings for its proposed $3 billion Medium Term Note programme.
The distinction between a programme rating and an actual debt issue is important.
The rating applies to the overall programme framework. Individual securities issued under the programme can still be subject to separate reviews based on their specific terms and conditions.
Therefore, the announcement should not be interpreted as Canara Bank having immediately raised $3 billion.
The more relevant future variables are:
whether the bank taps the programme, at what pricing, with what maturity and for what capital-management purpose.
This makes the announcement more of an international funding-market signal than a direct earnings trigger.
13. Page Industries: Dubai court dismisses Yellow Flower Trading claim in current state
Page Industries has disclosed a development in its Dubai litigation involving Yellow Flower Trading LLC.
The Dubai Court dismissed the claim in its current state after YFT failed to make a court-ordered expert deposit. The claimant was also directed to bear court costs and advocate fees.
The earlier claim had sought approximately AED 113.55 million, or nearly ₹294 crore based on contemporary conversions, plus interest.
The latest development reduces the immediate uncertainty surrounding that particular claim.
However, Page Industries has indicated that it will continue to monitor the matter and make further stock-exchange disclosures if material developments occur.
That makes the correct framing “claim dismissed in the current state”, rather than implying that every possible future legal issue has permanently disappeared.
14. Allcargo Global: Volume declines, efficiency improves
Allcargo Global’s August operational update showed LCL cargo volume of 711,000 cubic metres, down 7% year on year and 2% from July.
The company has been rationalising loss-making shipping routes, saying the move has helped improve yields.
Other operational indicators presented a mixed picture. FCL volume was lower year on year but higher month on month, while container utilisation improved.
That produces a classic volume-versus-yield tension.
A falling volume number can initially look negative.
But if low-margin traffic is being removed and the remaining network produces stronger yields and utilisation, the earnings effect can be different from the headline volume change.
The next few operating updates will show whether the efficiency strategy can compensate for lower throughput.
15. Knowledge Marine: CARE moves long-term outlook to Positive
Knowledge Marine & Engineering Works received a change in the outlook on its long-term bank facilities from Stable to Positive, while the CARE BBB+ rating was reaffirmed. The short-term rating was reaffirmed at A2.
The rating action covers long-term bank facilities and represents a change in outlook rather than a jump to a higher long-term rating.
That distinction matters.
The market may read the Positive outlook as an improvement in the credit assessment, but the company remains rated BBB+ for the relevant long-term facilities.
The update comes alongside continued growth in the company’s marine and shipbuilding-related business, including a recently disclosed ₹279.33 crore, 15-year green-tug contract from Mumbai Port Authority.
For Tuesday’s session, the rating update is therefore an incremental credit-profile development rather than a standalone earnings catalyst.
What connects these 15 stocks?
At first glance, the list looks random.
It is not.
The companies fall into four broad market themes.
| Market theme | Stocks | What investors are measuring |
|---|---|---|
| Capacity and orders | GRSE, Waaree, Pace Digitek, GK Energy, Lloyds Metals | Order conversion and utilisation |
| Exploration and strategic expansion | ONGC, GRSE | Future capacity and commercialisation |
| Capital and ownership changes | Pine Labs, Suryoday, Share India, Canara Bank | Funding cost, dilution and price discovery |
| Earnings and operating signals | Lumino, Symbiotec, Allcargo, Page Industries, Knowledge Marine | Margins, volumes, litigation and credit quality |
The common thread is translation.
A gas discovery must become commercial reserves.
A capex plan must become productive capacity.
An order must become revenue.
A fundraising announcement must become productive capital.
A block deal must clear without creating disorderly supply.
An earnings beat must survive subsequent quarters.
Three expectation gaps that could matter most Tuesday
ONGC: discovery versus commercialisation
The discovery is confirmed.
The economic value is not.
Further appraisal and commercial evaluation remain necessary.
Waaree: 2 GW versus undisclosed contract value
The physical capacity of the order is known.
The rupee value and resulting margin contribution are not.
GRSE: ₹2,896 crore investment versus future earnings
The investment has been approved.
The revenue and profit generated from the additional shipyard capacity are future outcomes dependent on construction and utilisation.
The most immediate trading event may not be the biggest headline
Among all 15 developments, Pine Labs stands apart because the announcement concerns actual share supply rather than future operating capacity.
Mastercard Asia-Pacific is proposing to sell 4.97 crore shares at a floor price of ₹179.50. With Pine Labs having closed at ₹193.70 on Monday, the discount provides a concrete reference point for Tuesday’s price discovery.
GRSE and Waaree are fundamentally different.
Their announcements are long-duration corporate events. Their stock-market reactions may begin immediately, but the economic consequences unfold over months or years.
That difference could lead to very different price-volume behaviour across the watchlist.
BESS becomes a second major theme
The simultaneous developments at Pace Digitek and GK Energy also highlight the growing importance of battery energy storage in corporate order books.
Pace Digitek has secured the ₹488.46 crore award from NTPC GE Power Services, including a long maintenance component.
GK Energy has secured a 150 MW/300 MWh project with a 15-year contract and reported annual income visibility of about ₹42.84 crore.
The two deals are not directly comparable.
Pace’s announcement focuses on equipment supply, commissioning and maintenance.
GK Energy’s project is structured around longer-duration contracted project income.
But together they point to a market theme worth watching: BESS is shifting from a future technology narrative toward actual contracts and infrastructure deployment.
The forward-looking risk is that project execution, financing, equipment costs and commissioning schedules will determine how much of this pipeline eventually appears in reported earnings.
What traders may monitor at the opening bell
| Stock | Immediate trigger | What could confirm the market interpretation |
|---|---|---|
| Pine Labs | Mastercard block deal | Final clearing price and volumes |
| ONGC | Mahanadi gas discovery | Follow-up appraisal information |
| GRSE | ₹2,896 crore shipyard capex | Funding and project execution updates |
| Waaree Energies | 2 GW order | Order value and FY27-FY28 execution |
| Pace Digitek | ₹488.46 crore BESS award | Delivery and commissioning progress |
| Lloyds Metals | DRI expansion + NCDs | Capacity and financing terms |
| GK Energy | 150 MW/300 MWh BESS | Project execution |
| Lumino | Q1 profit growth | Margin sustainability |
| Symbiotec | 53% profit decline | Margin recovery |
| Suryoday SFB | ₹400 crore NCD programme | Issue pricing and capital impact |
| Share India | ₹200 crore warrants | Final issue terms |
| Canara Bank | $3 billion MTN rating | Subsequent debt issuance |
| Page Industries | Dubai claim dismissal | Further legal developments |
| Allcargo Global | LCL volume decline | Yield and utilisation improvement |
| Knowledge Marine | Positive outlook | Credit and business execution |
September 22 watchlist: headline impact versus earnings visibility
The most useful way to read Tuesday’s news flow may be to separate what changed today from what could change earnings tomorrow.
| Company | What changed now | What still has to happen |
|---|---|---|
| ONGC | Gas discovery | Commercial appraisal and development |
| GRSE | ₹2,896 crore capex approved | Build and utilise new shipyard |
| Waaree Energies | 2 GW order won | Execute FY27-FY28 deliveries |
| Pace Digitek | ₹488.46 crore award | Deliver by Dec. 31, 2026 |
| GK Energy | 150 MW/300 MWh award | Commission project and realise contracted income |
| Lloyds Metals | Expansion + NCD plans | Add capacity and manage financing |
| Pine Labs | Secondary stake sale | Complete price discovery |
| Lumino | Profit growth reported | Sustain margin and growth |
| Symbiotec | Profit sharply lower | Restore margins |
| Suryoday | NCD programme approved | Price and issue debt |
| Share India | Warrant fundraising approved | Finalise issue structure |
| Canara Bank | MTN programme provisionally rated | Access debt markets |
| Page Industries | Claim dismissed in current state | Monitor any further proceedings |
| Allcargo | Low-margin routes rationalised | Prove yield improvement |
| Knowledge Marine | Outlook improved | Convert operating progress into stronger credit metrics |
What could surprise the market?
Tuesday’s biggest surprise may not necessarily come from the company with the largest headline amount.
A smaller announcement can matter more when it changes an already closely watched earnings assumption.
For example:
Pine Labs: the block price can influence immediate supply-demand conditions.
Symbiotec: the margin decline can challenge expectations built around revenue growth.
Allcargo: lower volumes may look negative unless yield improvement becomes visible in financial performance.
Waaree: the 2 GW number is large, but the undisclosed contract value leaves investors without a precise earnings estimate.
ONGC: a commercially valuable discovery could become much more important if later appraisal confirms meaningful reserves.
This is where the headline-to-earnings gap becomes important.
Bottom view for September 22
The September 22 watchlist contains a mix of hard trading catalysts and longer-duration corporate developments.
Pine Labs has a clearly defined block-deal event with a disclosed floor price.
ONGC has a fresh exploration catalyst.
GRSE has committed to a large future-capacity investment.
Waaree has added another 2 GW module order to an already substantial order book.
Pace Digitek and GK Energy are adding BESS projects at different points of the energy-storage value chain.
Lloyds Metals is combining operational capacity expansion with a sizeable proposed debt programme.
On the earnings side, Lumino is showing profit growth while Symbiotec is confronting significant margin and profit pressure.
The capital-market names — Suryoday, Share India and Canara Bank — bring another dimension, where the eventual cost and structure of funding matter more than the headline size alone.
The central expectation gap for Tuesday is therefore clear: the largest corporate number is not automatically the largest near-term earnings catalyst.
For traders, the focus is likely to remain on price discovery, volume, execution milestones and follow-up disclosures rather than treating every announcement as an immediate change to fundamental value.
Read Next: India Wealth Management Market Set for $436 Billion — What Emkay’s 14% AUM Fall Signals
Risk disclosure: Corporate announcements, order wins, discoveries, capex approvals, fundraising plans and credit-rating actions do not guarantee future earnings or share-price performance. Order execution, financing costs, margins, project timelines, regulatory approvals, commodity prices and subsequent disclosures can materially change the eventual financial impact. Investors should verify exchange filings and company updates before acting on market-moving news.