Need to Know
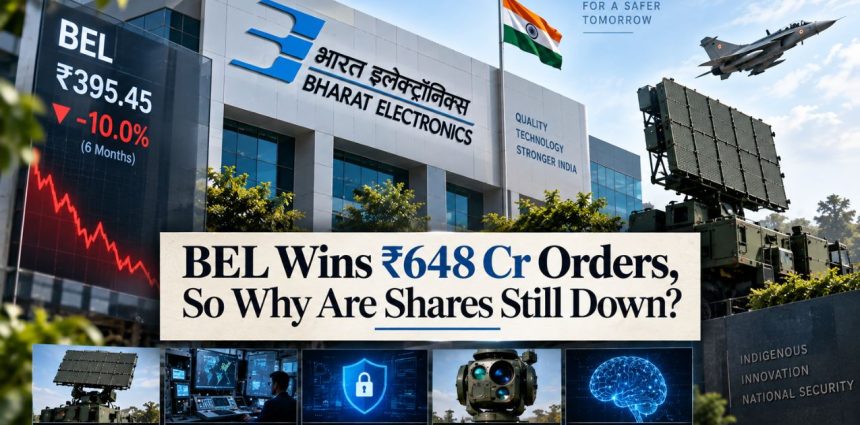
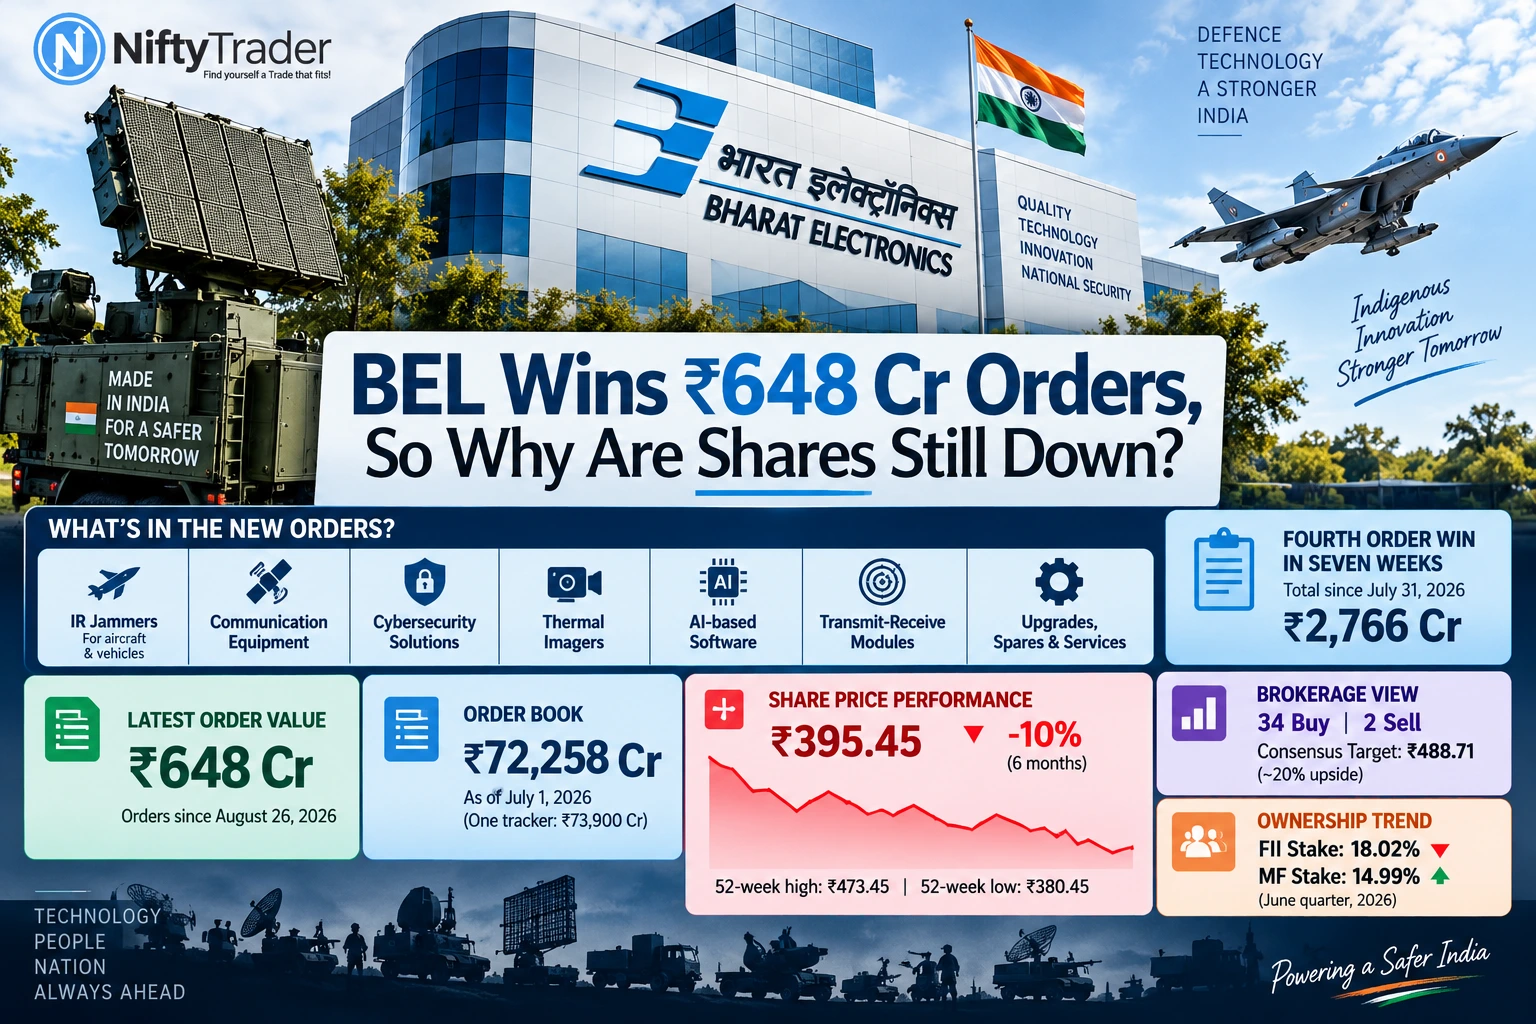
- Bharat Electronics (BEL) disclosed fresh orders worth Rs 648 crore since August 26, 2026, covering IR jammers, cybersecurity, AI software and communication gear
- This is BEL’s fourth order win in seven weeks; cumulative fresh orders since July 31 now total roughly Rs 2,766 crore, verified against BEL’s own NSE filing chain
- Despite the order streak, BEL stock closed at ₹395.45 on September 17, still down 10% over six months and 16.5% below its 52-week high of ₹473.45
- The Order book stood at ₹72,258 crore as of July 1, 2026 (one tracker cites ₹73,900 crore for the same period, flagged below)
- Brokerages remain net bullish: 34 Buy calls vs 2 Sell, with a ₹488.71 consensus target implying ~20% upside
- FIIs cut their BEL stake to 18.02% in the June quarter, even as domestic mutual funds raised theirs to 14.99%
Check Live: BHARAT ELECTRONICS Options Chart | Nifty Trader
What BEL Announced on September 17
Four order wins. Seven weeks. One falling stock. That’s the real story behind Thursday’s filing.
In a regulatory disclosure issued after market hours, Bharat Electronics, the Bengaluru-based Navratna defence major, told exchanges it has won additional orders worth Rs 648 crore since its last update on August 26, 2026.
This round leans digital and electronic-warfare heavy rather than big hardware: laser-based infrared jammers that shield aircraft and vehicles from heat-seeking missiles, communication equipment, a cybersecurity solution, thermal imagers, transducers, an AI-based software platform, transmit-receive modules for radar systems, plus routine upgrades, spares and services.
BEL didn’t break out individual contract values, standard practice for these periodic filings, which typically bundle several smaller wins into one cumulative number.
Inside BEL’s Rapid Order-Win Streak
Here’s what a single snippet won’t show you: BEL has filed four separate order disclosures in under seven weeks, confirmed sequential and non-overlapping by cross-checking BEL’s own NSE exchange filings.
| Disclosure Date | Order Value | Key Segments Covered |
|---|---|---|
| July 31, 2026 | ₹847 crore | Electro-optics, security operations centre, seekers, components |
| August 10, 2026 | ₹541 crore | Communication equipment, electro-optics, ammunition fuzes, CBRN systems |
| August 26, 2026 | ₹730 crore | Communication equipment, radar, avionics, tank subsystems, EVMs, jammers |
| September 17, 2026 | ₹648 crore | IR jammers, cybersecurity, thermal imagers, AI software, TR modules |
| 7-week cumulative | ₹2,766 crore | Verified via NSE filing chain — each stating value won since the prior disclosure |
That seven-week haul equals nearly 4% of BEL’s entire order book, added in under two months. Order wins at this pace aren’t the problem for BEL right now. Something else is.
BEL Share Price: Why the Rally Has Stalled Despite ₹2,766 Cr in Orders
BEL shares closed at ₹395.45 on the NSE on Thursday, up 2.51% on the day. That single-day pop, though, sits inside a much weaker six-month picture.
| Metric | Value |
|---|---|
| Close, Sept 17, 2026 | ₹395.45 (NSE, +2.51%) |
| 52-week high | ₹473.45 (March 6, 2026) |
| 52-week low | ₹380.45 (December 18, 2025) |
| 1-month return | -4.4% |
| 6-month return | -10% |
| 2026 YTD return | -1% |
| 3-year return | ~180-183% |
| Market capitalisation | ~₹2.89 lakh crore |
| TTM P/E ratio | ~48x-51x |
The stock is sitting closer to its 52-week low than its high. That’s the disconnect worth sitting with: BEL’s order-win news flow has been almost uninterrupted through July, August and September, yet the stock has drifted lower over the same stretch.
Valuation compression and profit-booking after a multi-year re-rating appear to be outweighing the steady drip of good operational news, at least for now.
On the often-quoted “183% in three years” figure: it checks out. One broker platform independently tracked BEL’s trailing three-year return at 180.58% as of September 10, 2026, close enough to the widely cited number that the claim holds up.
Also Check: BHARAT ELECTRONICS Ltd Futures — Live Price, Open Interest & Basis Analysis
Why This Matters: Q1 FY27 Financials & Order Book
Orders are only half the story. BEL’s June-quarter results, reported in late July, show a business still growing briskly, but with rising cost pressure underneath.
| Q1 FY27 Metric | Value | YoY Change |
|---|---|---|
| Consolidated net profit | ₹1,054.34 crore | +9% |
| Revenue from operations | ₹5,546.98 crore | +25% |
| Cost of materials | ₹3,041.23 crore | +55% |
| Order book (July 1, 2026) | ₹72,258 crore | One report cites ₹73,900 crore for the same date |
Revenue growing at 25% while profit grows at just 9% comes down almost entirely to that 55% jump in cost of materials. That’s the number worth watching most closely into Q2; if it doesn’t ease, margins take the hit even as the topline keeps climbing.
The order book stood at ₹72,258 crore as of July 1, 2026 (one Bloomberg-linked estimate puts this slightly higher, at ₹73,900 crore).
Separately, BEL raised its authorised share capital to ₹1,000 crore from ₹750 crore, subject to shareholder approval, a routine step that creates headroom for future bonus issues, not an active fundraise signal.
Also Read: BEL Q1 Results: Profit Beats Estimates as ₹73,882 Crore Order Book Stays in Focus
The Bigger Picture: India’s Rs 6.73 Lakh Crore Defence Procurement Wave
BEL’s order wins aren’t happening in a vacuum. They’re the visible, smaller edge of a much larger indigenous defence procurement cycle running through FY26.
Per the Ministry of Defence’s own Annual Report 2025-26, the Defence Acquisition Council accorded Acceptance of Necessity to 55 capital acquisition proposals worth approximately Rs 6.73 lakh crore over the year, spanning air defence missiles, armoured vehicle engines, unmanned systems, airborne early warning aircraft and naval platforms. A smaller Defence Procurement Board cleared six more proposals worth Rs 2,463.91 crore.
Two programmes anchor BEL’s medium-term growth case:
- QRSAM (“Anantshastram”) — an indigenous DRDO-designed, BEL-developed Quick Reaction Surface-to-Air Missile system, already cleared by the DAC, with a widely reported deal value near Rs 30,000 crore once it converts into a firm order
- Project Kusha — a long-range air defence system with Acceptance of Necessity worth Rs 21,700 crore dating to September 2023, where BEL is DRDO’s development partner for radars and control systems; an interceptor variant reportedly completed a flight test in July 2026
The government’s own numbers point to a structural tailwind too: the share of the defence capital acquisition budget reserved exclusively for domestic procurement has climbed from 58% to 75%, with a quarter of that domestic slice ring-fenced for private players.
On the ground, BEL has secured 75 hectares in the Uttar Pradesh Defence Industrial Corridor at Chitrakoot, backed by an investment exceeding Rs 600 crore, earmarked for QRSAM, Kusha and next-generation radar manufacturing.
FII, DII & Promoter Holding: What Institutional Money Is Doing
BEL is roughly half government-owned, so tracking the rest of the float matters — and right now, it’s telling a more cautious story than the order headlines suggest.
| Shareholder Category | March 2026 Qtr | June 2026 Qtr | Change |
|---|---|---|---|
| Promoter (Government of India) | 51.14% | 51.14% | Unchanged |
| FII/FPI | 19.51% | 18.02% | -1.49 pts |
| Mutual Funds (domestic) | 14.28% | 14.99% | +0.71 pts |
| Total Institutional Holding | 39.51% | 39.04% | -0.47 pts |
The number of FII/FPI investors holding BEL also fell, from 1,242 to 1,166, over the same quarter. Put next to the stock’s six-month slide, this looks like classic late-cycle rotation, with foreign investors trimming a name that’s already delivered a multi-year re-rating, while domestic mutual funds quietly add, rather than a broader loss of institutional confidence in the story.
Track Live: FII DII | NIFTYTRADER
What Brokerages Are Watching
The Street hasn’t turned bearish on BEL, even with the stock underperforming. As of late August, BEL carried 34 Buy calls against just 2 Sell ratings, with a 12-month consensus target of ₹488.71, implying roughly 20% upside from then-prevailing levels, per Bloomberg-sourced data reported by Business Today.
Individual targets from that window: Macquarie at ₹550 (Buy), InCred Research at ₹515, Ashika Institutional Equities at ₹506, Mirae Asset Securities at ₹494, and Axis Capital at ₹478.
The order book itself is diversified rather than riding on one programme, electronic fuzes account for roughly ₹4,300 crore, LRSAM around ₹3,500 crore, LCA electronics near ₹3,200 crore, BMP-II upgrades about ₹2,800 crore, and Ashwini radar close to ₹2,460 crore, per Ashika Institutional Equities.
That spread is what lets brokerages stay bullish through a six-month stock slide; the earnings visibility doesn’t depend on any single contract landing on schedule.
What’s Next for BEL: The Triggers That Could Decide the Next Leg
Three events would move BEL’s stock far more than any single “additional order” filing ever will.
QRSAM converting from Acceptance of Necessity to a signed, firm contract. At a reported Rs 30,000 crore, this alone could expand BEL’s current order book by more than 40% in one stroke.
Project Kusha advancing from development to a Letter of Intent. At Rs 21,700 crore, this would be BEL’s second mega-order in air defence and would cement its role as DRDO’s lead radar and control-systems partner.
Export momentum building. BEL has flagged an ambition to lift exports from roughly 4-5% of revenue towards 10%, against the backdrop of India’s defence exports hitting a record Rs 23,622 crore in FY25, with a national target of Rs 50,000 crore by 2029.
Set against all that, the near-term risk is far more mundane: rising input costs (that 55% YoY jump in material costs), the gap between paper approvals and executed revenue, and whether a stock trading near 48-51 times earnings has already priced in a good chunk of this optimism.
The next two quarters, where cost trends either ease or persist, and where QRSAM either converts or keeps slipping, will say more about BEL’s next leg than this week’s Rs 648 crore filing does on its own.
Read Next: Sept 18 Stocks to Watch: Tata Leadership, BEL Orders and Bharat Forge in Focus
This article is for informational purposes only and should not be construed as investment advice. Please consult a SEBI-registered financial advisor before making investment decisions. Figures are sourced from BEL’s regulatory filings (NSE) and reports by Upstox, Business Standard, Business Today, EquityBulls and the Ministry of Defence’s Annual Report 2025-26.