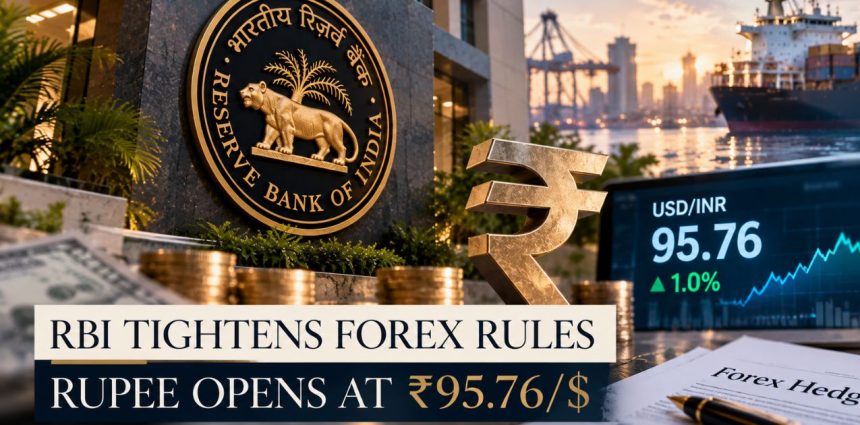
The RBI’s weekend rupee defence sets two goals against each other. It wants to choke off the forward-dollar buying that has been dragging the currency down, yet companies still need affordable cover for current-account exposures such as imports.
Within days, banks are asking the central bank to change how that cost is collected. Four people familiar with the discussions told Reuters that lenders, through a forex industry body, want the 20% cash deposit on large hedges removed.
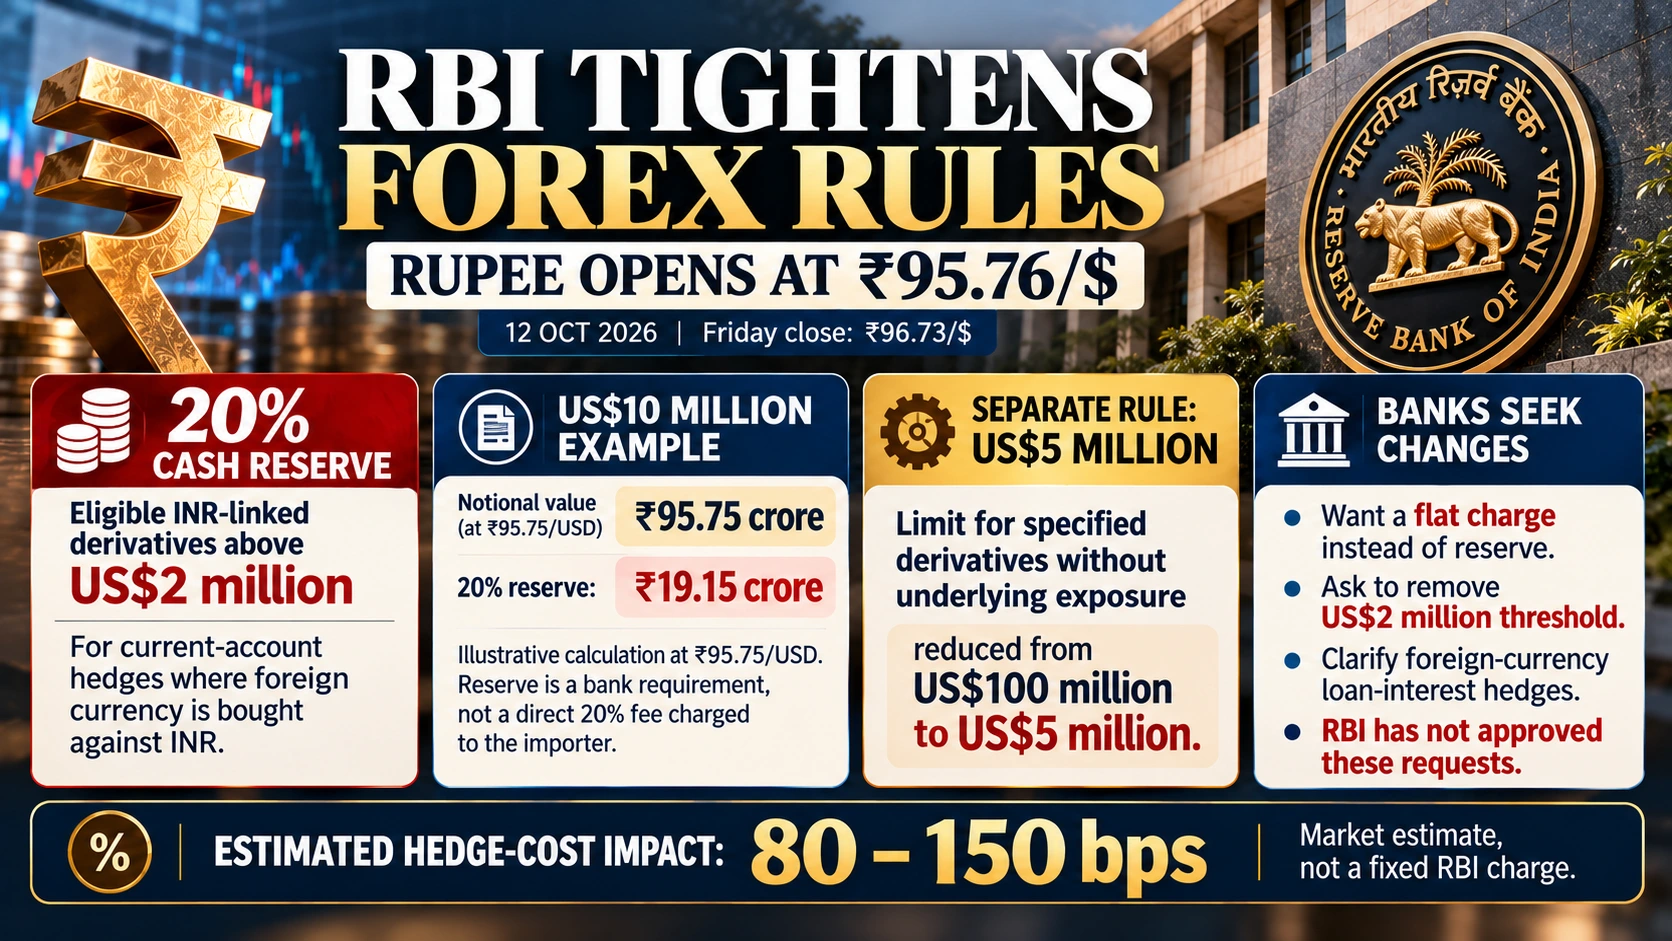
They proposed a flat charge instead and asked the RBI to drop the $2 million threshold that triggers the deposit and to clarify whether hedges on foreign-currency loan interest are covered. The rupee opened Monday at 95.76 per dollar, about 1% stronger than Friday’s 96.73 close, and is still down 6.6% this year.
WHAT BANKS WANT FROM THE RBI
Banks argue that a flat charge would still raise hedging costs without tying up rupee liquidity in their treasury operations. A banker who attended a Foreign Exchange Dealers’ Association of India meeting on Sunday told Reuters that costs will be passed on to clients and that a direct charge in paisa terms “removes a lot of friction”.
Banks typically charge importers a fixed margin in paisa terms, one banker said, and that approach is no longer feasible under the new rule. The RBI did not immediately respond to Reuters’ request for comment.
HOW THE 20% RESERVE WORKS
Under Circular No. 26 dated October 10, authorised dealers must hold a Foreign Exchange Risk Reserve equal to 20% of the rupee value of each qualifying contract. It applies to contracts above $2 million used to hedge current-account purchases of foreign currency. The cash is deposited with the RBI daily and kept until the contract ends. It covers only contracts undertaken after the circular.
The reserve is the bank’s obligation, not a 20% fee billed to the importer. How much of the resulting cost reaches clients is the open question.
A NiftyTrader illustration, not an RBI figure: at about Rs 95.75 per dollar, a $10 million forward purchase has a notional value of roughly Rs 95.75 crore. The bank would have to keep about Rs 19.15 crore in cash with the RBI against it.
Also Read: RBI Forex Rules: $5 Million Limit Replaces $100 Million, 20% Cash Reserve Added
TWO RULES, TWO THRESHOLDS: $2 MILLION VS $5 MILLION
The $2 million line is separate from the $5 million limit. Circular No. 25 cut the threshold from $100 million to $5 million equivalent for hedges of contracted exposure taken without establishing the underlying exposure. It cut the same limit for positions in exchange-traded currency derivatives, counted across all exchanges together.
It also bars rebooking of rupee derivative contracts cancelled after the directions, whether deliverable or non-deliverable. Users must now give banks an undertaking that the same exposure has not been hedged with another bank. The $2 million figure only decides which current-account hedges attract the 20% reserve.
THE COST: 80 TO 150 BASIS POINTS, DEPENDING ON PASS-THROUGH
Six bankers told Reuters the measures could raise hedging costs by 80 to 150 basis points, depending on how much of the extra cost banks pass on to clients. The impact will not be uniform. Citi economists estimate that Rs 60,000 crore to Rs 70,000 crore ($6.27 billion to $7.31 billion) of liquidity could be absorbed even if importer hedging falls substantially.
THE HEDGE-SPLITTING WORRY
Banks fear companies will slice large hedges into lots of $2 million or less to avoid the deposit. They say policing this would be hard, because they cannot easily question clients booking several smaller deals.
The circular already anticipates the tactic. It says any attempt to dodge the threshold through multiple transactions with one or more banks will be treated as a violation. The dispute is less about whether splitting is allowed, because it is not, and more about who has to detect it.
WHAT THE RULE DOES NOT COVER
The reserve is narrow by design. It does not cover companies hedging external commercial borrowings or foreign portfolio investors hedging their Indian investments.
One banker said it also excludes capital-account items such as repaying principal on overseas borrowings. Interest payments are the grey area. They are generally recorded under the current account in balance-of-payments accounting, which is why the RBI’s answer matters.
WHY THE RBI MOVED
Corporate purchases of forward dollars rose to a record $77 billion in September, up 80% from a year earlier, against sales of $41 billion, clearing house data showed.
The rupee fell near its all-time low of 96.96 last week, despite $140 billion raised through special dollar deposit schemes and higher interest rates.
The RBI is also selling dollars to Indian Oil, HPCL and BPCL through designated banks from October 12, until further notice. Kunal Kurani of Mecklai Financial said the RBI is now targeting two big sources of daily dollar demand: oil companies and importers.
THE FORWARD-PREMIUM PUZZLE
The cost of cover may move in two directions at once. Reuters reported, in a story carried by Moneycontrol, that the reserve could push up the premiums importers pay, while lower importer demand could pull interbank premiums down.
Barclays’ Mitul Kotecha said balance-sheet costs, reduced liquidity and the RBI’s own management of its forward book could push pricing the other way. In plain terms, the interbank forward premium and the all-in price a client pays may diverge.
WHAT TO WATCH NEXT
Watch whether the RBI softens or clarifies the rule. Also watch oil and foreign flows. Kotecha said the measures change where and when dollars are bought, not the demand behind oil imports, trade flows and capital outflows.
Kurani added that past experience suggests such fixes have limited staying power unless the underlying pressures ease. Track daily institutional flows on NiftyTrader’s FII-DII Tracker: niftytrader.in/fii-dii-data.
BOTTOM LINE: DEFENDING THE RUPEE VS. KEEPING HEDGES AFFORDABLE
The RBI has made forward-dollar buying costlier. Banks now want to decide how that cost is collected, as a flat fee or as locked-up cash. The next move is the RBI’s. Whether it softens the deposit, holds the $2 million trigger or settles the interest-payment question, the lasting test is crude prices and foreign flows, not the rule alone.
Read Next: Poonawalla Fincorp Q2FY27: ROA Hits 2.18%, but Can the Credit-Cost Ratio Stay Low?
Disclaimer: This article is for informational purposes only and is not investment advice or a recommendation to buy, sell or hold any security. NiftyTrader is a SEBI-registered platform. Investments in securities markets are subject to market risk. Read all related documents carefully before investing.