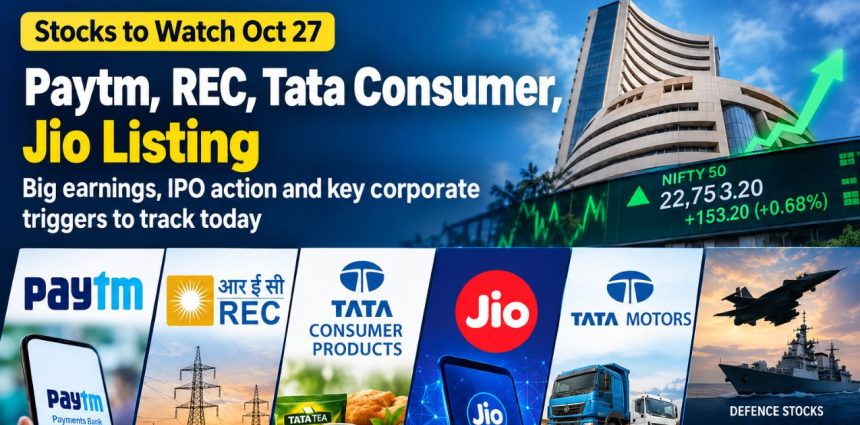
Paytm’s latest quarterly profit looks dramatically higher than a year ago, but an exceptional impairment in the comparison period changes the underlying picture. Tata Consumer Products reported strong earnings growth, REC’s profit declined, and fresh defence-sector developments have added another set of corporate triggers.
These developments come as the Nifty 50 attempts to recover after four consecutive sessions of losses. The index rebounded 365.85 points from Monday’s intraday low to close at 22,753.20, its highest level of the session, supported by buying in metal, IT and other heavyweight shares. However, elevated crude oil prices, foreign investor selling and monthly derivatives expiry leave room for renewed volatility.
Investors will also track Jio Platforms IPO share credits ahead of its planned October 28 listing, while Tata Motors’ Iveco takeover offer has crossed a key acceptance threshold.
Need to Know
- Paytm: Q2 FY27 profit after tax reached ₹225 crore, but the year-ago comparison included a ₹190 crore joint-venture loan impairment.
- Tata Consumer: Revenue rose 14% year on year to ₹5,661 crore, with stronger operating earnings.
- REC: Net profit fell 21.2%, while its second interim dividend of ₹3.50 per share was lower than the first interim payout this financial year.
- Defence stocks: Procurement proposals worth ₹2.12 lakh crore received in-principle approval.
- Jio Platforms IPO: The issue closed 22.19 times subscribed, with refunds and share credits scheduled for October 27 ahead of the planned October 28 listing.
- Tata Motors: Iveco’s takeover offer crossed the 80% acceptance threshold, reaching 87.8%.
Market Snapshot: October 27
| Indicator | Latest available reading |
|---|---|
| Nifty 50 close, October 26 | 22,753.20 |
| Nifty 50 daily gain | 153.20 points (+0.68%) |
| Nifty intraday low | 22,387.35 |
| Recovery from intraday low | 365.85 points |
| Sensex close | 73,606.75 |
| GIFT Nifty | 22,668.50 at 8:29 AM IST |
The GIFT Nifty reading is an earlier pre-market snapshot, not the confirmed opening level. Refresh it before publication if the article is posted after 8:29 AM IST.
Monday’s recovery was supported by buying in metal, IT and other heavyweight shares rather than earnings alone. Nevertheless, the upcoming monthly derivatives expiry could amplify stock and index moves. Brent crude prices near $115 a barrel, and continued foreign investor selling remains a risk for the domestic market.
The US Federal Reserve’s October 27–28 meeting is another event investors are watching. Its policy announcement is expected on Wednesday in the US, corresponding to late Wednesday night or early Thursday morning in India, depending on the release time.
Track Live: NIFTY 50, SENSEX, GIFT NIFTY
Stocks to Watch After Q2 Results
1. Paytm: The Profit Jump Has a Catch
One 97 Communications, which operates Paytm, reported Q2 FY27 profit after tax of ₹225 crore, compared with ₹21 crore a year earlier. Revenue rose 28% to ₹2,648 crore, while EBITDA increased 90% to ₹270 crore. EBITDA margin reached 10%, according to the company’s results announcement.
However, the year-ago quarter included a ₹190 crore joint-venture loan impairment. Adding that charge back to the reported ₹21 crore profit produces an approximate adjusted comparison base of ₹211 crore. Against that figure, the latest ₹225 crore profit is only around 7% higher.
This is an illustrative adjustment, not a replacement for reported PAT. It assumes the impairment can be added back without other accounting or tax adjustments. The distinction matters because the headline comparison suggests a much larger earnings acceleration than the adjusted figures indicate.
Paytm also announced proposed investments of up to ₹500 crore each in Paytm Cloud Technologies and Paytm Singapore. These investments are relevant to the company’s expansion plans, but the final deployment and financial impact should be assessed against the applicable board approvals and exchange disclosures.
What matters: Revenue growth, operating leverage, the quality of reported profit and the implications of the proposed investments.
2. Tata Consumer Products: Strong Revenue and Operating Growth
Tata Consumer Products reported revenue from operations of ₹5,661 crore in Q2 FY27, up 14% year on year. EBITDA rose to ₹794 crore, while group net profit increased to approximately ₹470 crore.
The company reported 11% underlying volume growth in its India branded business. Its growth businesses expanded 40% and accounted for 38% of its India business.
The results indicate continued growth in branded consumer products, although category-level performance remains important. Flat India tea volumes show that the expansion is not uniform across all products.
What matters: Volume growth, operating margins and whether the newer businesses continue contributing to overall expansion.
3. REC: Profit Declines as Dividend Payout Moderates
REC reported a 21.2% year-on-year decline in net profit to approximately ₹3,478 crore in Q2 FY27.
The net interest income figure must be read on the correct reporting basis: published results summaries cite standalone net interest income of approximately ₹5,135 crore and consolidated net interest income of approximately ₹5,478 crore. These figures should not be interchanged.
REC declared a second interim dividend of ₹3.50 per equity share for FY27. This compares with the first interim dividend of ₹4.25 per share in the current financial year and ₹4.60 per share for the second interim dividend in the previous year.
The lower payout is a useful comparison for income-focused investors, but dividend amounts alone do not establish the company’s future distribution policy.
What matters: Standalone versus consolidated earnings, net interest income, asset quality and the dividend record date.
4. Sona BLW Precision Forgings: Growth Versus Margins
Sona BLW Precision Forgings, also known as Sona Comstar, remains in focus following its Q2 FY27 results.
The key issue is the balance between reported revenue and profit growth and the decline in EBITDA margin. Published coverage differs on some rounded revenue and profit figures, so the final article should use the company’s exchange-filed financial statements as the single source of record before printing exact amounts.
The margin comparison reported in results coverage is approximately 23% for the latest quarter against 25.2% a year earlier.
What matters: The exact exchange-filed revenue and PAT figures, margin movement and the contribution from battery-electric vehicle-related business.
5. Dalmia Bharat: Exceptional Loss and Operating Pressure
Dalmia Bharat reported a net loss of approximately ₹205 crore in Q2 FY27, compared with a profit of ₹239 crore in the year-ago quarter. The result included an exceptional loss of ₹339 crore.
Revenue rose 4.3% year on year to ₹3,563 crore, while EBITDA declined 29.2% to ₹493 crore. EBITDA margin contracted to 13.84% from 20.37%.
The exceptional item explains much of the reported loss, but the decline in operating earnings shows why investors should look beyond the headline PAT number. The company also declared an interim dividend of ₹4 per share.
What matters: Cost trends, operating margins and the impact of exceptional items.
6. DCM Shriram: Revenue Growth Fails to Lift Profit
DCM Shriram reported a 34.1% year-on-year decline in net profit to approximately ₹105 crore in Q2 FY27. Revenue increased 21% to ₹4,151 crore, but EBITDA fell 5.8% to ₹291 crore. Its EBITDA margin narrowed to 7.02% from 9% a year earlier.
The company also outlined investments across its businesses, including a Kota solar power plant, additional electrolysers and projects at its cement facility.
The contrast between revenue growth and declining profitability is the key takeaway. Planned investments may support future efficiency, but their benefits depend on implementation and operating performance.
What matters: Margin stabilisation, project execution and the effect of capital spending on future profitability.
7. Aequs: Higher Revenue, Wider Loss
Aequs reported revenue from operations of approximately ₹409.08 crore in Q2 FY27, up around 45% year on year. Its net loss widened to ₹52.39 crore from ₹20.59 crore in the year-ago quarter.
Reported operating profit also declined, indicating that revenue growth has not translated into stronger operating performance.
What matters: Cost control, margin recovery and whether additional revenue converts into improved earnings.
Corporate Triggers Beyond Earnings
8. Defence Stocks: ₹2.12 Lakh Crore Procurement Approvals
The Defence Acquisition Council approved capital procurement proposals worth approximately ₹2.12 lakh crore on October 26.
Hindustan Aeronautics, Bharat Electronics, Mazagon Dock Shipbuilders, Bharat Dynamics, Cochin Shipyard, Garden Reach Shipbuilders & Engineers, BEML and Paras Defence are among the stocks investors may monitor.
The proposals cover equipment for the Army, Navy and Air Force, including artillery systems, helicopters, air-defence equipment, drones and surveillance platforms.
Important: The approvals are in-principle Acceptance of Necessity decisions, not final purchase orders awarded to every listed company. Individual beneficiaries and the eventual revenue contribution will depend on subsequent procurement and contract-award processes.
9. Sigma Advanced Systems: Defence Order Worth About ₹973 Crore
Sigma Advanced Systems secured a reported order worth approximately $102.23 million, equivalent to about ₹973 crore, to manufacture and supply base bleed units for a NATO customer. The stated execution period is 12 months.
The company had also announced a separate order worth approximately $19.70 million, or ₹174 crore, for specialised ancillary subsystems for 155 mm artillery ammunition.
The order pipeline provides a company-specific trigger, but order value is not the same as immediate revenue or profit. Execution costs and delivery schedules will determine the financial contribution.
10. Tata Motors: Iveco Takeover Crosses an Acceptance Milestone
Tata Motors‘ takeover offer for Italian commercial vehicle maker Iveco crossed the required 80% acceptance threshold, reaching 87.8%, according to Reuters, citing an Italian stock-market filing.
The development is an important milestone in the acquisition process. However, it should not be described as final completion of the transaction unless the remaining closing conditions and formal completion have been confirmed.
What matters: The next transaction update, completion conditions and the implications for Tata Motors’ commercial vehicle business.
Jio Platforms IPO: Subscription, Allotment and Listing
Jio Platforms‘ ₹30,213 crore IPO closed on October 23 with an overall subscription of 22.19 times.
| IPO indicator | Detail |
|---|---|
| Issue size | ₹30,213 crore |
| Price band | ₹1,065–₹1,119 |
| Overall subscription | 22.19x |
| QIB subscription | 70.55x |
| NII subscription | 14x |
| Retail subscription | 2.72x |
| Allotment date | October 26 |
| Refunds and share credits | October 27 |
| Planned listing | October 28 |
The strong institutional demand stands out, with the QIB portion subscribed 70.55 times. Retail demand was more moderate at 2.72 times.
Investors should check their allotment status through the registrar or exchange channels rather than assume that share credits have already reached every successful applicant.
Grey-market premium estimates reported before the issue closed were unofficial and time-sensitive. They should not be treated as a reliable listing-price forecast or a guarantee of listing gains.
Reliance Industries is the listed parent company to monitor for related developments; Jio Platforms itself is not yet trading on the exchanges.
What Investors Should Watch
The strongest earnings-growth stories in this group are Tata Consumer and Paytm, although Paytm’s prior-year impairment makes the headline profit comparison less dramatic on an adjusted basis. REC, Dalmia Bharat, DCM Shriram and Aequs require closer attention to profitability, while Sona BLW’s margin trend should be checked against its exchange-filed results.
Defence procurement approvals, Sigma Advanced Systems’ order and Tata Motors’ Iveco transaction provide separate corporate catalysts. Jio Platforms’ upcoming listing remains a major event, but subscription demand alone does not establish the eventual market valuation.
Monday’s rebound is encouraging, but a weaker pre-market indication, elevated crude prices and derivatives-expiry volatility could complicate the next session. Investors should distinguish stock-specific developments from a sustained improvement in the broader market.
Read Next: Nifty October 27 Expiry: 366-Point Rebound as 22,700 Call OI Falls
Disclaimer: This article is for information only and is not investment advice. Reported earnings, procurement approvals, corporate transactions and IPO subscription figures do not guarantee share-price gains. Please review official exchange disclosures before making investment decisions.