IDFC First Bank Q2 FY27 Results Put Strong Growth Under the Spotlight
IDFC First Bank is approaching its Q2 FY27 results announcement with strong provisional loan growth, rising deposits and improved liquidity. However, investors will be watching whether this operational momentum translates into sustainable profits while the bank manages funding costs and asset quality risks.
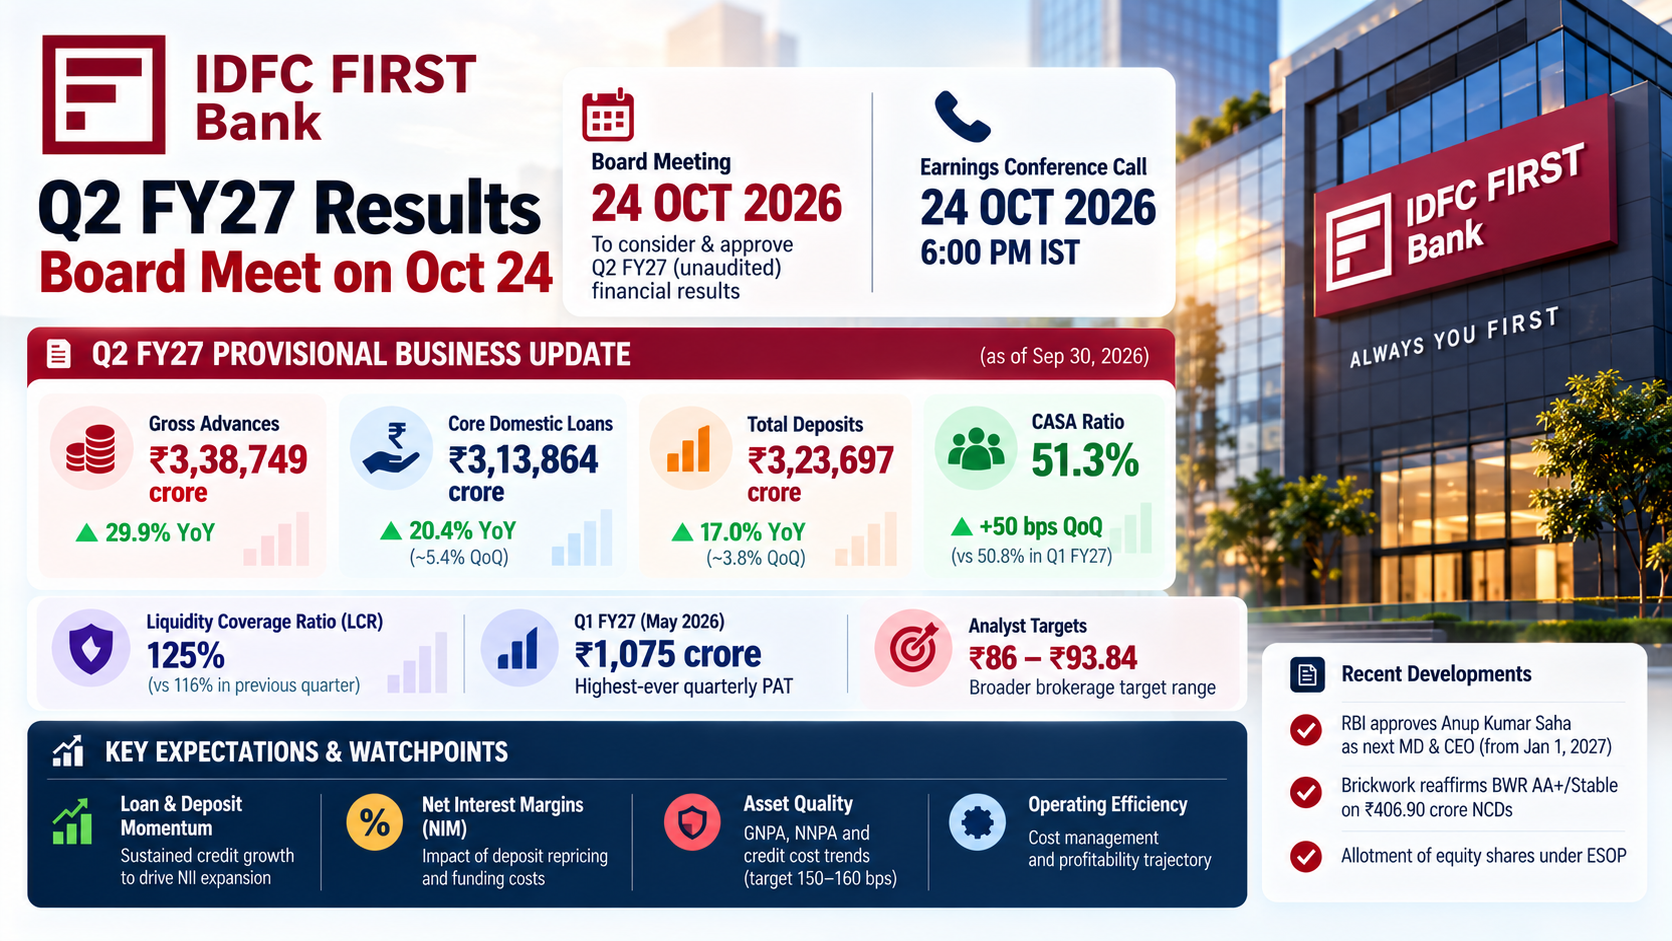
The bank’s board is scheduled to meet on Saturday, October 24, 2026, to consider and approve the unaudited standalone and consolidated financial results for the quarter and half-year ended September 30, 2026.
The earnings conference call is scheduled for 6:00 p.m. IST on the same day. The results could influence near-term sentiment towards IDFC First Bank shares as investors assess the bank’s profitability and outlook.
Track Live : NSE Option Chain — Live | BSE Option Chain — Live Sensex & Bankex Options Data Today
IDFC First Bank Q2 FY27 Results : Strong Loan Growth Supports IDFC First Bank’s Outlook
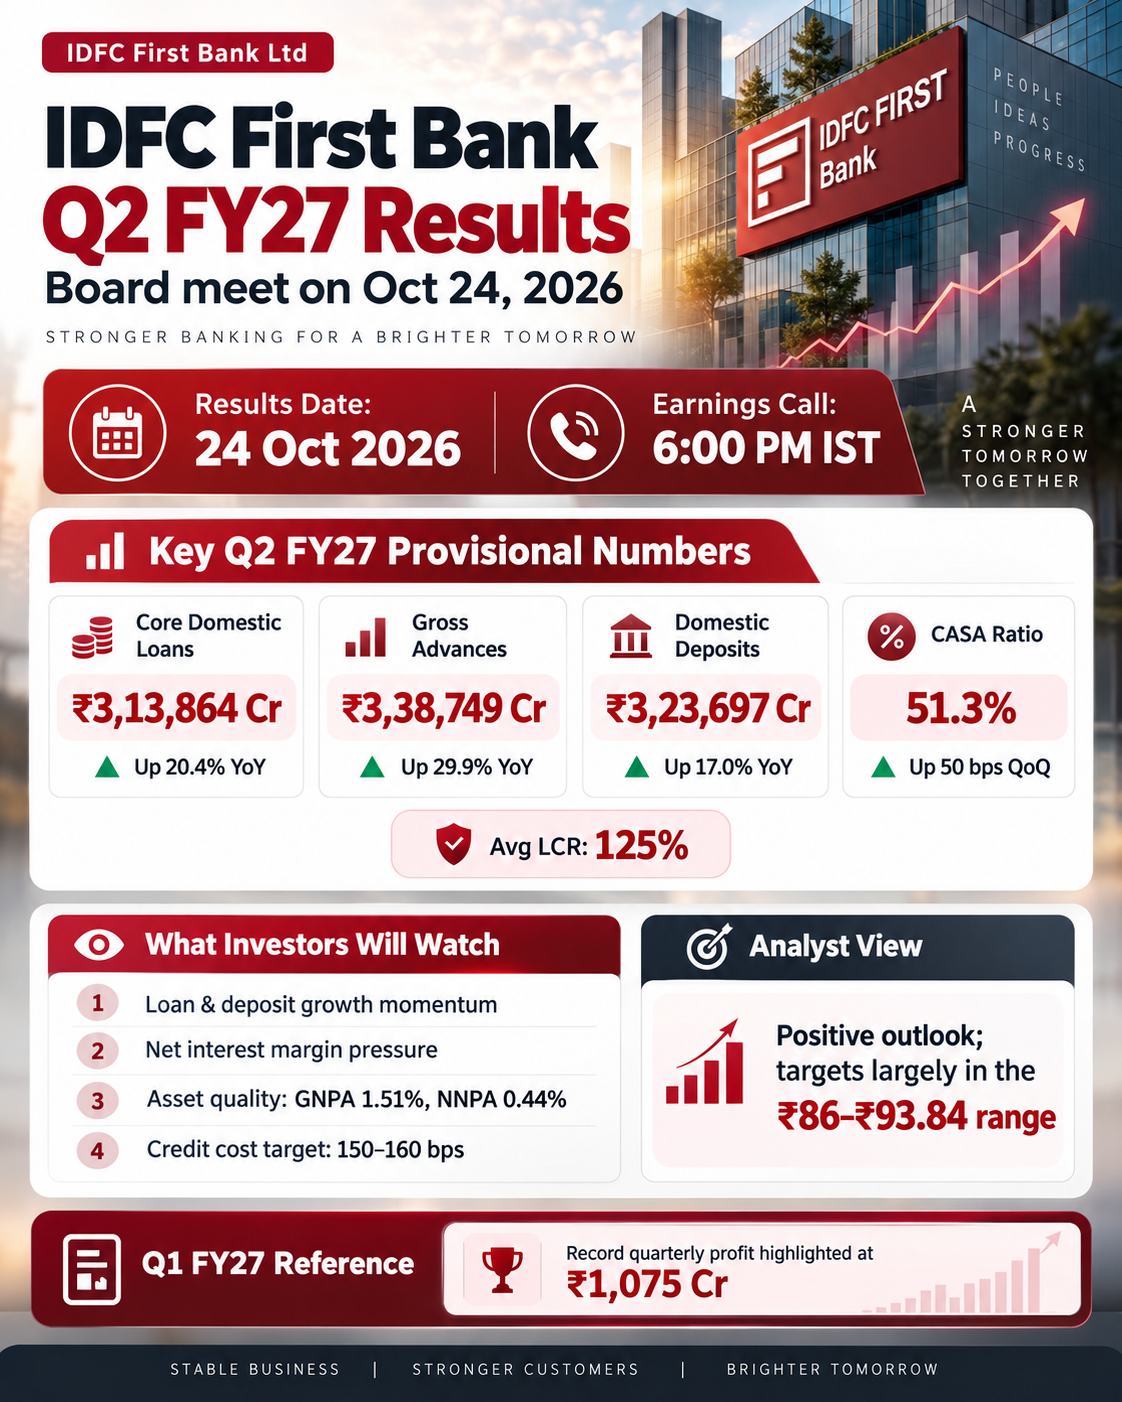
The bank’s provisional Q2 FY27 business update showed that core domestic loans increased 20.4% year-on-year (YoY) to ₹3,13,864 crore, representing approximately 5.4% sequential growth.
Overall gross advances reached ₹3,38,749 crore, up 29.9% YoY. The difference between core domestic loan growth and overall advances makes the composition of lending an important point to examine when the results are released.
Domestic deposits increased 17% YoY to ₹3,23,697 crore, growing approximately 3.8% quarter-on-quarter.
These figures indicate continued expansion in lending and deposit mobilisation. Investors will now look for confirmation that this growth is supporting net interest income without creating excessive pressure on funding costs.
IDFC First Bank Q2 FY27 Results: Board Meeting on October 24 — Key Facts and Investor Expectations
IDFC First Bank is scheduled to consider and approve its unaudited standalone and consolidated financial results for the quarter and half-year ended September 30, 2026, at its board meeting on Saturday, October 24, 2026. The bank has also scheduled its earnings conference call for 6:00 p.m. IST that day.
The key development ahead of the results is strong provisional business growth. However, investors will also be watching margins, funding costs, credit quality and the financial implications of the bank’s earlier fraud-related incident.
Key highlights at a glance
| Key indicator | Reported figure | Why it matters |
|---|---|---|
| Board meeting | October 24, 2026 | Q2 FY27 results to be considered |
| Earnings conference call | 6:00 p.m. IST, October 24 | Management discussion with investors and analysts |
| Core domestic loans | ₹3,13,864 crore | Up 20.4% year-on-year |
| Overall gross advances | ₹3,38,749 crore | Up 29.9% year-on-year, including FCNR(B)-related lending |
| Core total deposits | ₹3,23,697 crore | Up 17.0% year-on-year |
| Adjusted CASA ratio | 51.3% | Higher than 50.8% in the previous quarter |
| Average liquidity coverage ratio | 125% | Improved from 116% in Q1 FY27 |
Track Live : Opening Price Clues – What Pre-Market Data Says Today
What happened in the bank’s business during Q2 FY27?
The provisional update shows continued growth in lending and deposits. A major factor was the mobilisation of ₹34,390 crore in FCNR(B) deposits, a foreign-currency deposit category used by non-resident Indians.
| Business metric | Q2 FY27 provisional figure | Growth or comparison |
|---|---|---|
| Core loans and advances | ₹3,13,864 crore | +20.4% YoY; +5.4% QoQ |
| Core total deposits | ₹3,23,697 crore | +17.0% YoY; +3.8% QoQ |
| Customer deposits, excluding CDs | ₹3,16,529 crore | +17.6% YoY |
| Overall gross advances | ₹3,38,749 crore | +29.9% YoY |
| Overall total deposits | ₹3,48,582 crore | +25.9% YoY |
| CASA ratio, excluding FCNR(B) leverage | 51.3% | Up from 50.8% in Q1 FY27 |
| Average liquidity coverage ratio | 125% | Up from 116% in Q1 FY27 |
What are analysts expecting?
Published brokerage estimates compiled by Informist provide a more specific indication of the market’s expectations for the September quarter.
| Metric | Average estimate | Year-on-year comparison |
|---|---|---|
| Net interest income | ₹6,196 crore | Approximately +21% |
| Consolidated net profit | ₹1,033 crore | Approximately +193% |
| Expected sequential profit movement | — | Approximately −4% |
CASA Ratio and Liquidity Offer Encouraging Signals
IDFC First Bank’s CASA ratio improved to 51.3% in Q2 FY27, compared with 50.8% in the previous quarter. A higher current and savings account deposit share can help banks manage funding costs because these deposits are generally less expensive than term deposits.
The bank’s average Liquidity Coverage Ratio (LCR) also increased to 125%, up from 116% in Q1 FY27.
These improvements provide a positive starting point for the earnings announcement. However, the actual impact on profitability will depend on deposit pricing, lending yields and the bank’s ability to manage its overall cost of funds.
Q1 Profit Growth Sets a High Benchmark for Q2
Market trackers cited in the supplied material report record Q1 FY27 quarterly profit after tax of ₹1,075 crore. Another dataset lists net profit at ₹1,147.82 crore, alongside interest earned of ₹11,051 crore and gross profit of ₹2,625 crore.
Because the supplied sources contain different profit figures, investors should verify the final reported numbers before making direct comparisons.
The Q2 results will help establish whether the bank can maintain its earnings momentum while managing operating expenses, credit costs and funding pressures.
The ₹590 crore fraud-related issue
The earlier fraud-related disclosure remains an important risk to monitor. In February 2026, the bank identified suspected fraudulent activity involving certain Haryana government accounts, with discrepancies of approximately ₹590 crore. It subsequently reported repaying ₹583 crore, including principal and interest, to the relevant government departments.
Read More : Jio’s IPO Just Rewrote the Record Books, and Institutions Are Bidding 29 Times Their Quota
Here’s What Happened Today and Why Traders Reacted
Investors are preparing for the October 24 results after a period of sharp movements in IDFC First Bank shares.
The supplied information cites a roughly 9% share price rise following strong Q1 FY27 profit figures. It also reports a separate episode in which the stock fell as much as 20% after the bank disclosed a suspected fraud involving ₹590 crore.
These were separate developments, and neither should be confused with a market reaction to the upcoming Q2 results.
The key factors investors are likely to monitor include:
- Earnings growth: Whether the bank sustains its strong Q1 profitability.
- Net interest margins: Whether deposit repricing and delays in deploying FCNR(B) deposits affect profitability.
- Asset quality: Whether gross and net non-performing asset ratios remain controlled.
- Credit costs: Whether the bank progresses towards its stated target range of 150–160 basis points.
What will investors watch in the Q2 results?
| Indicator | What investors want to see | Why it matters |
|---|---|---|
| Net interest income (NII) | Sustainable growth | Measures the bank’s core interest-earning performance |
| Net interest margin (NIM) | Stability or improvement | Indicates whether lending returns are keeping pace with funding costs |
| Net profit | Growth versus Q2 FY26 and Q1 FY27 | Tests whether business expansion is translating into earnings |
| Credit costs | Continued control | Higher provisions can reduce profits |
| Gross and net NPAs | Stable or improving ratios | Indicates the quality of the loan book |
| Operating expenses | Better efficiency | Helps determine whether growth is improving profitability |
The supplied material cites Q1 FY27 net profit of ₹1,075 crore in one account and ₹1,147.82 crore in another market-tracker figure. These should not be treated as interchangeable without checking whether they refer to standalone or consolidated results and whether they use the same reporting basis.