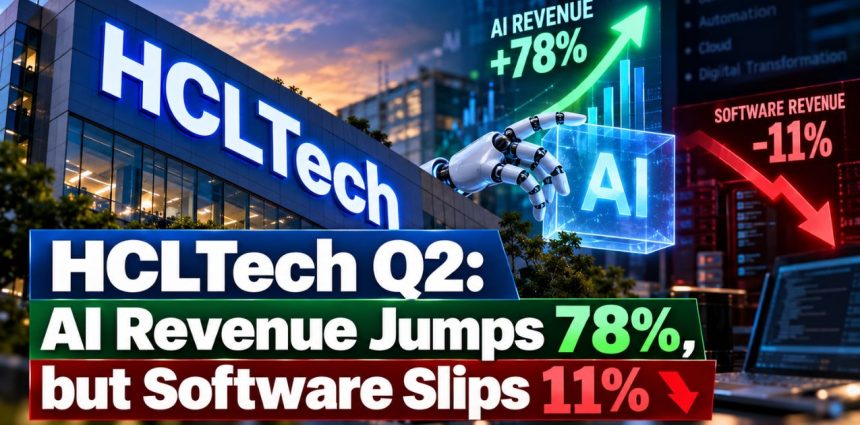
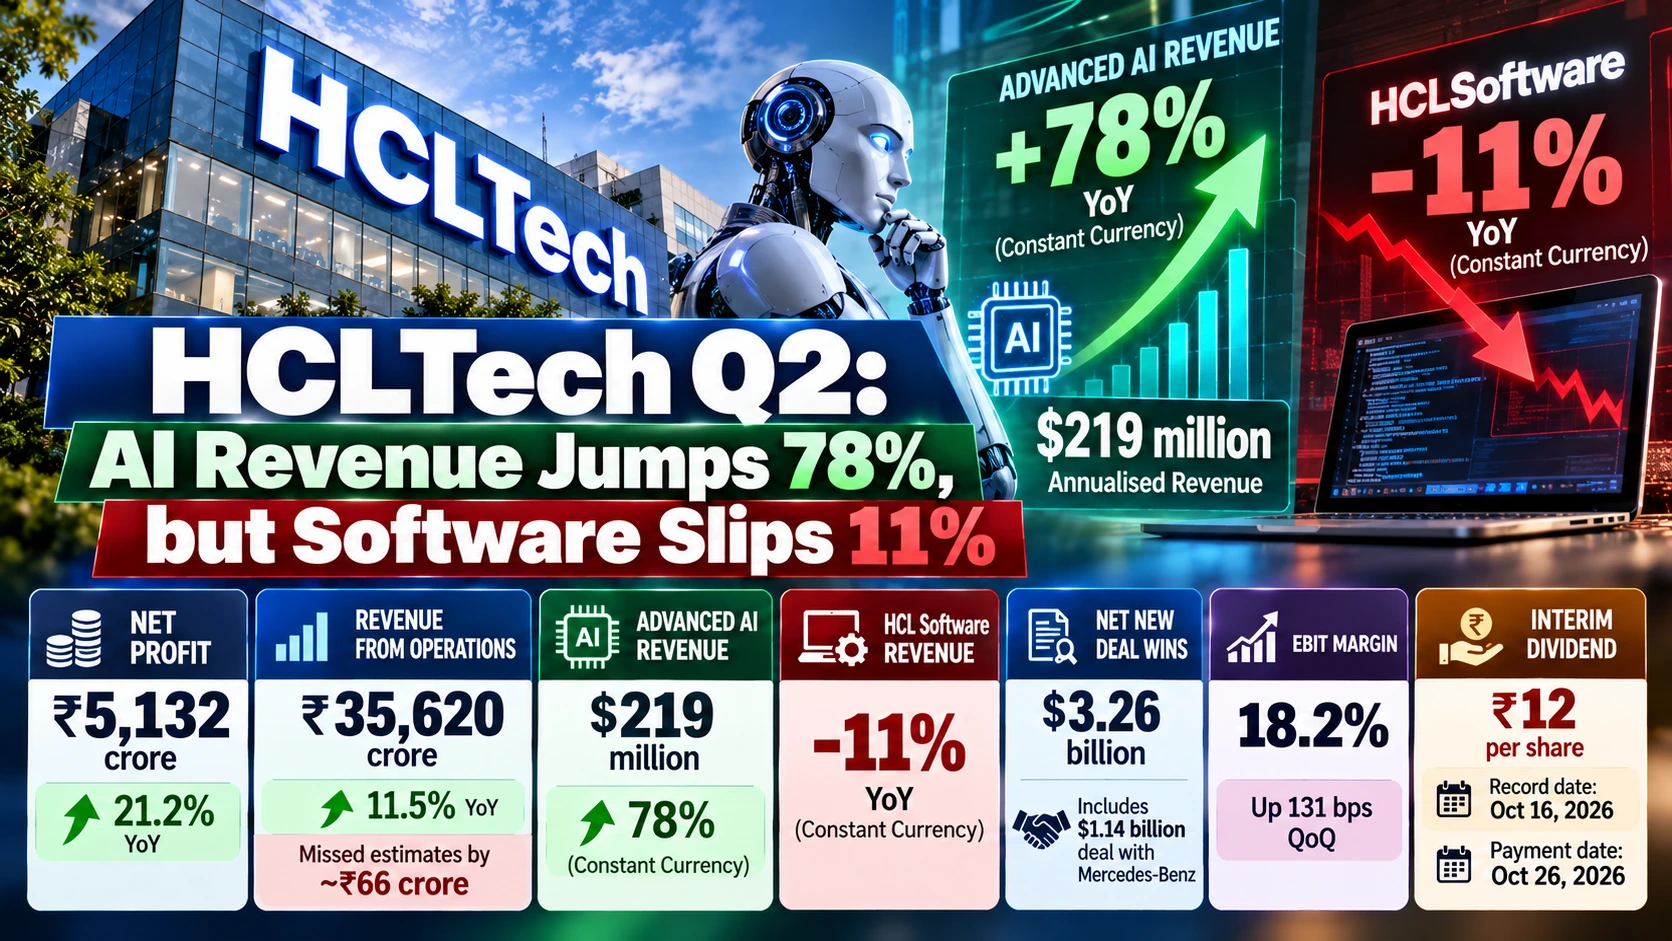
HCLTech’s Q2 FY27 net profit rose 21.2% to ₹5,132 crore, beating analyst expectations, while revenue narrowly missed estimates. Advanced AI revenue surged 78% year-on-year in constant-currency terms, but software weakness and changing IT billing models remain concerns.
HCLTech’s September-quarter results delivered a mixed signal for investors: strong profit growth and accelerating advanced AI revenue, alongside a slight revenue miss and pressure in its software business. Consolidated net profit climbed 21.2% year-on-year to ₹5,132 crore, while revenue from operations increased 11.5% to ₹35,620 crore.
The revenue figure came in approximately ₹66 crore below the ₹35,686 crore analyst consensus reported by Reuters. Net profit, however, exceeded the reported consensus of ₹4,859 crore by approximately ₹273 crore.
The company also raised the lower end of its FY27 revenue-growth guidance, retained its EBIT margin range and declared a second interim dividend of ₹12 per share.
The key question is whether AI-led demand and new contract wins can translate into sustained revenue growth as clients rethink traditional IT services spending and billing models.
HCLTech Q2 FY27 results: Key numbers
| Metric | Q2 FY27 |
|---|---|
| Consolidated net profit | ₹5,132 crore |
| Net profit growth YoY | 21.2% |
| Revenue from operations | ₹35,620 crore |
| Revenue growth YoY | 11.5% |
| Revenue growth QoQ | 3.0% |
| Revenue growth YoY, constant currency | 2.6% |
| EBIT margin | 18.2% |
| Annualised advanced AI revenue | $219 million |
| Advanced AI revenue growth YoY, constant currency | 78% |
| Net new deal wins | $3.26 billion |
| Second interim dividend | ₹12 per share |
Source: HCLTech Q2 FY27 results coverage by Reuters and The Economic Times. Figures are rounded where indicated.
Track Live: HCL TECHNOLOGIES Option Chain (NSE) — Live OI, PCR & Greeks
1. HCLTech’s profit beats estimates, but revenue misses
HCLTech’s consolidated net profit rose from ₹4,235 crore in the year-ago quarter to ₹5,132 crore in Q2 FY27. Revenue from operations increased from approximately ₹31,942 crore to ₹35,620 crore.
Sequentially, revenue grew 3%, while net profit increased 11%. In constant-currency terms, revenue advanced 2.3% quarter-on-quarter and 2.6% year-on-year.
The difference between profit and revenue performance is important. The profit beat signals stronger earnings than analysts expected, but the revenue miss suggests that growth remains challenging despite the improvement in reported earnings.
HCLTech reported an EBIT margin of 18.2%. Investors should track subsequent margin disclosures alongside revenue growth, particularly as the company expands its AI-related services and navigates changes in client spending.
2. Advanced AI revenue jumps 78%: Can the momentum continue?
HCLTech’s annualised advanced AI revenue reached $219 million, up 78% year-on-year in constant-currency terms, according to its reported results. Reuters also reported that the figure rose from $171 million in the preceding quarter.
The expansion underlines the opportunity created by enterprise AI adoption, including AI-led transformation, automation and the development of AI agents.
However, strong growth in one business area does not automatically translate into equivalent growth across the company. HCLTech’s total revenue grew 2.6% year-on-year in constant-currency terms, far below the reported growth rate of advanced AI revenue.
The next test is whether AI-related demand converts into sustained, recognised revenue and profitable client engagements. Investors will also need to track the contribution of AI-related work to the wider services business rather than relying on the headline growth rate alone.
3. Software weakness and changing billing models remain risks
Software performance is an important counterpoint to HCLTech’s AI growth story. The Economic Times reported that HCL Software revenue declined 11% year-on-year and 5.8% sequentially in constant-currency terms, even as its EBIT margin improved to 20.1% from 17.6% in the preceding quarter.
The segment figures should be checked against the official Q2 investor release before publication.
Separately, Reuters reported that clients are increasingly shifting towards outcome-based billing, in which payments are linked to results rather than hours worked. This is creating pressure on traditional revenue models across India’s IT services industry.
That creates a longer-term challenge for technology providers: AI can open new revenue streams while also changing how existing services are priced. HCLTech’s ability to convert AI demand into growth across its wider business will therefore be an important indicator to watch.
4. HCLTech revises FY27 revenue-growth guidance
HCLTech raised the lower end of its FY27 constant-currency revenue-growth guidance for the overall company from 1% to 2.5%, while retaining the upper end at 4%.
Its services revenue-growth range narrowed to 3%–4% from 1.5%–4.5%. The EBIT margin guidance remained unchanged at 17.5%–18.5%.
| FY27 guidance | Previous range | Updated range |
|---|---|---|
| Company revenue growth, constant currency | 1%–4% | 2.5%–4% |
| Services revenue growth, constant currency | 1.5%–4.5% | 3%–4% |
| EBIT margin | 17.5%–18.5% | 17.5%–18.5% |
The higher minimum revenue-growth expectation is a positive development. However, the narrower services range should not be described as an across-the-board increase in guidance.
Investors will watch whether AI demand, services momentum and new contracts support delivery within the updated ranges, particularly if traditional software revenue remains under pressure.
Also Check: HCL TECHNOLOGIES Options Chart | Nifty Trader
5. Deal wins offer support, but conversion matters
HCLTech reported net new deal wins of $3.26 billion, compared with $2.4 billion in the preceding quarter and $2.57 billion in the year-ago quarter, according to Reuters.
The current-quarter figure included a $1.14 billion Mercedes-Benz contract.
Strong bookings provide a potential source of future business, but contracts do not convert immediately into recognised revenue. Project execution, client spending schedules and the timing of new engagements will affect how quickly bookings contribute to reported growth.
The next quarter will help show whether the stronger pipeline translates into sustained company-wide revenue expansion.
6. ₹12 interim dividend: Record date and payment date
HCLTech declared a second interim dividend of ₹12 per equity share for FY27.
- Record date: October 16, 2026
- Payment date: October 26, 2026
- Dividend amount: ₹12 per share
Eligible shareholders should confirm their entitlement and corporate-action details through the official company and stock-exchange disclosures.
What should investors watch after HCLTech Q2?
HCLTech’s Q2 results combine robust profit growth, accelerating advanced AI revenue and stronger deal wins with a slight revenue miss and uncertainty around traditional IT services economics.
The higher revenue-growth floor is encouraging, but investors will need to monitor revenue conversion, software performance, services demand and delivery against the revised FY27 guidance.
The central takeaway is that AI represents a growth opportunity, but the durability of that growth across HCLTech’s wider business remains unproven. The quarterly result alone cannot determine the stock’s next move; valuation, market expectations and subsequent results also matter.
Read Next: Reliance’s Venezuelan Oil Bet Could Unlock ₹12,600 Crore—If Discounts Hold
Frequently asked questions
1. What was HCLTech’s Q2 FY27 net profit?
HCLTech reported consolidated net profit of ₹5,132 crore, up 21.2% year-on-year.
2. Did HCLTech beat revenue estimates?
No. Revenue reached ₹35,620 crore, approximately ₹66 crore below the ₹35,686 crore analyst consensus reported by Reuters. Net profit exceeded the reported analyst estimate.
3. How fast did advanced AI revenue grow?
Annualised advanced AI revenue reached $219 million, with reported year-on-year growth of 78% in constant-currency terms.
4. What changed in HCLTech’s FY27 guidance?
The company raised the lower end of its revenue-growth guidance to 2.5% from 1%, retained the 4% upper end and narrowed services growth guidance to 3%–4%. EBIT margin guidance remained at 17.5%–18.5%.
5. What dividend did HCLTech declare?
The company declared a second interim dividend of ₹12 per share. October 16, 2026, is the record date, and October 26, 2026, is the payment date.
Disclaimer: This article is for informational and educational purposes only and is not investment advice. Business guidance is subject to risks and uncertainties, and actual performance may differ from expectations.