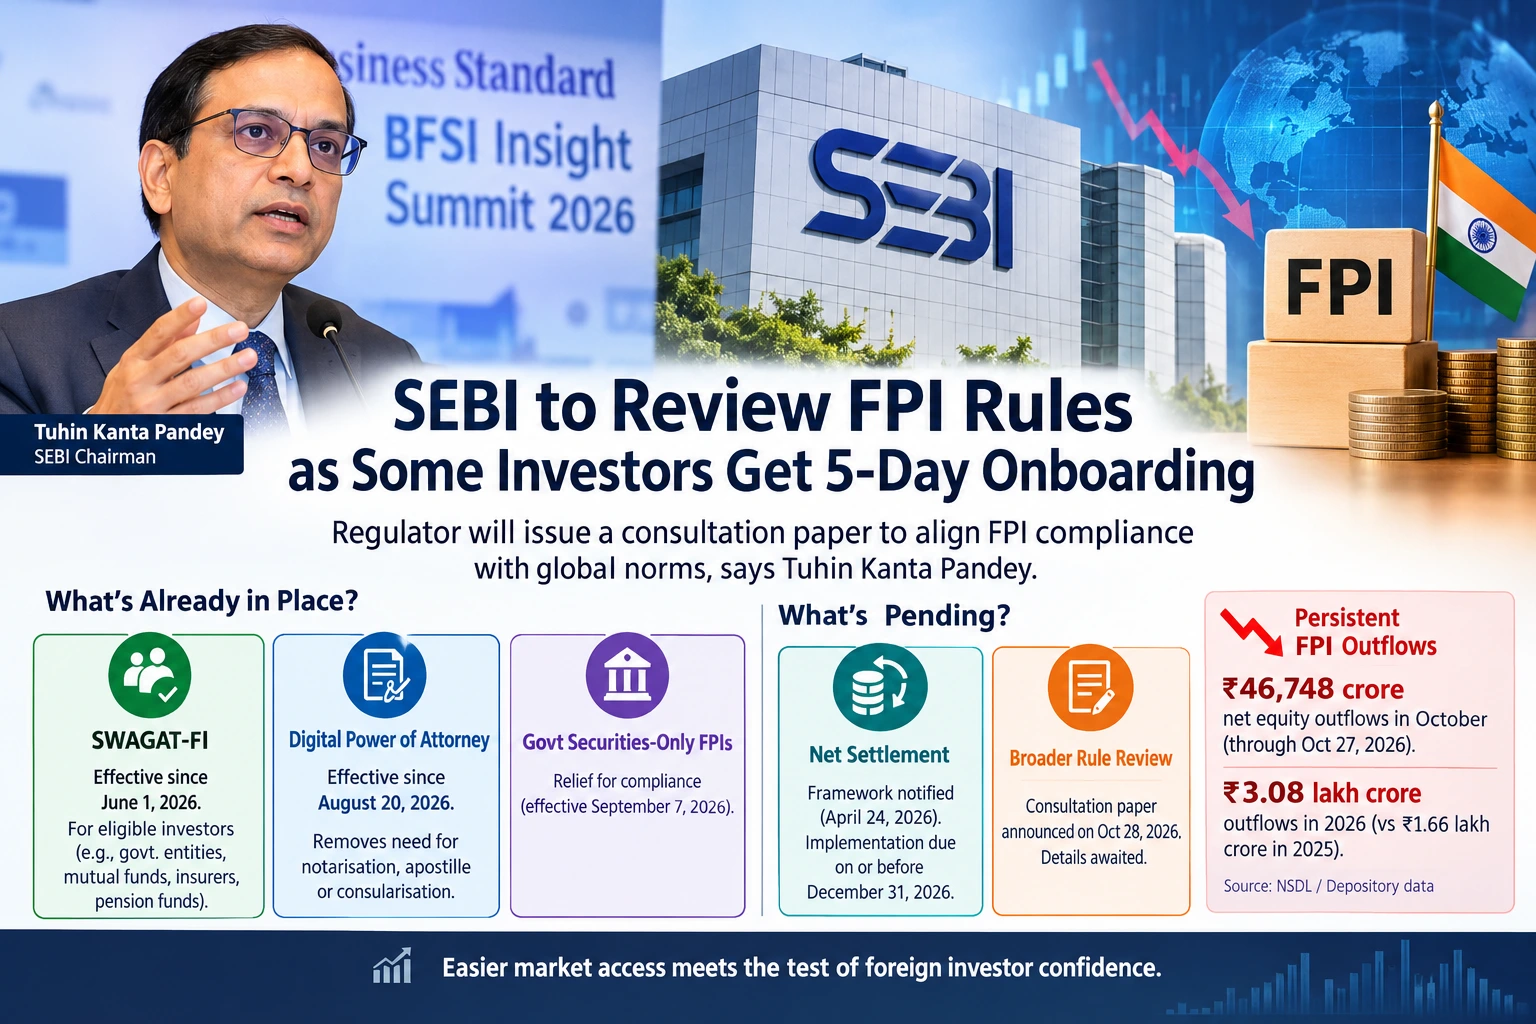
SEBI will review compliance requirements for foreign portfolio investors (FPIs) and issue a consultation paper seeking feedback on aligning Indian rules with global standards, Chairman Tuhin Kanta Pandey said on Wednesday, October 28. The announcement came at the Business Standard BFSI Insight Summit 2026 in Mumbai, as the regulator acknowledged that some Indian requirements remain more onerous than those in other major markets.
The review comes as foreign investors continue to withdraw substantial amounts from Indian equities. The latest available depository-based tracking series, updated on October 28 with data through October 27, showed net FPI equity outflows of ₹46,748 crore for October so far. The consultation could address operational barriers, but the extent of any relief remains uncertain because the proposed changes have not yet been specified.
SEBI has already introduced targeted measures to simplify onboarding, documentation and settlement. The new consultation process is expected to examine whether further requirements can be streamlined without weakening investor protection or market integrity.
Track Live : NSE Option Chain — Live
SEBI’s FPI Reforms: What Is Effective and What Is Pending?
SEBI’s initiatives are at different stages. The distinction matters because some changes are already effective, another framework has a year-end implementation deadline, and the broader compliance review is still awaiting its consultation paper.
| Initiative | Status as of October 28, 2026 |
|---|---|
| SWAGAT-FI framework | Effective since June 1, 2026, for eligible investors |
| Digitally signed powers of attorney | Effective since August 20, 2026 |
| Compliance relief for government-securities-only FPIs | Circular issued on September 7, 2026 |
| Net settlement of eligible FPI cash-market fund obligations | Framework notified; implementation due on or before December 31, 2026 |
| Broader review of FPI compliance rules | Consultation paper announced; detailed proposals awaited |
The status of these measures is based on SEBI’s official circulars and announcements. The proposed consultation paper is a separate development and should not be confused with changes already introduced.
FPI Outflows Add Urgency to SEBI’s Review
The regulatory review comes amid sustained foreign selling, although the latest figures vary according to the reporting date and data series.
An October 25 report by NDTV Profit, citing depository data, put net FPI equity outflows at ₹48,056 crore for October at that point. Cumulative withdrawals during 2026 had reached ₹3.08 lakh crore, compared with ₹1.66 lakh crore withdrawn during the whole of 2025.
The later depository-based tracking series, updated on October 28 with data through October 27, showed October net equity outflows of ₹46,748 crore. The updated figure reflects subsequent trading sessions and should be used instead of the older monthly snapshot when reporting the latest available position.
The figures indicate that foreign equity outflows remained substantial even as targeted compliance reforms came into effect. However, the relationship is not necessarily direct: regulatory paperwork is only one factor in the decision to allocate capital to a market.
At the summit, Pandey identified earnings growth, post-tax returns in dollar terms, currency movements and oil prices among the factors influencing foreign investment decisions. Global market opportunities and relative valuations also affect where international investors deploy capital.
For Indian markets, the expectation gap is clear. Easier access can reduce administrative friction, but it cannot guarantee that overseas investors will increase their equity allocations.
SWAGAT-FI: Why Five-Day Registration Is Not Available to Every FPI
SEBI introduced the Single Window Automatic and Generalised Access for Trusted Foreign Investors (SWAGAT-FI) framework through circulars dated January 16, 2026. Its provisions became effective on June 1, 2026.
The framework is intended to simplify registration and ongoing compliance for eligible FPIs and foreign venture capital investors. Eligible categories include central banks, sovereign wealth funds, appropriately regulated and broad-based mutual funds, insurance companies and pension funds that meet the applicable criteria.
Under SWAGAT-FI, eligible investors can benefit from a unified registration process across multiple investment routes and reduced duplication of documentation and compliance requirements.
Pandey said at the October 28 summit that some FPIs had completed registration in as little as five days under the framework. That experience is an indication of what streamlined procedures can achieve for qualifying applicants, not a guaranteed processing time for every foreign investor.
SEBI has also introduced a common application form covering registration, PAN, bank accounts and demat accounts. This reduces the need for investors to navigate separate procedures for related onboarding requirements.
The framework therefore addresses specific administrative barriers, but its benefits depend on investor eligibility and compliance with the applicable conditions.
Digital Power of Attorney Removes Additional Documentation Steps
SEBI permitted FPIs to submit digitally signed powers of attorney to their custodians through a circular dated August 20, 2026. The provision took effect on the same date.
The change removes the need for notarisation, apostillisation or consularisation of a power of attorney executed using a digital signature in accordance with the Information Technology Act, 2000.
The reform is aimed at reducing documentation-related delays during FPI onboarding. It is an existing change, rather than a proposal awaiting the new consultation paper.
In a separate measure dated September 7, SEBI also eased regulatory compliance for FPIs investing exclusively in government securities. That relief is targeted at a specific investor category and should not be interpreted as a blanket exemption for equity-market FPIs.
Net Settlement: What Changes by December 31?
SEBI notified its framework for net settlement of funds for eligible FPI cash-market transactions on April 24, 2026. The measure is intended to reduce funding requirements and improve the efficiency of foreign investors’ cash management.
The scope is specific. The framework covers outright purchase-only or sale-only transactions in a security during a settlement cycle. Transactions involving both purchases and sales in the same security during that cycle are excluded from netting and continue under the existing gross-settlement process.
The distinction between funds and securities is important. Although eligible fund obligations can be netted, securities settlement between the FPI and its custodian continues on a gross basis. Securities transaction tax (STT) and stamp duty also continue to be charged on a delivery basis.
Pandey referred to implementation in December at the summit. SEBI’s April 24 circular sets a formal deadline of on or before December 31, 2026.
As of October 28, this framework should be described as notified with implementation pending, unless subsequent official confirmation establishes that it has already become operational. It is not part of the broader consultation proposal announced on October 28.
Government’s LTCG and STT Review Is a Separate Development
The debate over foreign investor costs also extends beyond SEBI’s compliance rules.
The Economic Times reported on October 27 that the government had sought views from investors, market participants and tax experts on long-term capital gains (LTCG) tax and STT amid foreign portfolio investment outflows.
According to the report, the discussions concern the competitiveness of India’s capital-market tax framework and the combined burden of capital-gains tax and transaction levies. The development was reported separately from SEBI’s consultation announcement.
No tax reduction should be assumed from this report. Any change would require a separate policy decision, and the government would also need to consider the potential revenue implications.
The distinction matters because onboarding requirements, settlement processes and taxation affect different parts of an investor’s experience. Reducing administrative friction may make participation easier, but the final investment decision also depends on expected returns, currency exposure, market valuations and the availability of competing opportunities.
The reported tax discussions provide additional context for India’s efforts to attract overseas capital. They do not establish that the forthcoming SEBI consultation paper will cover LTCG or STT.
India’s Capital Markets Continue to Expand
Pandey cited the growth of India’s capital markets while discussing the next phase of market development.
According to figures he shared at the summit, India’s market capitalisation-to-GDP ratio rose from 69% in FY2016 to around 130% currently. Outstanding corporate bonds reached nearly ₹61 lakh crore, equivalent to approximately 55% of bank credit to industry and services.
These figures highlight the expanding role of securities markets in corporate financing. The regulatory challenge is to make participation more efficient while maintaining transparency, effective supervision and investor confidence.
For foreign investors, the practical impact of reforms will depend on how much time, documentation and funding friction they actually remove. For the regulator, the challenge is to simplify processes without compromising the safeguards that support orderly markets.
What Happens Next for FPI Rules?
The next milestone is the consultation paper announced by Pandey. Its publication should identify the requirements under review and allow market participants to submit feedback on possible changes.
Until those proposals are available, the scope of further simplification and the timeline for any final amendments remain uncertain. Existing compliance requirements continue to apply unless SEBI formally changes them.
Bottom Line: SEBI’s planned review adds to a series of reforms targeting foreign investor onboarding and operational costs. SWAGAT-FI and digitally signed powers of attorney are already effective, while eligible cash-market fund netting has a December 31 implementation deadline. With foreign equity outflows still substantial, the broader test will be whether further simplification improves the ease of investing in India without weakening investor protection or market integrity.
Track institutional flows: Follow daily foreign and domestic investor activity through the NiftyTrader FII-DII Tracker.
Read Next: F&O Buildup October 28: 81 Long Signals, 77 Shorts as Nifty Futures Weaken
Disclaimer: This article is for informational purposes only and does not constitute investment advice. Regulatory requirements and FPI flow figures may change; readers should refer to official SEBI circulars and the latest depository data for updates.