Need to Know
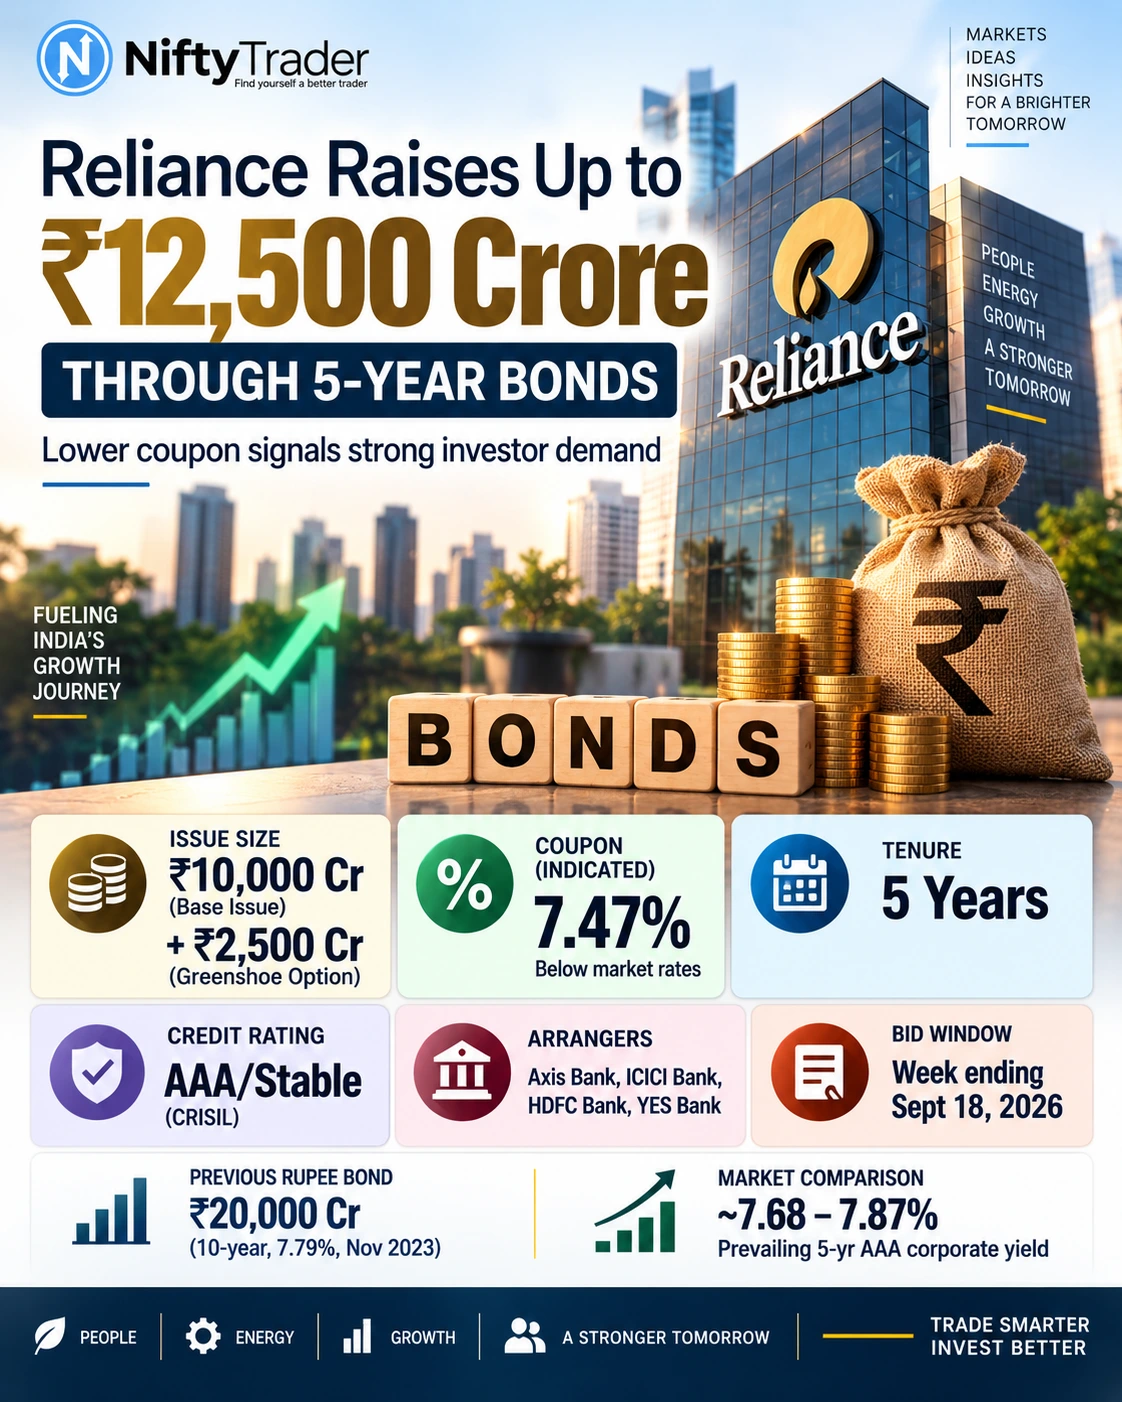
- Reliance Industries is raising up to ₹12,500 crore through five-year, AAA-rated bonds, a ₹10,000 crore base issue plus a ₹2,500 crore greenshoe option.
- The indicated coupon is 7.47%, below the ~7.68–7.87% range prevailing on comparable top-rated five-year corporate paper, per banker estimates cited by Reuters and Bloomberg.
- Axis Bank, ICICI Bank, HDFC Bank and YES Bank are arranging the sale; bids are expected in the week ending September 18, 2026.
- It’s RIL’s first rupee bond sale since a ₹20,000 crore, 10-year issue in November 2023 that drew heavy participation from LIC. This time, people familiar with the deal say LIC isn’t a significant investor.
- The timing coincides with a record $136.38 billion haul under RBI’s special FCNR(B)/ECB/OFCB swap facility and India’s forex reserves hitting an all-time high of $785.71 billion.
- CRISIL has assigned AAA/Stable to a proposed ₹15,000 crore NCD programme, ₹2,500 crore more than what’s currently being placed, pointing to headroom for further issuance.
- Reliance has not filed a stock-exchange disclosure confirming final terms as of publication; figures below come from banker and people-familiar-with-the-matter reporting, cross-checked against rating-agency documents.
Check Live: Reliance Option Chain Live – RIL Options Data
A ₹12,500 Crore Headline That’s Actually Two Numbers
The ₹12,500 crore raise isn’t a single fixed number; it splits into a ₹10,000 crore base issue plus a ₹2,500 crore greenshoe, or over-allotment, option. Whether the final tally hits the full ₹12,500 crore depends on how much of that greenshoe gets exercised.
The five-year, AAA-rated notes carry an indicated coupon of 7.47%, according to bankers cited by Reuters and Bloomberg, and that number is more revealing than the headline size.
It sits below the 7.87% average yield that top-rated five-year corporate bonds were fetching just before the deal broke and roughly tracks a broader easing in AAA yields: five-year AAA PSU paper slipped from 7.85% on June 3 to 7.68% by September 7.
In plain terms, Reliance is pricing inside the benchmark, a sign of how much appetite there currently is for high-grade paper.
The Liquidity Wave Behind the Comeback
RIL’s last rupee bond sale was in November 2023: ₹20,000 crore at 7.79% for 10 years. Since then, corporate India has largely bypassed bonds in favour of cheaper bank loans.
What’s changed now is the sheer amount of money sitting inside the banking system. Between June and August, RBI’s special USD-INR swap facility, opened to cushion the rupee against West Asia-linked energy costs, pulled in $136.38 billion, with FCNR(B) deposits from NRIs alone accounting for $127.23 billion, well above the roughly $80–100 billion the scheme was originally expected to draw.
The window for fresh FCNR(B) deposits closed a month early, on August 31, because the response outran the timeline; ICICI Bank alone mobilised $17.88 billion.
That inflow fed straight into the number dominating this month’s macro headlines: India’s forex reserves jumped a record $44.9 billion in the week to September 4, to an all-time high of $785.71 billion, the tenth straight weekly rise, and enough to push India past Russia into fourth place globally.
Also Check: Reliance PCR, OI Chart & Options Data Live
Deal Snapshot
| Detail | Figure |
|---|---|
| Issue size | Up to ₹12,500 crore (₹10,000 cr base + ₹2,500 cr greenshoe) |
| Tenure | 5 years |
| Coupon (indicated) | 7.47% |
| Credit rating | CRISIL AAA/Stable; CARE AAA |
| Arrangers | Axis Bank, ICICI Bank, HDFC Bank, YES Bank |
| Bid window | Week ending September 18, 2026 |
| RIL’s previous rupee bond | ₹20,000 crore, 10-year, 7.79% coupon (Nov 2023) |
| Pre-deal benchmark | ~7.87% avg. 5-yr AAA corporate bond yield |
Where the Money Is Actually Going
The more useful question isn’t how much cash came in; it’s where it’s headed next. RBI data shows bank credit grew 19.1% year-on-year by end-August 2026, a decadal high, up from 10.3% a year earlier, while deposit growth accelerated to 17.8% from 9.8%. Outstanding bank credit stood near ₹224 lakh crore against deposits of ₹279 lakh crore.
Reliance’s bond sale is one visible channel for that deployment: the arranging banks are also expected to subscribe to part of the issue themselves, according to bankers cited by Reuters.
Jefferies pegs the resulting system liquidity surplus at close to ₹10 lakh crore, enough, it estimates, to trim banks’ funding costs by up to 50 basis points and add roughly ₹10,000–11,000 crore to sector-wide annual profit.
BofA’s estimate is more dramatic: it expects the FCNR-driven rise in base money to eventually support ₹25–40 lakh crore of what it calls “unencumbered credit creation”, equivalent to 7–11% of GDP, over the next two to three years.
That figure is a projection, not a booked outcome, and how much of it materialises depends on how fast banks find creditworthy borrowers, alongside external swing factors like crude prices and global bond yields.
Also Read: RBI’s ₹1 Lakh Crore Liquidity Drain: Bonds, Banks and Rates in Focus
The Liquidity Backdrop
| Metric | Figure |
|---|---|
| RBI swap facility, total inflows | $136.38 billion (by August 31, 2026) |
| — of which FCNR(B) deposits | $127.23 billion |
| India’s forex reserves | $785.71 billion (week ended Sept 4, 2026 — record) |
| Weekly reserve jump | +$44.9 billion (largest on record) |
| Bank credit growth, YoY | 19.1% (end-Aug 2026) vs. 10.3% a year earlier |
| Bank deposit growth, YoY | 17.8% vs. 9.8% a year earlier |
| Jefferies’ liquidity-surplus estimate | ~₹10 lakh crore |
| BofA’s credit-creation estimate | ₹25–40 lakh crore over 2–3 years (7–11% of GDP) |
Why LIC Sat This One Out
The clearest sign of how much the funding landscape has shifted is who isn’t in this deal. RIL’s 2023 issue was a 10-year bond that drew heavy demand from insurers and pension funds; market participants said at the time that a large state-run insurer alone took up roughly half of the ₹20,000 crore raised.
This time, with a shorter five-year tenor and banks flush with FCNR-linked liquidity, people familiar with the current transaction say LIC isn’t a significant investor.
It’s a small detail, but a telling one: when banks have this much cash to deploy, they can out-compete even a blue-chip issuer’s traditional anchor investors.
More Rating Headroom Than the Deal Size Suggests
CRISIL has assigned a ‘CRISIL AAA/Stable’ rating to RIL’s proposed non-convertible debentures, but the rated amount is ₹15,000 crore, ₹2,500 crore above the ₹12,500 crore currently being marketed.
CRISIL also reaffirmed its existing AAA/Stable/A1+ ratings on RIL’s outstanding debt and bank facilities, and CARE Ratings separately reaffirmed its own AAA rating.
The rationale points to RIL’s scale across oil-to-chemicals, telecom and retail, and its financial flexibility; the company posted its highest-ever quarterly recurring EBITDA of ₹54,067 crore in Q1 FY27, up about 10.1% year-on-year, even as net profit fell on a high base created by a one-off gain in the year-ago quarter.
The unused ₹2,500 crore of rated headroom leaves the door open for RIL to come back to the rupee market again without a fresh rating exercise.
The ₹12,500 Crore Question Investors Will Be Watching Next
Reliance’s bond return is not just about how much money it can raise. The bigger test is what this deal signals for India’s corporate borrowing market as banks sit on unusually high liquidity.
The first signal is pricing. At an indicated 7.47% coupon, Reliance is borrowing at a level that could become a useful reference point for other highly rated issuers considering the domestic bond market. Reuters has reported the five-year issue at 7.47%, while the current backdrop includes substantial banking liquidity following the RBI’s foreign-currency mobilisation measures.
The second signal is investor mix. LIC’s limited role in the current five-year deal, compared with its participation in Reliance’s earlier longer-maturity issue, highlights how banks and traditional long-term investors may be approaching corporate bonds differently this time. That shift could become more important if other large borrowers follow Reliance back into the market.
The third, and more uncertain, question is whether this liquidity translates into cheaper funding across corporate India. Banks have multiple avenues for deployment, including loans and corporate bonds, but stronger competition for high-quality borrowers could also put pressure on lending spreads.
That makes Reliance’s ₹12,500-crore deal a market signal worth watching beyond September 18: will it remain a one-off large-company fundraise or become an early indicator of a broader return to domestic corporate bonds?
Investor Watch
The key monitorables now are the final issue size, actual demand, the final pricing achieved and whether other AAA-rated companies begin testing similar funding levels. The answer could reveal whether India’s current liquidity surplus is merely temporary or the start of a broader shift in corporate funding conditions.
Read Next: US House Blocks India Tariff Bid: The 100% Threat Takes a Twist
Disclaimer: This article is for informational purposes only and does not constitute investment advice, a recommendation or a solicitation to buy or sell any security. Bond pricing, demand and liquidity conditions can change, and reported transaction details may be subject to final confirmation by the issuer or arrangers.