Reliance Q2 FY27 Results on Oct 30: Rs 20,900 Crore Profit Seen, Retail the Weak Link
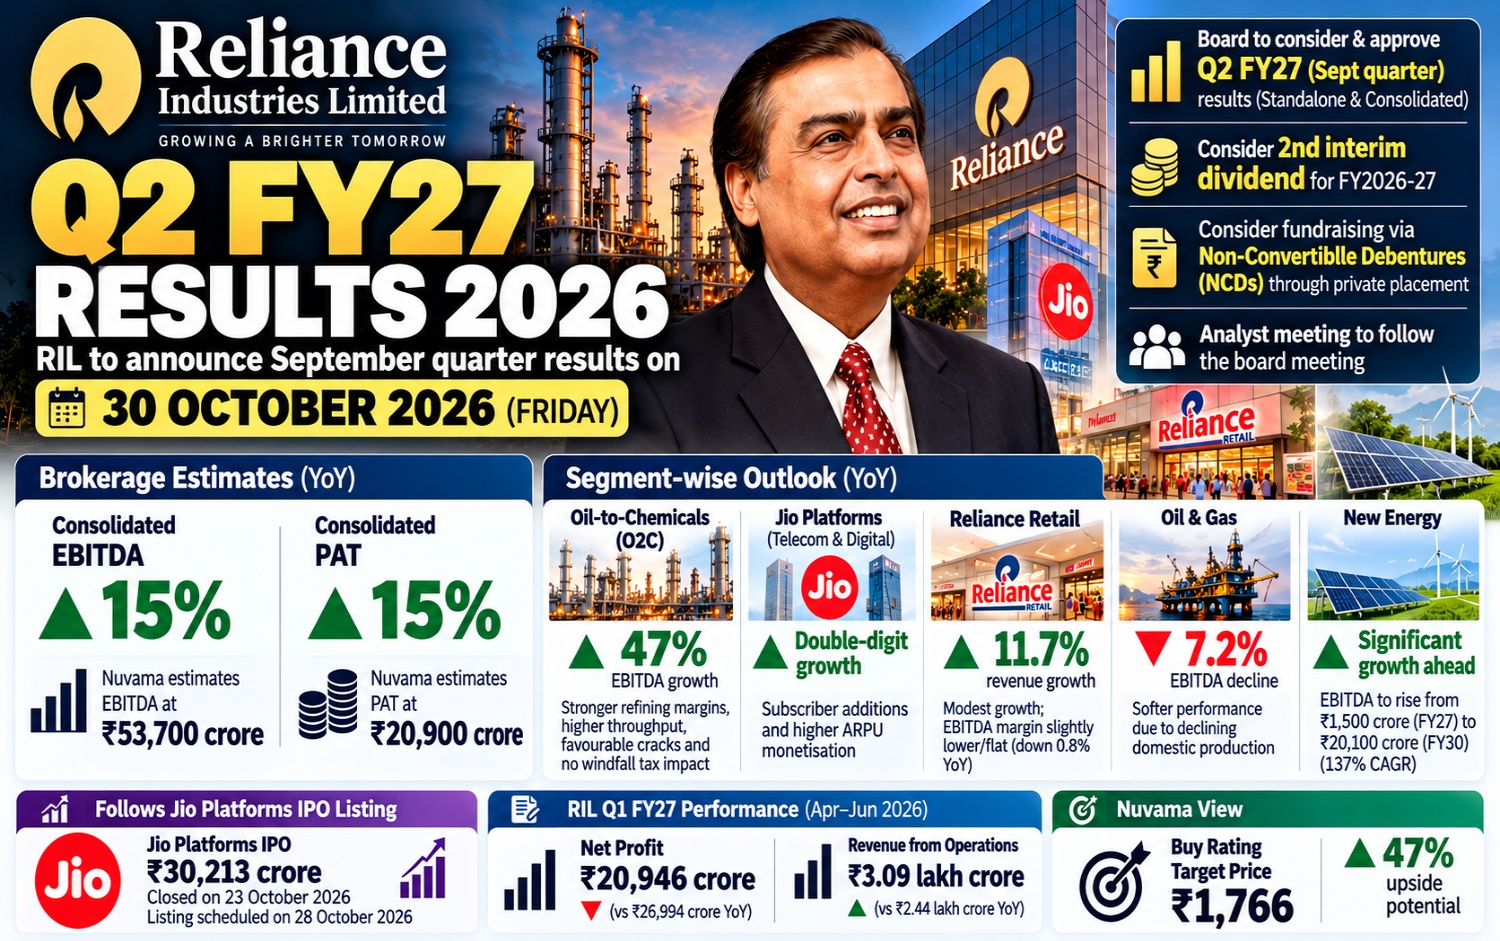
Reliance Industries Limited (RIL), led by Mukesh Ambani, is scheduled to announce its September-quarter results on Friday, October 30, 2026. Investors will be watching closely to see whether stronger refining margins and telecom growth can offset weaker performance in some business segments.
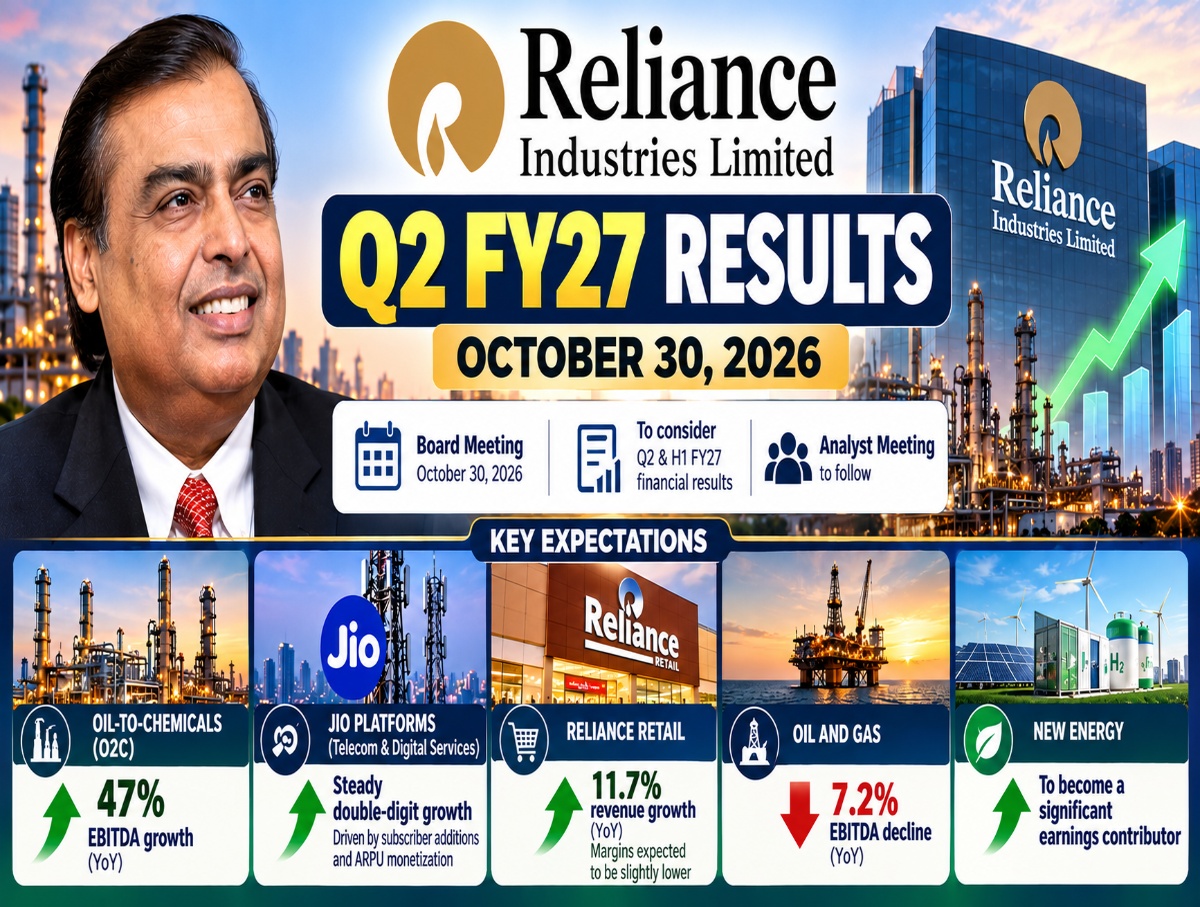
According to the company’s regulatory filing dated October 27, the board will consider the standalone and consolidated unaudited financial results for the quarter and half-year ended September 30, 2026.
Reliance has not specified the exact time of the announcement. An analyst meeting is scheduled to follow the board meeting, providing an opportunity to discuss financial performance and business updates.
The board will also consider raising funds through non-convertible debentures (NCDs) on a private-placement basis, potentially in one or more tranches.
Track Live : Nifty Levels Today | Sensex Levels Today
Why Analysts Expect Stronger Reliance Q2 FY27 Results Earnings
Brokerage estimates point to improved profitability, supported primarily by the oil-to-chemicals (O2C) business.
Nuvama Research expects consolidated EBITDA to increase 17% year-on-year to ₹53,700 crore, while profit after tax (PAT) is projected to rise 15% to ₹20,900 crore.
Kotak Institutional Equities has also projected consolidated EBITDA growth of around 15% year-on-year and 11.1% quarter-on-quarter.
These figures are forecasts, not confirmed results. The actual performance will depend on refining margins, production volumes, operating costs and the contribution of individual business segments.
Official results date, board agenda and analyst meeting
Reliance Industries confirmed in its October 27 regulatory filing that its board would meet on Friday, October 30, 2026, to consider the unaudited standalone and consolidated financial results for the quarter and half-year ended September 30, 2026. The board will also consider raising funds through non-convertible debentures (NCDs) via private placement. An analyst meeting will follow the board meeting.
| Key detail | Information |
|---|---|
| Results date | Friday, October 30, 2026 |
| Reporting period | Q2 FY27 and first half of FY27 |
| Exact results announcement time | Not specified in the cited filing |
| Analyst meeting | After the board meeting |
| Fundraising proposal | Listed, secured or unsecured, redeemable NCDs |
| Proposed fundraising amount | Not specified in the cited filing |
| Dividend announcement | No dividend proposal identified in the cited board-meeting notice |
Nuvama’s Q2 FY27 earnings estimates
Nuvama Research expects Reliance Industries to report stronger earnings, primarily driven by its oil-to-chemicals business and improved refining margins.
| Financial indicator | Nuvama estimate | Expected performance |
|---|---|---|
| Consolidated revenue | ₹2,92,437 crore | Up 14.9% YoY |
| Consolidated EBITDA | ₹53,700 crore | Up 17% YoY |
| Profit after tax (PAT) | ₹20,905–20,900 crore | Up approximately 15% YoY |
| O2C EBITDA | ₹20,700 crore | Up 38% YoY |
| Digital services EBITDA | Not specified in the cited report | Expected to benefit from ARPU growth and subscriber additions |
| Reliance Retail EBITDA | Not specified in the cited report | Expected to remain relatively weak |
| Oil and gas EBITDA | Not specified in the cited report | Expected to face pressure from lower production and gas realisations |
How the O2C Business Could Drive Reliance Industries’ Performance
Reliance’s O2C business is expected to be a major earnings driver during Q2 FY27.
Nuvama estimates that O2C EBITDA could rise 38% year-on-year to ₹20,700 crore. Improved refining margins, higher refinery throughput, stronger gasoil and aviation turbine fuel cracks, better gasoline cracks and inventory gains could support the segment.
Other brokerage estimates suggest an even sharper year-on-year improvement, highlighting the importance of refining performance to the overall earnings outlook.
Investors will also monitor the impact of the rupee’s weakness and the company’s petrochemical operations. However, fluctuations in global commodity prices and refining margins could affect the final numbers.
What Jio Platforms and Reliance Retail Could Contribute
Jio Platforms is expected to maintain growth through subscriber additions and average revenue per user (ARPU) improvements. Its digital services business has delivered strong growth in recent quarters, making telecom performance an important part of the RIL earnings outlook.
The results follow Jio Platforms’ ₹30,213 crore IPO, which closed on October 23, with its shares scheduled to list on October 28, 2026. Jio Platforms is also scheduled to announce its earnings on October 30.
Reliance Retail, meanwhile, could see more moderate growth. Estimates point to revenue growth of around 11.7% year-on-year, while EBITDA margins could remain under pressure.
The oil and gas segment is also expected to face challenges, with one estimate projecting EBITDA to decline 7.2% year-on-year because of weaker domestic production.
For the September quarter, investors should monitor:
-
Average revenue per user (ARPU).
-
Subscriber additions and customer retention.
-
Growth in digital services revenue and EBITDA.
-
Demand for home broadband and enterprise connectivity.
-
Management commentary on the relationship between Jio’s growth and Reliance Industries’ consolidated financial performance.
Track Live : NSE Option Chain — Live | BSE Option Chain — Live Sensex & Bankex Options Data Today
Reliance Retail and oil and gas could moderate growth
Despite expectations of stronger consolidated earnings, not every business is expected to perform equally well.
| Business | Key concern | Brokerage outlook |
|---|---|---|
| Reliance Retail | Revenue growth may not translate into comparable EBITDA growth | Nuvama expects EBITDA to decline around 1% YoY. |
| Oil and gas | Lower KG-D6 production and weaker gas realisations | Nuvama expects EBITDA to decline around 6% YoY. |
| O2C | Sustainability of improved refining margins | Expected to lead earnings growth. |
| Digital services | Subscriber monetisation and ARPU | Expected to support EBITDA growth. |
Why Reliance’s New Energy Business Is Drawing Investor Attention
Reliance’s longer-term investment story increasingly includes solar manufacturing, batteries, electrolysers, green hydrogen and renewable power.
Nuvama expects New Energy EBITDA to rise from ₹1,500 crore in FY27 to ₹20,100 crore in FY30. It also projects a turnaround in PAT, from a ₹300 crore loss to a ₹10,600 crore profit over the same period.
The company has commissioned 6 GW of module and 2 GW of cell manufacturing capacity and is developing an integrated 10 GW solar manufacturing facility, with plans to scale capacity further.
These projections depend on utilisation, execution, pricing and demand. Investors should distinguish the long-term opportunity from earnings already delivered.
Also Read : Coal India Q2 FY27 Results on Oct 29: Will a Second Payout Cushion a 31.6% Profit Drop?
Nuvama expects Reliance’s New Energy business to grow significantly as solar manufacturing, batteries, electrolysers, green hydrogen and renewable power projects scale up.
| New Energy indicator | Nuvama projection |
|---|---|
| FY27 EBITDA | ₹1,500 crore |
| FY30 EBITDA | ₹20,100 crore |
| Projected EBITDA CAGR | Approximately 137% |
| FY27 PAT | ₹300 crore loss |
| FY30 PAT | ₹10,600 crore profit |
Here’s What Happened Today and Why Traders Reacted
Reliance’s upcoming results have put its refining margins, Jio growth, retail profitability and New Energy investments in focus. However, the supplied information does not establish a specific share-price reaction to the earnings preview.
For traders, the key triggers will be actual EBITDA and PAT compared with estimates, management guidance, O2C margins and the NCD fundraising decision. The Jio Platforms listing may also influence sentiment around Reliance’s telecom and digital businesses.
What Reliance Industries Investors Should Watch Next
Reliance reported revenue from operations of ₹3.09 lakh crore in Q1 FY27, compared with ₹2.44 lakh crore a year earlier. Consolidated net profit was ₹20,946 crore, against ₹26,994 crore in the corresponding year-ago quarter. The earlier period included a one-off gain of ₹8,924 crore from the sale of its stake in Asian Paints.
Nuvama has retained its Buy rating with a target price of ₹1,766, based on its sum-of-the-parts valuation. This is a brokerage estimate, not a guaranteed return or a prediction of where the stock will trade.
-
Consolidated EBITDA compared with the ₹53,700 crore estimate.
-
PAT compared with the approximately ₹20,900 crore estimate.
-
O2C EBITDA and refining-margin commentary.
-
Jio Platforms’ ARPU and digital services performance.
-
Reliance Retail’s EBITDA margin and revenue growth.
-
Oil and gas production and realisations.
-
The board’s decision on NCD fundraising and the proposed terms, if approved.
-
Management’s updates on New Energy investment and project execution.