Hindalco Q2 Results FY27: Why November 6 Is Important for Investors
Hindalco Industries is approaching an important earnings trigger, with investors closely watching whether the aluminium and copper major can maintain its strong financial performance after delivering record earnings in Q1 FY27.
The company is scheduled to announce its September-quarter results on Friday, November 6, 2026. The board meeting will consider the unaudited financial results for the second quarter and first half of FY27.
Hindalco has also scheduled its Q2 earnings conference call for 4:30 PM IST on the same day.
The biggest question for investors is whether strong domestic operations and an improving performance from its US subsidiary, Novelis, can support another healthy quarter.
Track Live : Results Calendar — NSE & BSE
Hindalco Q2 Results FY27: 6 November Date, Earnings Expectations, Novelis Outlook and Key Numbers
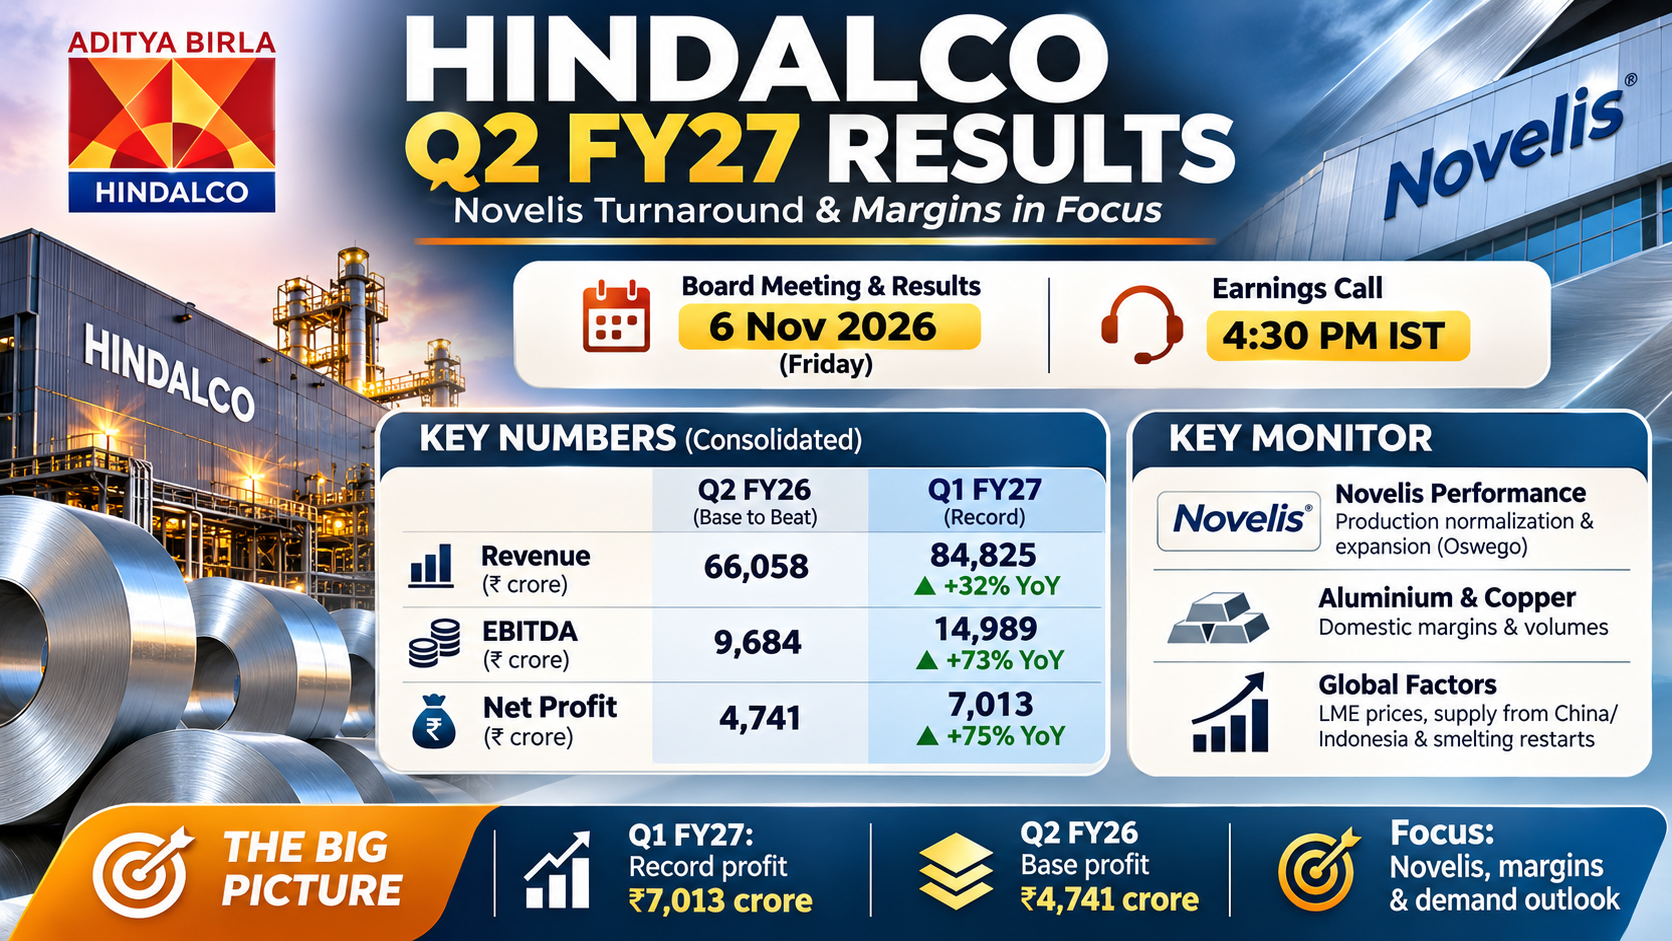
Hindalco Industries is scheduled to announce its Q2 FY27 financial results on Friday, November 6, 2026, with investors closely tracking its aluminium and copper businesses, subsidiary Novelis and the company’s operating margins.
The September-quarter earnings will be important because Hindalco is entering the results season after delivering record consolidated revenue, EBITDA and net profit in Q1 FY27.
| Particulars | Details |
|---|---|
| Company | Hindalco Industries Ltd |
| Results | Q2 FY27 |
| Board meeting date | Friday, 6 November 2026 |
| Earnings call | 6 November 2026, 4:30 PM IST |
| Reporting period | July–September 2026 |
| Q2 FY26 revenue | ₹66,058 crore |
| Q2 FY26 EBITDA | ₹9,684 crore |
| Q2 FY26 net profit | ₹4,741 crore |
| Q2 FY26 EPS | ₹21.35 |
| Q1 FY27 revenue | ₹84,825 crore |
| Q1 FY27 EBITDA | ₹14,989 crore |
| Q1 FY27 net profit | ₹7,013 crore |
| Q1 FY27 EPS | ₹31.58 |
| Novelis results | Expected November 5, 2026 |
| Q2 FY27 analyst consensus | Not independently verified |
Hindalco Q2 Results : Can Hindalco Repeat Its Record Q1 FY27 Performance?
The earnings bar is relatively high after Hindalco delivered its strongest-ever quarterly performance in Q1 FY27.
The company reported consolidated revenue of ₹84,825 crore and net profit of ₹7,013 crore, representing increases of 32% and 75%, respectively, year-on-year.
The supplied figures include two different Q1 EBITDA numbers: ₹14,989 crore and ₹13,932 crore. Investors should check the company’s official results presentation for the correct comparable reporting basis.
No confirmed analyst consensus estimate for Q2 FY27 was available as of October 31, 2026. For comparison, market expectations for Q1 FY27 were around ₹5,817 crore in profit, against the actual ₹7,013 crore.
| Consolidated financial metric | Q2 FY26 | YoY growth |
|---|---|---|
| Revenue from operations | ₹66,058 crore | +13% |
| EBITDA | ₹9,684 crore* | +6% |
| Net profit | ₹4,741 crore | +21% |
Historical financial comparison
| Metric | Q2 FY26 | Q1 FY27 |
|---|---|---|
| Revenue | ₹66,058 cr | ₹84,825 cr |
| EBITDA | ₹9,684 cr | ₹14,989 cr |
| Net profit | ₹4,741 cr | ₹7,013 cr |
| EPS | ₹21.35 | ₹31.58 |
Novelis Q2 FY27 results on November 5: Why Hindalco investors should watch closely
Novelis, Hindalco’s US-based subsidiary and a major global aluminium rolling and recycling business, is scheduled to announce its Q2 FY27 results on Thursday, November 5, 2026.
Its earnings conference call is scheduled for 5:30 PM IST.
This is particularly important because Novelis’ operating performance has a significant influence on Hindalco’s consolidated financial results.
-
Oswego hot-mill recovery: Production restarted in June 2026 and was ramping up during Q1.
-
Bay Minette expansion: Commissioning was underway, with commercial shipments expected in Q1 FY28.
-
Cost optimisation: Continued cost reduction initiatives are expected to support operating profitability.
-
EBITDA per tonne: Investors will watch whether Novelis can sustain its improved profitability per tonne.
-
Shipment volumes: Recovery in production and shipments will be important for revenue growth.
In Q1 FY27, Novelis reported adjusted EBITDA of $516 million, up 24% year-on-year, while EBITDA per tonne reached $563. Shipments stood at 916 kilotonnes.
The November 5 earnings announcement could therefore provide an early indication of how Novelis performed before Hindalco publishes its consolidated results the following day.
Q1 FY27 record performance: The benchmark Hindalco must follow
Hindalco delivered its strongest-ever quarterly performance in Q1 FY27, setting a high benchmark for the September quarter.
| Consolidated financial metric | Q1 FY27 | YoY growth |
|---|---|---|
| Revenue from operations | ₹84,825 crore | +32% |
| EBITDA | ₹14,989 crore | +73% |
| Net profit | ₹7,013 crore | +75% |
| EPS | ₹31.58 | +75% |
The company’s performance was supported by strong aluminium realisations, higher operating efficiency and improving profitability at Novelis.
However, Q1 FY27 also included an exceptional expense of ₹2,299 crore, which investors should consider when comparing reported profit across quarters.
Track Live : Nifty Levels Today | Sensex Levels Today
Aluminium and Copper Margins Could Support Earnings Growth
Hindalco’s domestic aluminium and copper operations remain important earnings drivers.
Analysts have highlighted the company’s ability to maintain strong EBITDA per tonne despite monsoon-related challenges and traditionally higher coal costs.
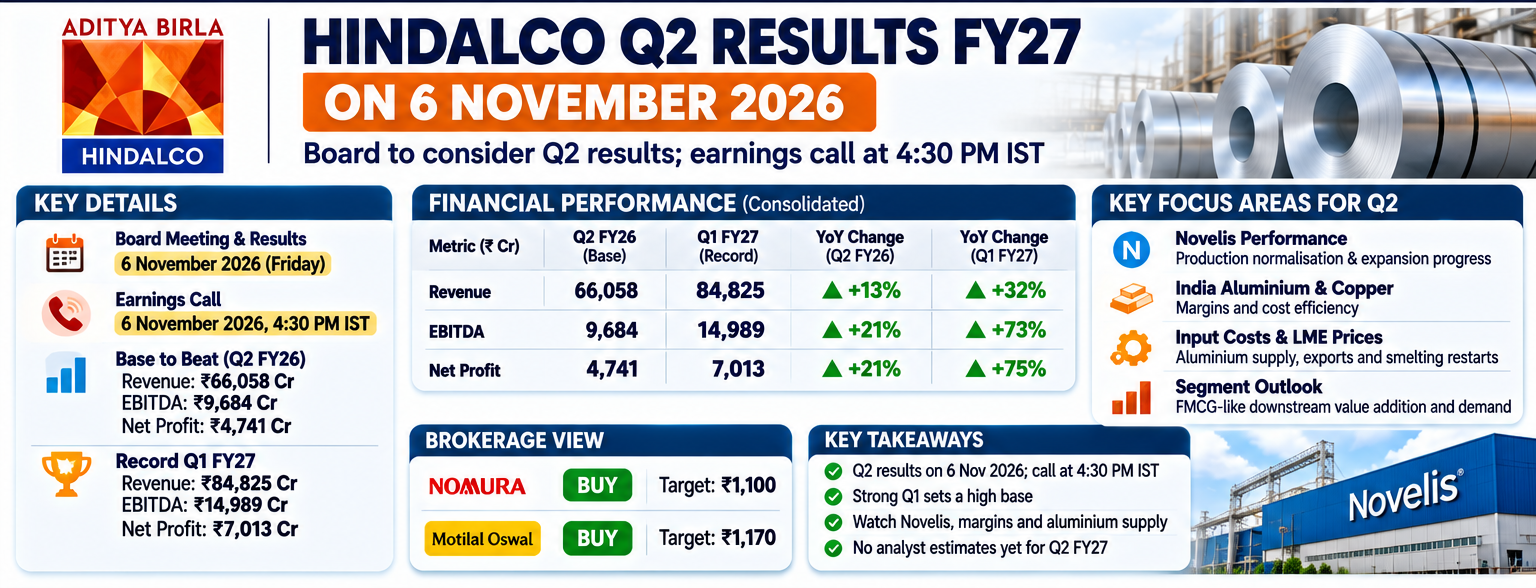
Brokerages Nomura and Motilal Oswal have maintained positive views, with respective Buy target prices of ₹1,100 and ₹1,170.
However, investors should also monitor aluminium supply conditions. Rising exports from China and Indonesia, along with additional smelting capacity restarts, could create pressure on aluminium prices and margins.
Track Live : NSE Option Chain — Live | BSE Option Chain — Live Sensex & Bankex Options Data Today
| Aluminium upstream indicator | Q1 FY27 |
|---|---|
| Revenue | ₹13,403 crore |
| EBITDA | ₹7,390 crore |
| Revenue growth | +44% |
| EBITDA growth | +81% |
| EBITDA margin | 55% |
| Shipments | 335 KT |
The company benefited from favourable aluminium prices, higher realisations and operational efficiencies.
Copper business: Another important earnings contributor
Hindalco’s copper business also reported record quarterly EBITDA in Q1 FY27.
| Copper business indicator | Q1 FY27 |
|---|---|
| Revenue | ₹17,232 crore |
| EBITDA | ₹918 crore |
| Revenue growth | +16% |
| EBITDA growth | +36% |
| Metal sales | 105 KT |
Despite planned major smelter maintenance, the company delivered strong profitability, supported by higher realisations from by-products such as sulphuric acid.
For Q2, investors should monitor copper treatment and refining charges (TC/RCs), smelter operations, production volumes and by-product realisations.
Read More : Capital Gains Tax Relief for Foreign Investors? What SEBI Has Proposed Before the Budget
Hindalco Q2 FY27 analyst estimates: What is the market expecting?
One important finding from the available research is that I could not verify a reliable, published consensus estimate for Hindalco’s Q2 FY27 revenue, EBITDA and net profit as of November 2, 2026.
| Financial metric | Q2 FY26 actual | Q1 FY27 actual |
|---|---|---|
| Revenue | ₹66,058 cr | ₹84,825 cr |
| EBITDA | ₹9,684 cr | ₹14,989 cr |
| Net profit | ₹4,741 cr | ₹7,013 cr |
These are historical actuals, not forecasts for Q2 FY27.
Why are three different EBITDA figures reported?
| Figure | What it represents |
|---|---|
| ₹9,684 crore | Consolidated EBITDA in Hindalco’s official Q2 FY26 results release |
| ₹9,104 crore | Business Segment EBITDA in the Q2 FY26 investor presentation |
| ₹8,966 crore | Not independently verified in the official Q2 FY26 documents reviewed |
The ₹9,684-crore and ₹9,104-crore figures are not interchangeable because the company reports different EBITDA measures.
For a results comparison, use ₹9,684 crore as the headline EBITDA from the official financial release and clearly label ₹9,104 crore as business segment EBITDA when discussing the investor presentation. Do not use ₹8,966 crore without identifying its source and calculation basis.
What Should Traders and Investors Watch Before November 6?
For traders, Hindalco’s Q2 results could trigger volatility depending on profitability, management commentary and Novelis’ recovery.
Long-term investors should focus on consolidated EBITDA, domestic operating margins, copper profitability, aluminium prices and expansion-related developments.
The key question is whether Hindalco can sustain its record earnings momentum despite international supply pressures.
With November 6 approaching, Novelis’ recovery and the strength of domestic operations could determine whether Hindalco delivers another strong quarter or faces expectations-related pressure in the stock.