BEL Q2 FY27 Results: Strong Revenue Growth Faces a Crucial Margin Test
Bharat Electronics Limited (BEL) is heading into its September-quarter earnings announcement with high expectations, but one important number could determine how investors react. While the defence electronics manufacturer is expected to deliver double-digit revenue growth, analysts anticipate pressure on its operating margin.
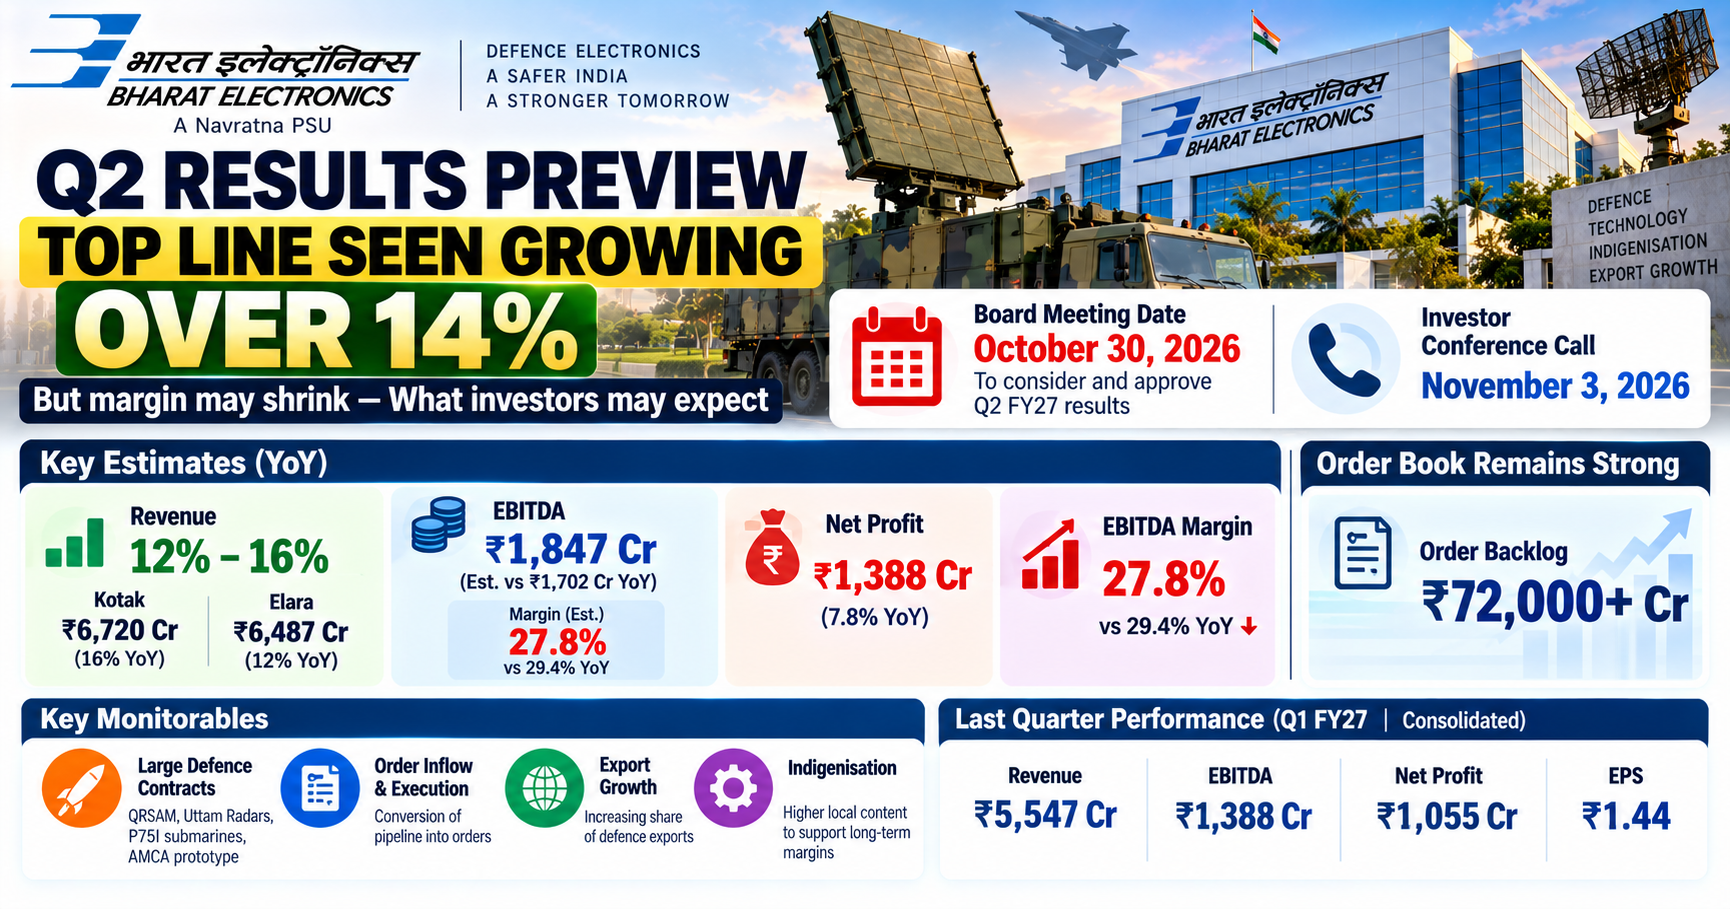
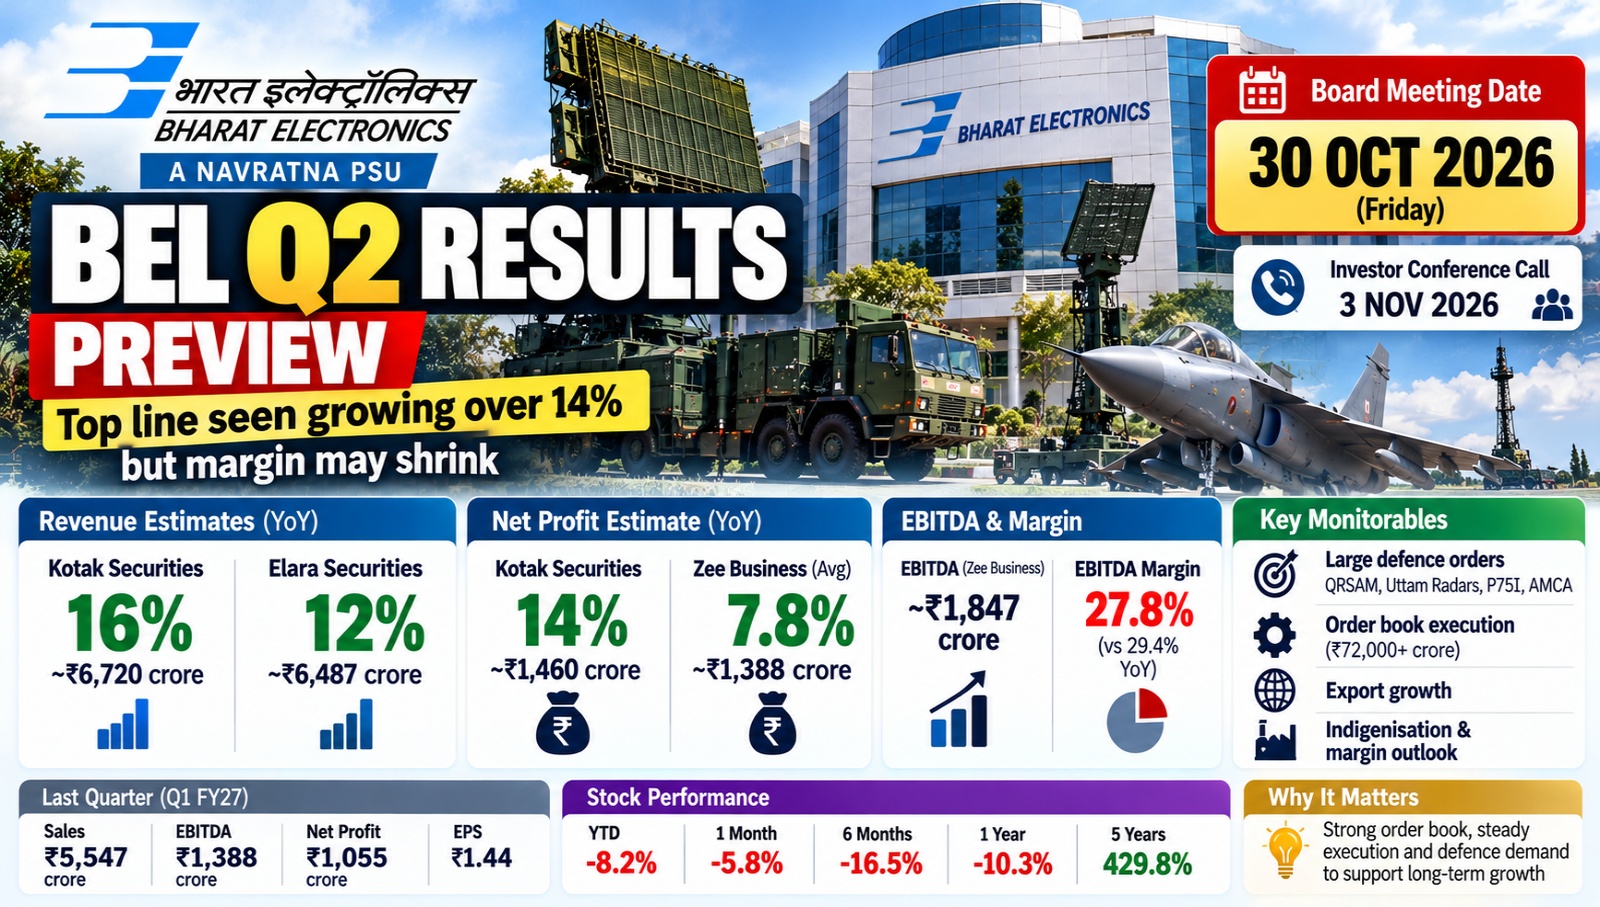
The Navratna public sector undertaking (PSU) is scheduled to announce its Q2 FY27 results on Friday, October 30, 2026. Investors will be watching whether strong execution from its sizeable defence order book can offset margin pressure and revive sentiment around the stock.
BEL shares have declined 8.2% year to date, according to the supplied figures, making the upcoming results an important near-term catalyst.
Track Live : Results Calendar — NSE & BSE
BEL Q2 FY27 Results: What Brokerages Expect
According to Zee Business research estimates provided, BEL could report consolidated revenue of ₹6,640 crore for the quarter ended September 30, 2026, representing approximately 14.5% year-on-year growth.
Net profit is estimated at ₹1,388 crore, up 7.8% from the corresponding quarter last year. EBITDA is projected to increase to ₹1,847 crore from ₹1,702 crore.
However, profitability could face pressure despite higher revenue.
BEL FY27 Management Guidance
| Key parameter | FY27 target |
|---|---|
| Revenue growth | Around 15% |
| EBITDA margin | Above 28% |
| Order inflow | Above ₹55,000 crore, including the potential QRSAM order |
Why BEL’s EBITDA Margin Could Fall Despite Higher Revenue
BEL’s EBITDA margin is expected to decline to 27.8% from 29.4% a year earlier, a contraction of 160 basis points. EBITDA is a measure of operating earnings before interest, taxes, depreciation and amortisation.
Brokerage estimates differ slightly. Kotak Securities expects revenue of around ₹6,720 crore, net profit of ₹1,460 crore and an EBITDA margin of 28.9%. Elara Securities projects revenue of approximately ₹6,487 crore and a margin of 27.4%.
The difference reflects varying assumptions about execution, product mix and operating costs. Investors will look for management commentary on whether margin pressure is temporary or could continue over the coming quarters.
Track Live : NSE Option Chain — Live | BSE Option Chain — Live Sensex & Bankex Options Data Today
BEL Q2 FY27 Consensus Estimates and Expectations
| Metric | Estimated Value | Projected Growth (YoY) | Key Drivers / Insights |
|---|---|---|---|
| Revenue | ₹6,487–₹6,720 crore | 12%–16% up | Supported by execution of the opening order book. |
| Net Profit (PAT) | ₹1,388–₹1,460 crore | 7.8%–14.1% up | Profit growth may be moderated by operating margin pressures. |
| EBITDA | ₹1,778–₹1,940 crore | Varies by brokerage | Higher revenue, with profitability influenced by product mix. |
| EBITDA Margin | 27.4%–28.9% | Down approximately 50–200 bps, depending on estimate | Changes in product mix may weigh on year-on-year margins. |
BEL has secured fresh orders ahead of its results
₹770 crore Army radar contract
October 22, 2026
BEL secured a contract to supply Improved Low Level Light Weight Radars to the Indian Army. The systems can detect and track aircraft and mini or micro drones.
₹1,011 crore in additional orders
Disclosed October 21, 2026
BEL reported additional orders since October 13 across radars, communication equipment, sonars, jammers, upgrades, spares and services.
These developments support BEL’s order pipeline. However, verify the underlying disclosures before adding the ₹770 crore contract separately to the ₹1,011 crore figure, so that the same order is not counted twice.
Order inflows have slowed despite a sizeable backlog
-
BEL’s Q1 FY27 order inflows were approximately ₹3,750 crore, down around 51% year-on-year.
-
Its order backlog stood at approximately ₹72,300 crore at the end of June 2026.
-
Kotak Institutional Equities subsequently highlighted a roughly 44% year-on-year decline in BEL’s financial-year-to-date order inflows in its October analysis.
Track Live : Nifty Levels Today | Sensex Levels Today
BEL Order Book and Defence Contracts Remain Key Growth Drivers
BEL’s existing order book, estimated at more than ₹72,000–₹73,000 crore, provides visibility for future revenue. Execution of these contracts is expected to support growth, although the pace of fresh order inflows remains an important concern.
Investors will watch for updates on major defence opportunities, including Quick Reaction Surface-to-Air Missile systems, Uttam Radars, next-generation corvettes, P75I submarines and the Advanced Medium Combat Aircraft programme.
The Defence Acquisition Council cleared procurement proposals worth ₹2.12 lakh crore on October 27, while BEL disclosed additional orders worth ₹533 crore on October 13, according to the supplied information. These developments support the broader defence-sector outlook but do not guarantee that the approvals will translate into BEL contracts.
Export growth and further indigenisation of components will also be important indicators of the company’s long-term competitiveness.
Read More : Margin Trading Is Booming, but NSE’s Audit Shows Where Brokers Slipped
Key Monitorables & Focus Areas
- Order Book: BEL’s order backlog stood at around ₹72,300 crore, while FY27-to-date inflows were approximately ₹7,300 crore, down 44% YoY. Investors will track QRSAM, Uttam radars and other major defence contracts.
- Margin Outlook: Motilal Oswal expects Q2 EBITDA margins to decline to 27.7% from 29.4% a year ago, citing changes in product mix.
- Defence Procurement: The DAC approved procurement proposals worth ₹2.12 lakh crore, creating potential opportunities for BEL. However, approvals do not guarantee contract awards.
Here’s What Happened Today and Why Traders Reacted
BEL shares traded around ₹365.50 on the BSE during Thursday’s afternoon session, gaining 0.5% on the day. However, the stock’s broader performance remained weak.
| Period | BEL share performance | Nifty 50 |
|---|---|---|
| 1 month | -5.8% | +0.6% |
| 6 months | -16.5% | -5.5% |
| 1 year | -10.3% | -12.3% |
| 5 years | +429.8% | +29.3% |
The figures show that BEL has faced near-term pressure despite delivering substantial long-term returns over five years.
Market participants will now assess whether the earnings announcement provides enough evidence of sustained growth to improve sentiment. A stronger-than-expected result could support the stock, while weaker margins or disappointing order commentary could weigh on it.
What BEL Q2 Results Could Mean for Investors
The immediate focus will be on revenue growth, profit margins and fresh order announcements. Strong execution and reassuring management commentary could improve confidence, but investors should avoid treating revenue growth alone as proof of improving profitability.
The company has scheduled its investor conference call for November 3, 2026, which could provide further insight into its outlook.