FIIs Pulled $56 Billion from India in Two Years — Bernstein Says Don’t Expect a Big Comeback
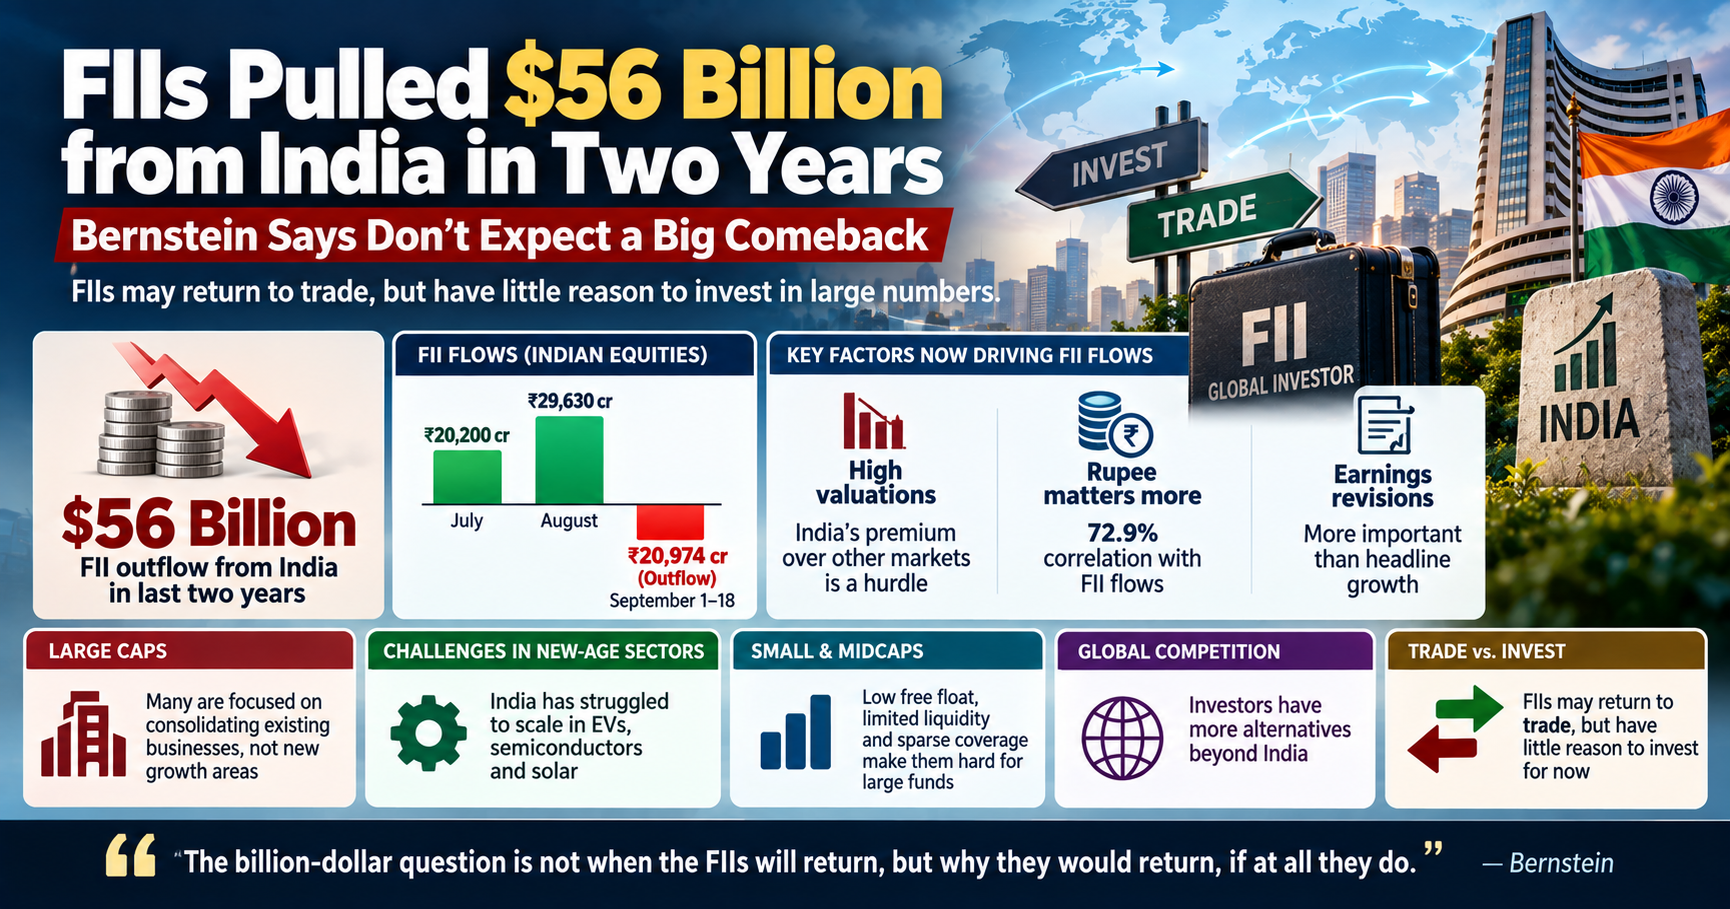
Foreign investors have started buying Indian equities again in recent months, but FII flows into India may not return in large numbers even if the global AI-led investment trade loses momentum. Bernstein says the bigger question is no longer when FIIs return, but what would make them commit capital to India for the long term.
The brokerage argues that India’s traditional attractions for foreign investors have changed, with valuations, the rupee and earnings revisions now playing a bigger role in determining FII flows.
Track Live : GIFT Nifty Live – Today Price, Chart, Timings and Nifty Opening Signal
FIIs Pulled $56 Billion from India Why valuations and the rupee now matter more for FII flows
According to Bernstein, relative valuations, currency returns and forward earnings revisions have become increasingly important drivers of FII flows into India.
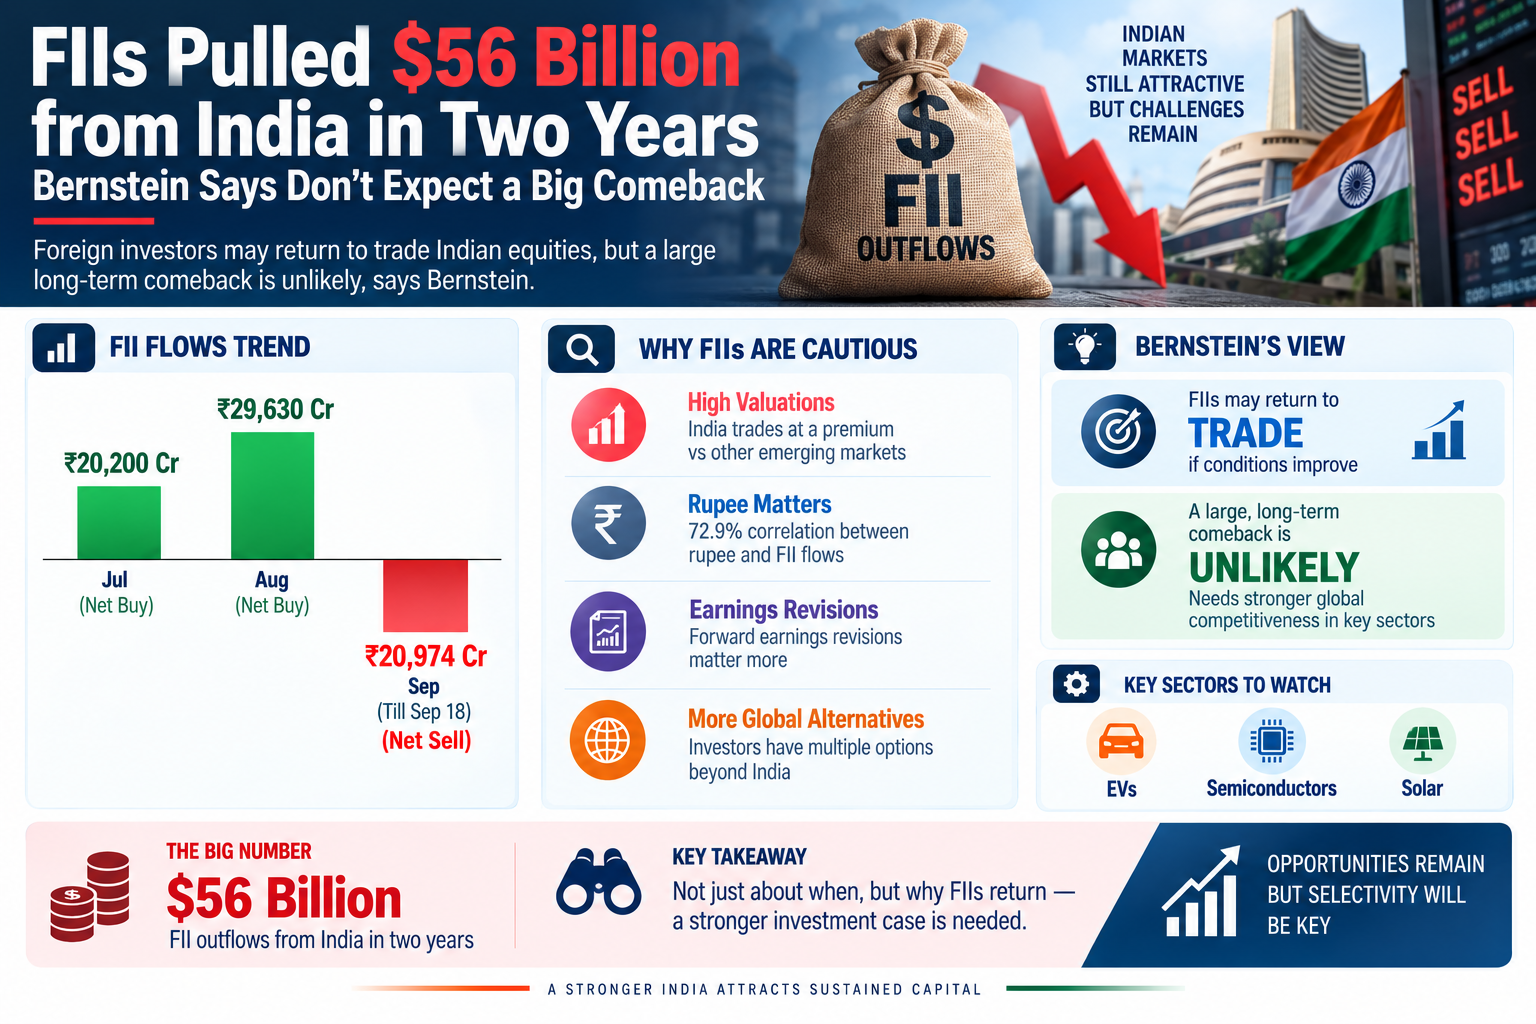
India’s valuation premium over other emerging markets has become a particular hurdle. The brokerage also estimates a recent 72.9% correlation between the rupee and FII flows, highlighting how currency movements can influence foreign investor returns.
A weaker rupee can reduce dollar-denominated returns for overseas investors. At the same time, FII selling can put additional pressure on the currency, creating a potential feedback loop.
Why the Old FII Playbook Is Broken
- India’s valuation premium is a hurdle: Bernstein says India’s premium over other emerging markets has become increasingly important to FII flows, particularly since 2020.
- The rupee matters more: Bernstein estimates a 72.9% correlation between the rupee and FII flows. Currency weakness can reduce dollar-denominated returns for foreign investors and potentially reinforce selling pressure.
- Earnings revisions matter more than headline growth: Bernstein says recent-quarter earnings growth has not consistently explained FII flows, while forward earnings revisions have shown a stronger relationship in some periods.
- GDP growth alone is no longer enough: The brokerage argues that the historical relationship between India’s macroeconomic growth and foreign inflows has weakened, while the India-US interest-rate differential has also become a less reliable FII driver.
- Global investors have more alternatives: Bernstein’s argument is that even if the AI-led trade loses momentum, capital will not automatically move into India. Investors will continue comparing India’s valuations, currency-adjusted returns and earnings outlook with opportunities elsewhere.
- The question has shifted from “when” to “why”: Bernstein’s central argument is that a structural FII revival requires a stronger investment case rather than simply waiting for money to rotate out of other global trades.
FII Selling Returns in September
- Nearly ₹21,000 crore outflow: FPIs withdrew ₹20,974 crore from Indian equities through September 18, after buying ₹20,200 crore in July and ₹29,630 crore in August.
- Key pressure points: Analysts attributed the renewed selling mainly to elevated crude prices, higher US bond yields, India’s valuation premium and rupee weakness.
- Selective, not a complete exit: Foreign investors are still participating in IPOs and other primary-market opportunities, suggesting that the September selling is not necessarily a wholesale withdrawal from India.
Large caps and midcaps face different FII challenges
Bernstein also raised concerns about India’s large-cap universe. The brokerage argued that several established companies are focused more on consolidating existing businesses than investing aggressively in emerging industries.
It cited areas such as electric vehicles, semiconductors and solar where India has struggled to scale globally.
For FIIs looking at small and midcaps, another challenge is liquidity. Bernstein said many companies remain sub-scale, have limited free floats and receive relatively sparse institutional coverage.
This makes them harder for large global funds to access at scale.
Track Live : NSE Option Chain — Live | BSE Option Chain — Live Sensex & Bankex Options Data Today
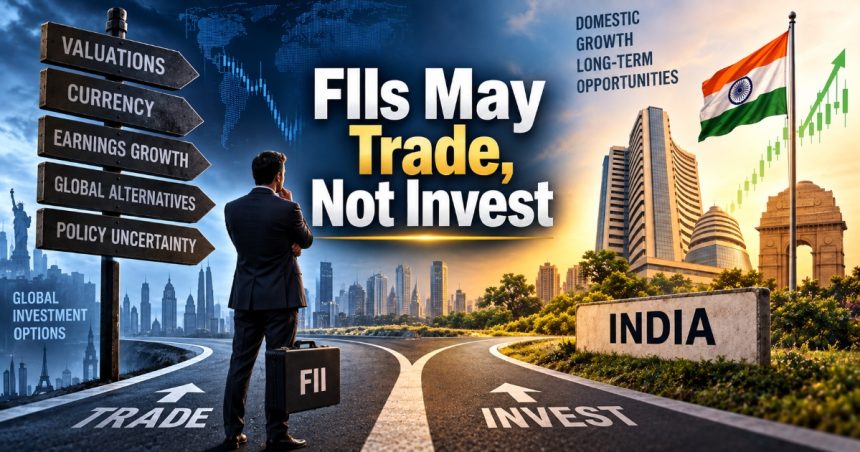
The Core Structural Issues: Trade vs. Invest
- Large-cap bottleneck: Bernstein says many large caps are focused more on consolidating existing businesses than building new growth engines.
- Weak scale in new technologies: The brokerage points to challenges in scaling EVs, semiconductors and solar, partly due to limited capital commitment.
- SMID-cap challenge: Small and midcaps often have low free floats, limited liquidity and sparse coverage, making large institutional investments difficult.
- More global alternatives: Foreign investors have other markets and opportunities to choose from, making India’s valuation and liquidity risks more important.
- Trade vs. invest: Bernstein expects FIIs could return for tactical trading, but says a lasting revival in long-term investment requires globally competitive industries and businesses.
Here’s what happened today and why traders reacted
Bernstein said it does not expect FIIs to return in large numbers simply because the AI trade peaks. The brokerage believes foreign investors could still return to trade Indian equities, particularly if oil prices decline, earnings growth accelerates or macroeconomic conditions improve.
However, Bernstein sees a difference between short-term trading flows and a sustained structural allocation to Indian equities. It said the traditional relationship between strong economic growth and FII inflows has weakened.
The India-US interest-rate differential, which became a more important FII trigger between 2012 and 2018, has also lost some of its influence since around 2019.
Read More : Trump Threatens 100% Tariffs Over Russian Oil as India-US Trade Talks Move Forward
What the FII outlook means for Indian investors
The FII debate matters because foreign flows can influence liquidity, the rupee and overall market sentiment. Recent data also shows that foreign participation can change quickly: FIIs invested ₹29,631 crore in Indian equities in August, their highest monthly inflow since September 2024, after buying ₹20,200 crore in July.
However, September has brought renewed selling pressure. FIIs were net sellers of about ₹2,033 crore on September 16, while DIIs bought about ₹3,908 crore.
For traders and investors, this makes FII flows, rupee movement, crude oil prices, valuations and earnings revisions important indicators to monitor.
Bernstein’s longer-term argument is that a sustained revival in foreign investment would require India to build globally competitive businesses in areas such as advanced semiconductor manufacturing, batteries, energy storage and other emerging industries.
The brokerage therefore draws a distinction between FIIs returning to trade Indian stocks and returning to make long-duration investments. That distinction could remain important for market sentiment in the coming quarters.