Hindalco Industries shares fell 1.88% to ₹920.25 on Friday, November 6, even as the company reported a 58.9% year-on-year (YoY) rise in consolidated Q2 FY27 profit. The results showed record EBITDA from non-LME-linked businesses, but sequentially lower consolidated EBITDA and weaker first-half operating cash generation remain important concerns for investors.
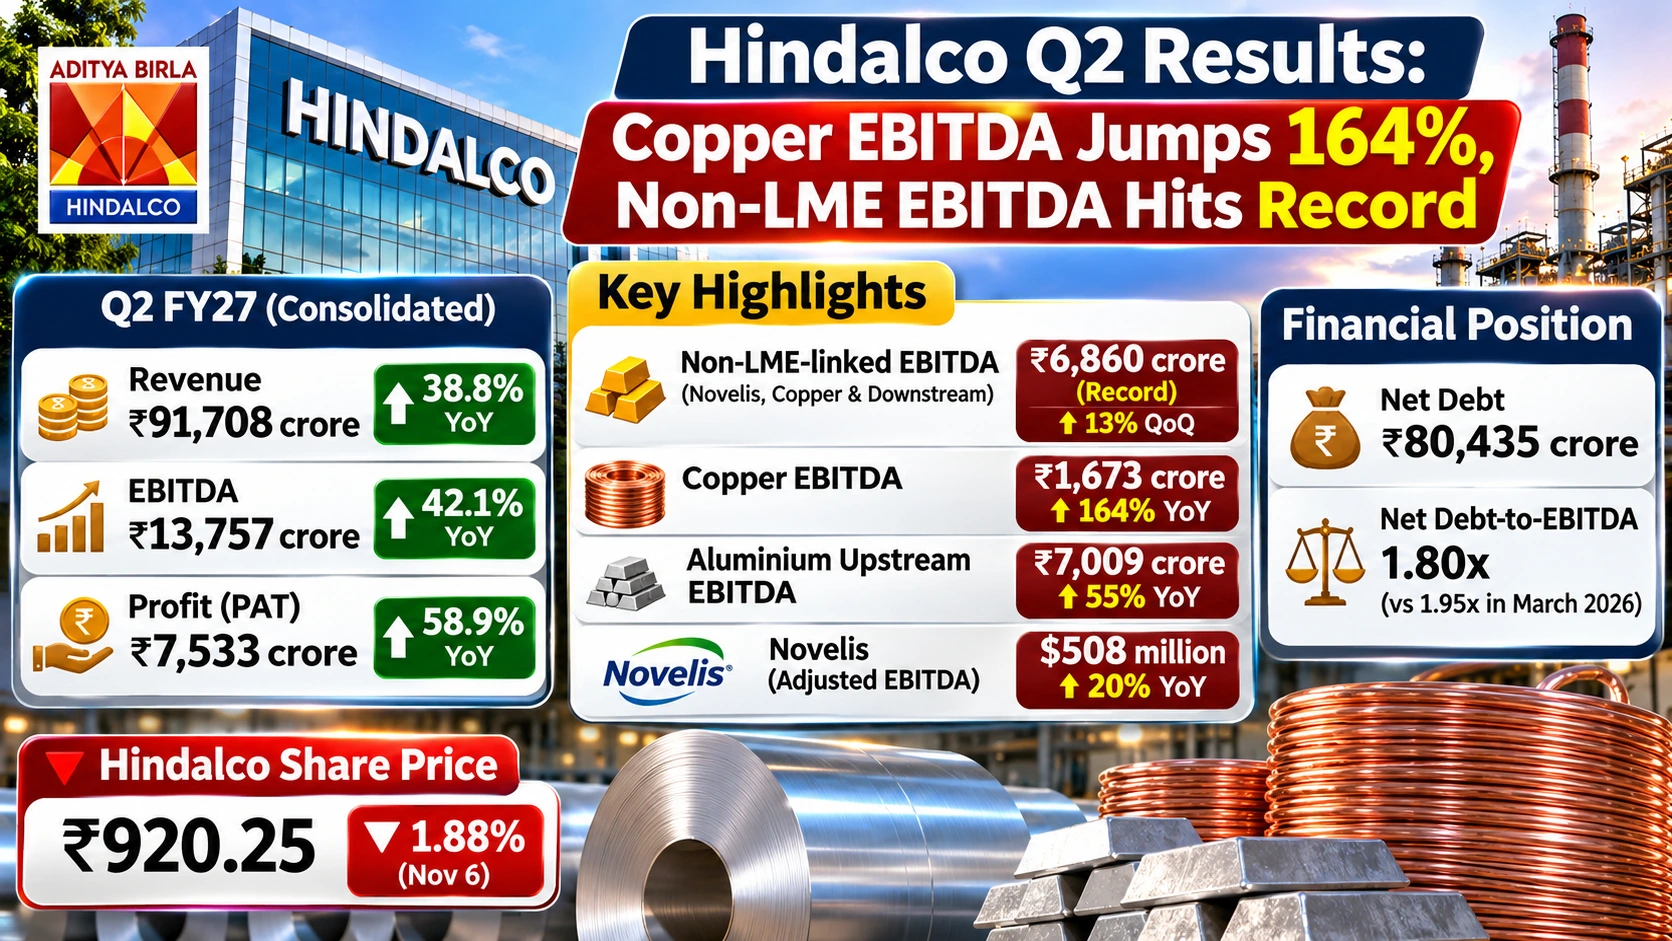
The company’s consolidated revenue from operations increased 38.8% to ₹91,708 crore, while EBITDA rose 42.1% to ₹13,757 crore. Profit for the period stood at ₹7,533 crore against ₹4,741 crore in the corresponding quarter last year. Profit attributable to Hindalco’s owners was ₹7,532 crore.
A key highlight was the record ₹6,860 crore EBITDA generated by Hindalco’s non-LME-linked businesses, comprising Novelis, copper and aluminium downstream operations. This represented 13% sequential growth despite a 10% decline in LME aluminium prices during the quarter, according to the company’s earnings presentation.
However, the results also contain important counterpoints. Consolidated EBITDA declined sequentially, Novelis shipments remained lower year-on-year, and Hindalco’s first-half statutory operating cash flow was considerably below the year-ago level.
Track Live: Hindalco Option Chain (HINDALCO) — Live OI, IV & PCR
Need to Know: Hindalco Q2 FY27 Results
- Consolidated revenue: ₹91,708 crore, up 38.8% YoY.
- Consolidated EBITDA: ₹13,757 crore, up 42.1% YoY.
- Consolidated PAT: ₹7,533 crore, up 58.9% YoY.
- Non-LME-linked EBITDA: Record ₹6,860 crore, up 13% sequentially.
- Copper EBITDA: ₹1,673 crore, up 164% YoY.
- Aluminium upstream EBITDA: ₹7,009 crore, up 55% YoY.
- Novelis adjusted EBITDA: $508 million, up 20% YoY.
- Net debt: ₹80,435 crore at September 30, 2026.
- Net debt-to-EBITDA: 1.80x, compared with 1.95x in March 2026.
Hindalco Q2 Results: Revenue Rises 39%, EBITDA Increases 42%
Hindalco’s consolidated revenue from operations increased to ₹91,708 crore in Q2 FY27 from ₹66,058 crore in Q2 FY26. Total income rose to ₹92,651 crore from ₹66,771 crore.
Consolidated EBITDA increased to ₹13,757 crore from ₹9,684 crore, representing growth of approximately 42.1%.
Profit before exceptional items and tax increased 53.4% to ₹10,310 crore against ₹6,722 crore in the year-ago quarter.
Profit before tax, including exceptional items, rose 62% to ₹10,594 crore from ₹6,540 crore. Consolidated profit for the period increased 58.9% to ₹7,533 crore.
Profit attributable to owners of Hindalco Industries was ₹7,532 crore, while basic earnings per share increased to ₹33.93 from ₹21.35.
Sequential Performance: Revenue and PAT Grow, but EBITDA Falls 8%
The quarter-on-quarter comparison presents a different picture from the strong year-on-year growth.
| Particulars | Q1 FY27 | Q2 FY27 | QoQ change |
|---|---|---|---|
| Revenue | ₹84,825 cr | ₹91,708 cr | +8.1% |
| Consolidated EBITDA | ₹14,989 cr | ₹13,757 cr | -8.2% |
| Business segment EBITDA | ₹13,480 cr | ₹13,869 cr | +2.9% |
| Profit before exceptional items and tax | ₹11,692 cr | ₹10,310 cr | -11.8% |
| Profit for the period | ₹7,013 cr | ₹7,533 cr | +7.4% |
The distinction between business segment EBITDA and consolidated EBITDA is important.
Aggregate business segment EBITDA increased 2.9% sequentially to ₹13,869 crore. However, after intersegment eliminations, unallocable expenses and other accounting adjustments, consolidated EBITDA declined 8.2% to ₹13,757 crore.
Reported PAT increased sequentially, but profit before exceptional items and tax declined. The comparison was also influenced by the ₹2,299 crore exceptional expense in Q1 FY27 and the ₹284 crore exceptional recovery recorded in Q2.
This indicates that the sequential increase in reported profit should not be interpreted as an equivalent improvement in underlying operating earnings.
Non-LME-Linked Businesses Deliver Record ₹6,860 Crore EBITDA
One of the most important disclosures in Hindalco’s investor presentation was the performance of its non-LME-linked businesses.
These businesses include Novelis, copper and aluminium downstream operations.
Their combined EBITDA reached an all-time high of ₹6,860 crore in Q2 FY27, up 13% sequentially from ₹6,091 crore in Q1 FY27.
The company highlighted that this growth came despite a 10% sequential decline in LME aluminium prices.
The performance was supported by the recovery at Novelis, operational improvements in copper and higher value addition and product innovation in aluminium downstream.
This business mix is strategically important because, according to Hindalco, the earnings of these operations have a lower correlation with LME prices than those of its upstream aluminium business.
However, lower correlation does not mean complete protection from metal-price movements, demand fluctuations or operating costs.
Copper Business EBITDA Jumps 164% to ₹1,673 Crore
Hindalco’s copper business delivered the strongest year-on-year EBITDA growth among its major operating segments.
Copper revenue increased 46.8% to ₹21,374 crore from ₹14,563 crore in Q2 FY26.
Business segment EBITDA surged 164% to ₹1,673 crore against ₹634 crore a year earlier.
Copper metal shipments increased 2% to 116 KT from 113 KT, while continuous cast rod shipments stood at 96 KT against 97 KT in the year-ago quarter.
EBITDA per tonne increased to $1,510 from $641, a rise of 136%.
However, the company’s earnings presentation specifically noted that the 63% sequential increase in copper EBITDA per tonne to $1,510 from $926 included a one-time gain.
The company also attributed the 82% sequential increase in copper segment EBITDA to normalisation following the planned smelter shutdown in Q1 FY27, higher LME prices and improved by-product realisations.
This distinction is important when assessing the sustainability of the copper segment’s exceptional growth. The 164% year-on-year increase and the 82% sequential increase reflect different comparison periods and operating factors.
The production figures also deserve attention. Copper cathode production declined 8% to 99 KT, while copper rod production fell 15% to 104 KT. These are production figures and should not be confused with the segment’s sales shipment numbers.
Also Check: HINDALCO INDUSTRIES Options Chart | Nifty Trader
Aluminium Upstream EBITDA Rises 55% to ₹7,009 Crore
Hindalco’s aluminium upstream business reported revenue of ₹13,364 crore in Q2 FY27, up 32.6% from ₹10,078 crore in the corresponding quarter last year.
Business segment EBITDA increased 55% to ₹7,009 crore from ₹4,524 crore.
Aluminium upstream shipments increased marginally to 345 KT from 341 KT.
EBITDA per tonne increased 40% to $2,125 from $1,521, while the segment’s EBITDA margin improved to 52% from 45%.
The company attributed the improvement to favourable market conditions and strong operational performance, partly offset by higher input costs.
Alumina production, including Utkal, increased 6% to 980 KT during the quarter. Production at the Utkal refinery stood at 670 KT, up 3%.
Aluminium Downstream EBITDA Reaches Quarterly High
The aluminium downstream business also reported improved profitability.
Revenue increased 44.7% to ₹5,511 crore from ₹3,809 crore in Q2 FY26.
EBITDA rose 26% to ₹329 crore from ₹261 crore.
Shipments increased 6% to 119 KT from 113 KT. The company attributed the performance to higher shipments and further value addition.
EBITDA per tonne improved 9% to $289, supported by premiumisation and improved operating leverage.
The increase indicates that stronger earnings were not restricted to upstream operations, with value-added aluminium products also contributing to the quarter’s performance.
Novelis Q2 Results: Adjusted EBITDA Rises 20%, Shipments Decline 2%
Novelis, Hindalco’s wholly owned subsidiary, reported net sales of $5.942 billion for Q2 FY27, up 25% year-on-year.
Adjusted EBITDA increased 20% to $508 million from $422 million. Adjusted EBITDA per tonne rose 23% to $553 from $448.
However, rolled-product shipments declined 2% to 919 KT from 941 KT.
Higher beverage-packaging and aerospace shipments were offset by lower automotive and specialty-product shipments. Novelis also reported better scrap spreads and higher recycling benefits.
Its net income attributable to its common shareholder rose 29% to $210 million. Excluding special items, net income also increased 29% to $146 million.
The reported $508 million adjusted EBITDA included $39 million in Oswego business-interruption insurance recoveries.
In rupee terms, the Novelis segment’s EBITDA increased 32% to ₹4,858 crore. Hindalco’s presentation attributed the higher rupee-denominated growth compared with the 20% US-dollar growth partly to favourable INR/USD exchange-rate movements.
Novelis Cost Savings and Bay Minette Expansion
Hindalco’s presentation provided additional information on Novelis’ recovery and expansion plans.
The company reported more than $240 million in run-rate cost savings through Q2 FY27 and retained its target of $350–400 million in total savings by the FY28 exit.
The Oswego hot mill has returned to normalised production following the two fire incidents in FY26. Cumulative insurance recoveries related to the incidents reached $519 million through September 2026.
Another major development was the Bay Minette facility in Alabama, which produced its first cold-rolled coil in September 2026.
Commercial shipments are expected to begin in Q1 FY28.
Novelis also maintained its long-term adjusted EBITDA guidance of more than $600 per tonne.
The company expects positive free cash flow and the beginning of a deleveraging cycle towards FY27 exit. These targets will depend on the recovery in operating cash flows, lower capital expenditure requirements and successful commercial ramp-up at Bay Minette.
Novelis Cash Flow and Leverage Remain Key Risks
Despite the improvement in quarterly profitability, Novelis’ first-half cash-flow performance remained weak.
For the six months ended September 30, 2026:
- Net cash used in operating activities was $418 million, compared with an inflow of $411 million in H1 FY26.
- Adjusted free cash flow outflow, a non-GAAP measure, was $1.804 billion, compared with an outflow of $499 million in the corresponding year-ago period.
- Net leverage increased to 4.7x from 4.1x at March 31, 2026.
- Total liquidity stood at $2 billion at September 30, 2026.
Novelis attributed the deterioration in adjusted free cash flow primarily to lower operating cash flow and capital expenditure related to the Bay Minette project.
This creates an important expectation gap: quarterly EBITDA has improved, but cash generation and leverage have not yet shown the same recovery.
Hindalco Net Debt Rises to ₹80,435 Crore; Ratio Improves Sequentially
Hindalco’s investor presentation showed consolidated net debt increasing from ₹64,841 crore at March 31, 2026, to ₹80,435 crore at September 30, 2026.
The company’s capital-allocation bridge identified the following movements:
| Net debt bridge | Amount |
|---|---|
| Net debt at March 31, 2026 | ₹64,841 cr |
| Net inflow from operations | -₹10,231 cr |
| Oswego impact, net of insurance recovery | +₹2,015 cr |
| Capital expenditure | +₹20,719 cr |
| Other movements | +₹3,091 cr |
| Net debt at September 30, 2026 | ₹80,435 cr |
Net debt increased approximately 24% during the six-month period.
However, the net debt-to-EBITDA ratio declined to 1.80x from 1.95x in March 2026 and 1.83x in June 2026. It remained higher than the 1.23x recorded in September 2025.
Hindalco said it was maintaining the ratio at 1.80x in line with its capital-allocation framework.
The company reported capital expenditure of ₹20,719 crore during H1 FY27, an increase of 83% year-on-year, towards strategic growth projects.
Cash-flow clarification: The ₹10,231 crore net inflow from operations shown in Hindalco’s capital-allocation bridge is a separate management-presented measure. It should not be confused with statutory net cash generated from operating activities, which stood at ₹2,825 crore in H1 FY27 after working-capital movements and tax.
The investor presentation separately labels ₹23,319 crore as cash flow from operations, while the statutory filing reports ₹23,312 crore as operating profit before working-capital changes. These are different presentation measures and should not be treated as interchangeable with the ₹2,825 crore statutory operating cash flow. The statutory filing does not provide a reconciliation between these presentation figures.
Similarly, the ₹20,719 crore capital expenditure figure in the presentation’s capital-allocation bridge is distinct from the ₹19,344 crore of payments to acquire property, plant and equipment, intangible assets and investment property reported in the statutory cash-flow statement.
The increase in net debt highlights the funding requirements of these investments, even as the company expects improved future cash flows to support deleveraging.
Consolidated Operating Cash Flow Falls to ₹2,825 Crore in H1
Hindalco’s statutory consolidated cash-flow statement reported net cash generated from operating activities of ₹2,825 crore for the six months ended September 30, 2026, compared with ₹8,016 crore in H1 FY26.
This represents a decline of approximately 64.8%.
Payments to acquire property, plant and equipment, intangible assets and investment property increased to ₹19,344 crore from ₹10,685 crore.
Working-capital movements were a major factor. The company reported:
- Inventory-related cash outflow of ₹8,279 crore.
- Trade-payables-related cash outflow of ₹4,634 crore.
- Other financial-liability-related cash outflow of ₹1,814 crore.
Hindalco’s closing cash and cash-equivalent balance stood at ₹13,028 crore at September 30, 2026.
The cash-flow statement is important because it shows that the increase in quarterly profit has not yet translated into a comparable improvement in statutory operating cash generation during the first half.
Hindalco India Business PAT Rises 91% to ₹5,852 Crore
The presentation separately reported strong performance from Hindalco’s India businesses.
Revenue increased 42% to ₹36,123 crore from ₹25,494 crore in Q2 FY26.
Business segment EBITDA increased 66% to ₹9,011 crore, while EBITDA after intersegment eliminations and unallocable expenses rose 70% to ₹8,765 crore.
Profit after tax increased 91% to ₹5,852 crore from ₹3,060 crore.
However, the company specifically clarified that the PAT increase was aided by its transition to the new tax regime, effective April 1, 2026.
The effective tax rate declined to 25% in Q2 FY27 from 29% in Q2 FY26.
This means the improvement in India-business PAT reflects both stronger operating performance and a lower effective tax rate.
Separately, the statutory standalone financial results of Hindalco Industries Limited showed revenue of ₹35,369 crore and PAT of ₹5,132 crore for Q2 FY27, compared with ₹24,780 crore and ₹2,266 crore, respectively, a year earlier.
The standalone and Hindalco India-business figures are different reporting measures and should not be interchanged.
Global Aluminium Prices and Demand Outlook
The commodity environment remained supportive on a year-on-year basis, although sequential metal-price movements were less favourable.
According to Hindalco’s presentation, the LME aluminium price was $3,227 per tonne in Q2 FY27, compared with $3,576 per tonne in Q1 FY27, a sequential decline of approximately 10%.
The presentation showed the Q3 FY27 price level at $3,071 per tonne up to November 6, 2026.
Globally, aluminium production declined 1% year-on-year in Q2 FY27, while consumption increased 1%.
Hindalco projected that the global aluminium market deficit could widen to approximately 0.8 million tonnes in calendar year 2026, compared with a pre-conflict estimate of 0.3 million tonnes.
On the Indian side, the company’s estimate placed Q2 FY27 aluminium demand at 1,735 KT, up 6% year-on-year, led primarily by automotive and electrical demand.
The copper market presented a different demand picture. India’s copper market was estimated at 388 KT in Q2 FY27, down 3% from 398 KT in Q2 FY26. Growth in building and construction and power demand was offset by weakness in consumer durables and electrical equipment.
The outlook therefore depends not only on international prices but also on how demand, supply and operating costs evolve across Hindalco’s individual businesses.
Hindalco Q2 FY27: First-Half Earnings Also Show Strong Growth
For the six months ended September 30, 2026, Hindalco reported:
| Particulars | H1 FY27 | H1 FY26 | YoY growth |
|---|---|---|---|
| Revenue from operations | ₹1,76,533 cr | ₹1,30,290 cr | 35% |
| Consolidated EBITDA | ₹28,746 cr | ₹18,357 cr | 57% |
| Profit before exceptional items and tax | ₹22,002 cr | ₹12,398 cr | 77% |
| Profit after tax | ₹14,546 cr | ₹8,745 cr | 66% |
The first-half figures indicate that the earnings improvement extended beyond one quarter. However, the cash-flow performance and the investment requirements of the business remain important considerations.
Hindalco Share Price Closes 1.88% Lower
Hindalco shares ended Friday’s session at ₹920.25, down ₹17.60 or 1.88% from the previous close of ₹937.85.
The stock touched an intraday low of ₹891.45 and an intraday high of ₹928.50.
The closing decline came alongside stronger consolidated earnings and record non-LME-linked EBITDA. The share-price movement alone does not establish that the results caused the decline.
Investors will likely continue monitoring the cash-flow recovery at Novelis, the company’s investment programme, net debt and the sustainability of copper and aluminium profitability.
Read Next: Nasdaq Falls 5.5% as Nearly $3 Trillion Rout Puts AI Returns on Trial
Bottom Line
Hindalco’s Q2 FY27 performance highlights a broader earnings improvement across aluminium, copper and Novelis. The record ₹6,860 crore EBITDA from non-LME-linked businesses is particularly important because it demonstrates the increasing contribution of businesses with lower direct exposure to LME price movements.
However, the 164% jump in copper EBITDA also needs context. The sequential increase in copper EBITDA per tonne included a one-time gain, while normalisation after the previous quarter’s planned smelter shutdown also supported segment profitability. Novelis’ shipments declined, its first-half adjusted free cash flow remained negative, and consolidated statutory operating cash generation at Hindalco fell year-on-year.
The next phase will depend on whether Novelis can convert its operational recovery into positive free cash flow, Bay Minette can begin commercial shipments on schedule, and Hindalco can manage its higher investment commitments while improving cash generation.
For investors, the record non-LME EBITDA is encouraging, but the quality and cash conversion of earnings will be just as important as the headline profit growth.
Sources: Hindalco Industries’ Q2 FY27 exchange filing and earnings presentation dated November 6, 2026; Novelis’ Q2 FY27 results release.
Disclaimer: This article is for informational and educational purposes only and should not be considered investment advice or a recommendation to buy or sell Hindalco shares. Investors should verify information independently, assess market risks and consult a qualified financial advisor before making investment decisions.