Freshworks Q3: Crosses $1 billion ARR ahead of its 2026 target
Freshworks has achieved a major business milestone ahead of schedule, crossing $1 billion in annual recurring revenue (ARR) in October 2026, well before its original year-end target.
The Nasdaq-listed software-as-a-service (SaaS) company also reported a sharp improvement in profitability for the September quarter, signalling stronger financial performance and improving operating efficiency.
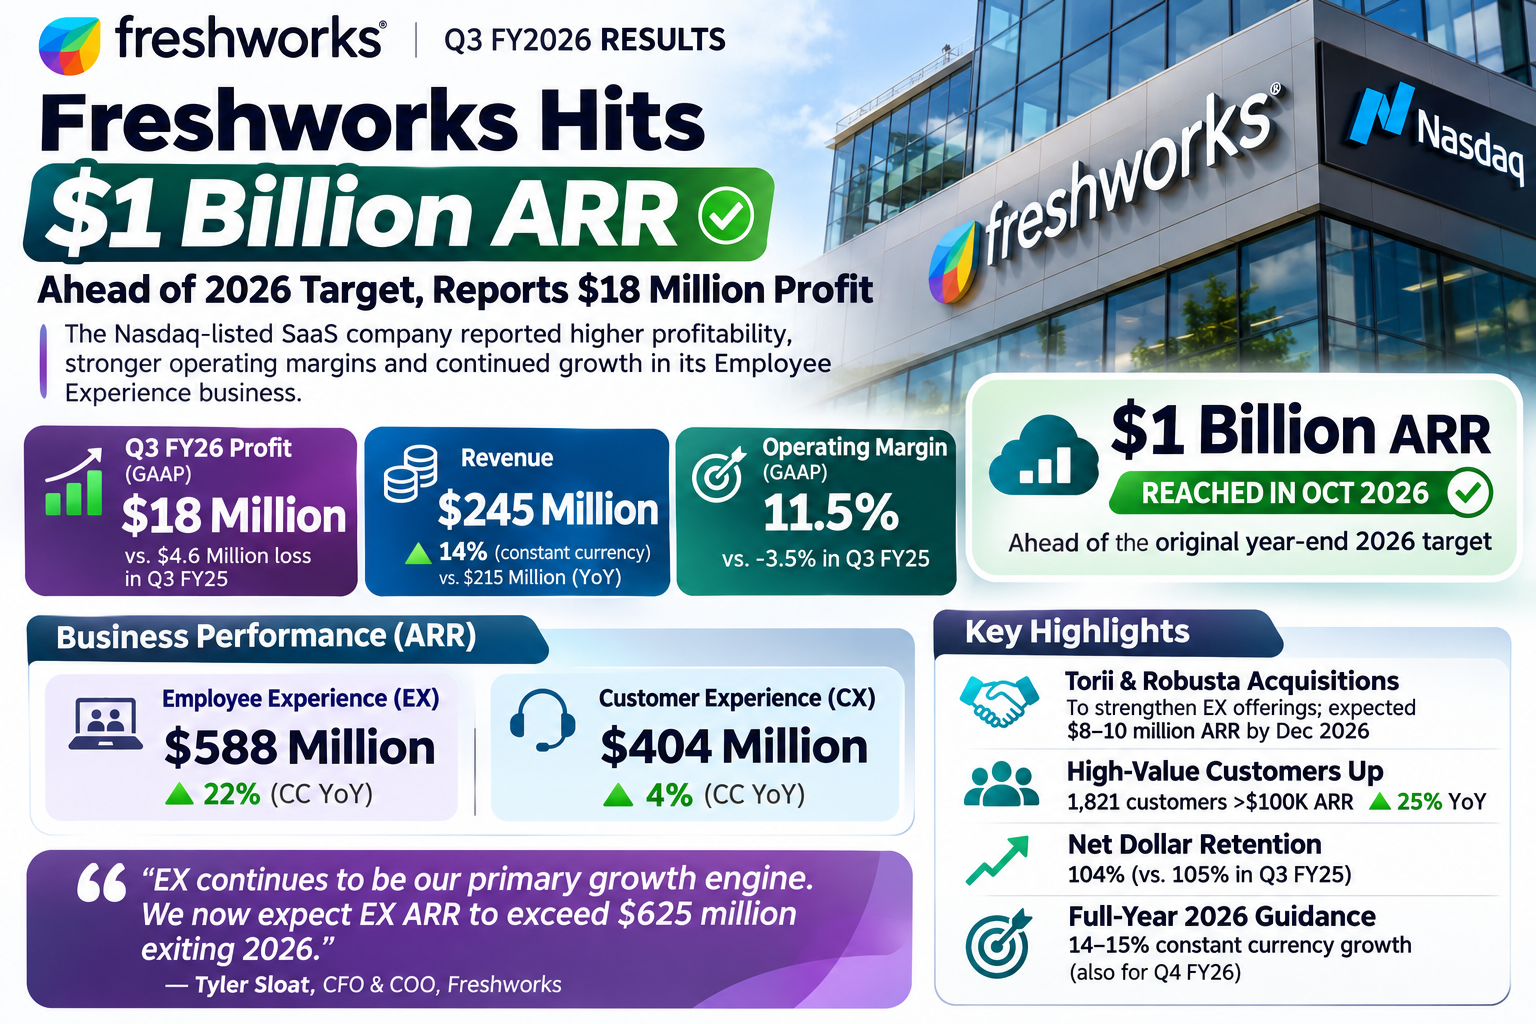
Freshworks reported a GAAP net profit of $18 million for the third quarter of 2026, compared with a net loss of $4.6 million in the corresponding quarter last year.
Revenue increased to $245 million from $215 million, representing constant currency growth of 14%.
However, despite the positive earnings performance, Freshworks shares fell marginally to close at $14.15 on Nasdaq.
For investors, the key question is whether the company’s improving profitability and billion-dollar ARR milestone can support stronger share price performance in the coming quarters.
Track Live : NSE Option Chain — Live | BSE Option Chain — Live Sensex & Bankex Options Data Today
Freshworks Q3: Employee Experience business emerges as Freshworks’ biggest growth driver
The Employee Experience (EX) business continued to drive Freshworks’ ARR expansion during the quarter.
CEO Dennis Woodside said Employee Experience ARR increased 22% on a constant currency basis to $588 million.
Meanwhile, Customer Experience ARR stood at $404 million, representing 4% constant currency growth.
CFO and COO Tyler Sloat said, “EX continues to be our primary growth engine.”
He added that the company expects EX ARR to exceed $625 million by the end of 2026.
The company believes its Employee Experience business can continue growing at a mid-20% rate as it expands its multiproduct platform.
Freshworks Q3 2026 results: Key financial highlights
Freshworks reported revenue of $245.4 million for the September quarter, compared with $215.1 million in Q3 2025, representing year-on-year growth of approximately 14%.
| Financial metric | Q3 2026 | Q3 2025 |
|---|---|---|
| Revenue | $245.4 million | $215.1 million |
| GAAP net income | $18.3 million | -$4.7 million |
| GAAP operating income | $28.2 million | -$7.5 million |
| GAAP operating margin | 11.5% | -3.5% |
| Non-GAAP operating income | $73.2 million | $45.2 million |
| Non-GAAP operating margin | 29.8% | 21.0% |
| Gross profit | $209.4 million | $182.2 million |
| Gross margin | 85.3% | 84.7% |
The improvement in profitability is particularly notable because Freshworks moved from an operating loss to a positive operating profit within a year.
Its non-GAAP operating margin also expanded substantially, indicating improved cost efficiency alongside revenue growth.
Freshworks crosses $1 billion ARR ahead of its original deadline
One of the biggest developments from the results is Freshworks crossing $1 billion in annual recurring revenue in October.
The company had previously expected to achieve this milestone by the end of 2026.
An important distinction is that Freshworks ended September with approximately $992 million in ARR and crossed the $1 billion threshold after completing its October acquisitions of Torii and Robusta.
ARR represents the annualised value of recurring subscription contracts. It is not the same as revenue already earned during a financial year.
The milestone reflects Freshworks’ expanding subscription business and growing customer base.
According to CEO Dennis Woodside, the company added approximately $250 million in ARR during his tenure, which began in May 2024.
Torii and Robusta acquisitions expected to strengthen business growth
Freshworks also acquired Torii and Robusta during the September quarter.
Both acquisitions will be integrated into its Employee Experience offerings to strengthen the company’s product portfolio.
Management expects the two acquisitions to contribute between $8 million and $10 million in ARR by the end of the December quarter.
CEO Dennis Woodside indicated that Freshworks would remain disciplined with future acquisitions while continuing to explore opportunities that strengthen its go-to-market operations.
Track Live : Nifty Levels Today | Sensex Levels Today
The acquisitions include:
-
Torii: A SaaS management and AI spend governance platform that helps businesses monitor software subscriptions, manage SaaS expenditure and improve software utilisation.
-
Robusta: An AI-powered IT troubleshooting and automation company focused on identifying and resolving technology-related problems.
According to Freshworks’ earnings coverage, the company expects the two acquisitions to contribute approximately $8 million to $10 million in ARR by the end of the December quarter.
The company spent a combined preliminary consideration of approximately $102.5 million on the two October acquisitions, primarily in cash.
Employee Experience business becomes Freshworks’ biggest growth engine
The Employee Experience (EX) business continues to drive Freshworks’ growth.
During the investor call, management highlighted the following ARR figures:
| Business segment | ARR | Constant-currency growth |
|---|---|---|
| Employee Experience | $588 million | 22% |
| Customer Experience | $404 million | 4% |
Employee Experience represented approximately 59% of the company’s combined reported segment ARR at the September quarter-end.
The business includes software solutions designed to help organisations manage employee IT support, service requests and workplace technology experiences.
CFO and COO Tyler Sloat said Employee Experience would continue to be a major growth engine as Freshworks expands its multiproduct platform.
Management expects EX ARR to exceed $625 million by the end of 2026.
Freshworks operating margin improves as profitability strengthens
Another important highlight of the Freshworks Q3 results was the improvement in operating profitability.
The company reported a GAAP operating margin of 11.5%, compared with negative 3.5% in the same quarter last year.
Management attributed the improvement partly to restructuring its go-to-market operations earlier in 2026, particularly within the Customer Experience business.
This improvement indicates that Freshworks is becoming more efficient while continuing to invest in business expansion.
High-value customers increase as Freshworks expands its enterprise business
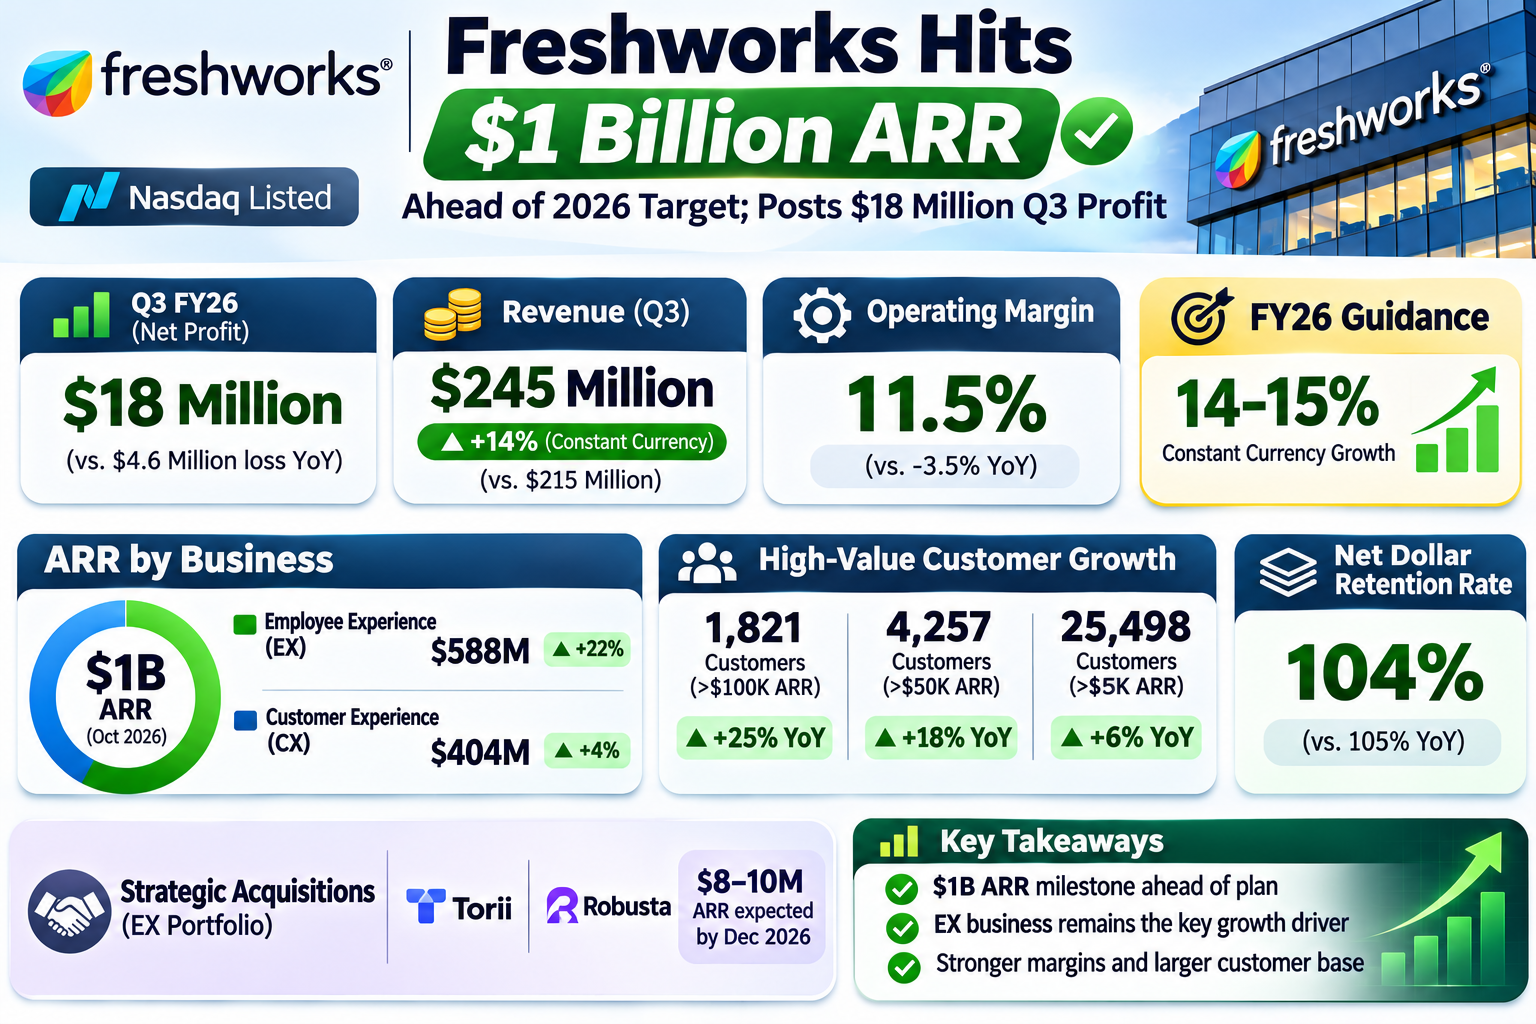
Freshworks also reported growth across its higher-value customer categories.
| Customer category | Q3 2026 customers | YoY growth |
|---|---|---|
| Above $100,000 ARR | 1,821 | 25% |
| Above $50,000 ARR | 4,257 | 18% |
| Above $5,000 ARR | 25,498 | 6% |
However, its net dollar retention rate stood at 104%, compared with 105% in the year-ago quarter.
This indicates that customer expansion remains positive, although the retention metric deserves attention.
Read More : Why Muthoot Finance Jumped 8% Today: Gold’s Biggest Rise Since August
Operating margin improves sharply as Freshworks focuses on profitability
One of the strongest aspects of the September-quarter results was the improvement in operating efficiency.
Freshworks reported a GAAP operating margin of 11.5%, compared with negative 3.5% in Q3 2025.
Its non-GAAP operating margin also expanded to 29.8% from 21% in the corresponding quarter last year.
Management attributed the improvement partly to changes in its go-to-market strategy and greater operational discipline.
The company reduced certain operating expenses while continuing to invest in product development and AI capabilities.
What changed in operating expenses?
| Expense category | Q3 2026 | Q3 2025 | Change |
|---|---|---|---|
| Sales and marketing | $98.5 million | $101.0 million | -2.5% |
| Research and development | $44.7 million | $41.5 million | +7.8% |
| General and administration | $38.2 million | $47.1 million | -19% |
| Total operating expenses | $181.2 million | $189.6 million | -4.4% |
Cash flow improves as Freshworks reports record adjusted free cash flow
Another important development is the improvement in cash generation.
Freshworks generated $77.7 million in cash from operating activities during Q3 2026, compared with $63.5 million in the year-ago quarter.
Adjusted free cash flow increased to $73.9 million from $57.2 million, representing growth of approximately 29%.
Its adjusted free cash flow margin improved to 30.1% from 26.6%.
The company ended September 2026 with $697.3 million in cash, cash equivalents, restricted cash and marketable securities.
| Cash-flow indicator | Q3 2026 | Q3 2025 |
|---|---|---|
| Operating cash flow | $77.7 million | $63.5 million |
| Adjusted free cash flow | $73.9 million | $57.2 million |
| Adjusted free cash flow margin | 30.1% | 26.6% |
| Cash and marketable securities | $697.3 million | Not comparable in this table |
Here’s what happened today and why traders reacted
Freshworks delivered three important developments in its Q3 2026 results.
-
ARR milestone: Crossed $1 billion in October, ahead of schedule.
-
Profitability: Reported an $18 million GAAP net profit against a $4.6 million loss last year.
-
Revenue growth: Quarterly revenue increased to $245 million, representing 14% constant currency growth.
The company maintained its full-year 2026 constant currency revenue growth guidance of 14-15%.
For the December 2026 quarter, Freshworks also expects constant currency revenue growth of 14-15%.
The marginal decline in Freshworks shares suggests investors may be looking beyond headline earnings to assess future growth and valuation.
What Freshworks Q3 results mean for investors
Freshworks’ $1 billion ARR milestone, improving operating margins and return to GAAP profitability are encouraging developments.
The 22% growth in Employee Experience ARR also highlights the company’s ability to expand beyond its traditional customer support offerings.
However, investors should monitor revenue growth, customer retention, acquisition contributions and the company’s ability to maintain profitability.