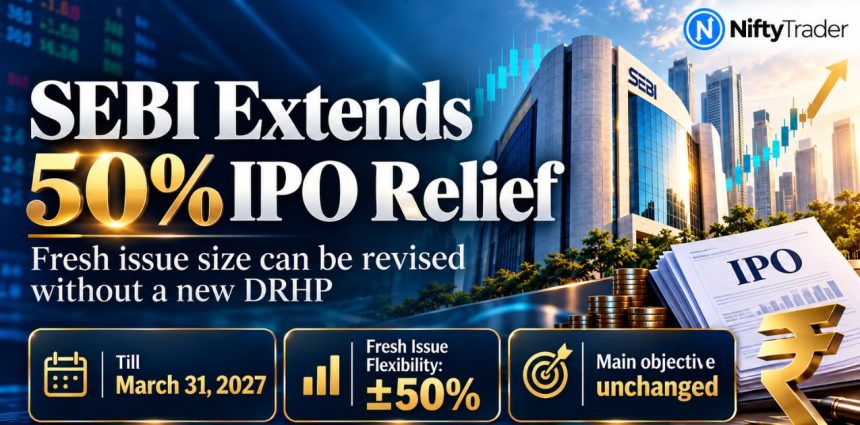
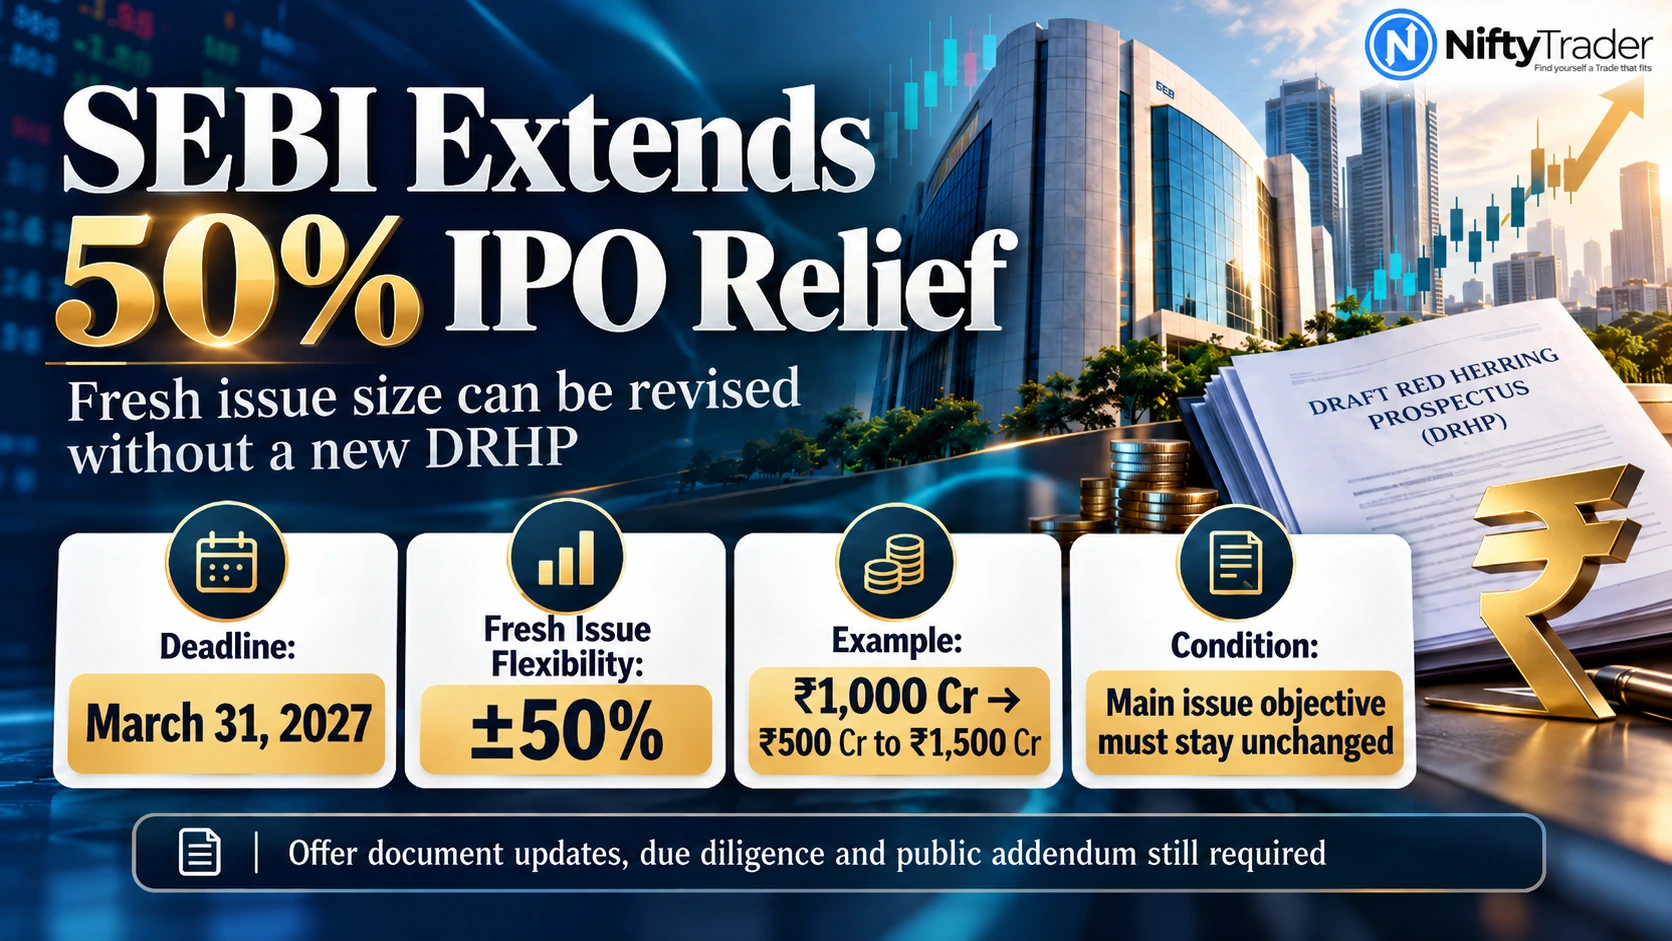
The Securities and Exchange Board of India (SEBI) has extended its temporary relaxation, allowing eligible companies to increase or decrease the fresh issue size of an initial public offering (IPO) by up to 50% without filing a fresh draft offer document. The extension applies to IPOs opening on or before March 31, 2027, giving issuers six more months of flexibility beyond the earlier September 30, 2026, deadline.
The decision was communicated to the Association of Investment Bankers of India (AIBI) on October 12, 2026, according to reports by Reuters and Business Standard. The relaxation allows companies to adjust proposed fundraising amounts as market conditions and business requirements change, subject to disclosure, due-diligence and other applicable regulatory requirements.
The extension comes amid strong primary-market activity. According to AIBI figures reported by NDTV Profit, 161 mainboard and SME IPOs raised a combined ₹94,649 crore during July–September 2026. However, the relaxation does not guarantee successful subscriptions, favourable valuations or listing gains.
Check Live: SME IPOs 2026 (Full List With Details of SME IPO)
What Has Changed Under SEBI’s IPO Rules?
Under the earlier framework, changes of more than 20% in the proposed issue size generally required companies to file fresh draft offer documents. The temporary relaxation expanded the permitted revision to 50%, subject to prescribed conditions.
The extension keeps that flexibility available for eligible IPOs opening by March 31, 2027.
For illustration, if a company originally proposes a fresh issue of ₹1,000 crore, a 50% increase would take the proposed fresh issue to ₹1,500 crore, while a 50% decrease would reduce it to ₹500 crore. Any such revision would remain subject to SEBI’s conditions, including justification, updated disclosures and an unchanged main objective.
The revised framework allows the lead manager to file an updated offer document reflecting the revised issue size instead of requiring an entirely fresh draft filing. It reduces procedural friction, but it does not give companies unrestricted permission to change their offerings.
Also Read: SEBI Settlement Rules 2026: ₹10 Lakh Fast Track Has a Catch
Four Conditions IPO-Bound Companies Must Still Meet
1. The relaxation applies to the fresh issue component.
A fresh issue involves a company issuing new shares to raise capital. The 50% flexibility should not be interpreted as blanket permission to revise every component of an IPO, including its offer-for-sale portion, on the same terms.
2. The main objective of the issue must remain unchanged.
Companies cannot use the relaxation to change the fundamental purpose for which they are raising money.
3. Updated disclosures and a public addendum are required.
The lead manager must update the relevant sections of the offer document to reflect the revised size and ensure the required changes are disclosed publicly through an addendum.
4. Lead managers must justify the revision and certify regulatory compliance.
Book-running lead managers must carry out the required due diligence, justify the revised fresh issue size and certify compliance with applicable SEBI regulations.
These safeguards are intended to preserve transparency while allowing companies to respond to changing business requirements and market conditions.
₹94,649 Crore Raised Through 161 IPOs in One Quarter
The scale of India’s primary market helps explain the importance of the extension.
According to AIBI data reported by NDTV Profit, mainboard IPOs raised ₹90,482 crore through 69 issues during July–September 2026. Another 92 SME IPOs raised ₹4,167 crore.
Combined, the 161 offerings mobilised ₹94,649 crore during the quarter.
September was the strongest month, with mainboard IPOs raising ₹39,381 crore through 34 issues and SME IPOs raising ₹2,123 crore through 52 issues. Total fundraising for the month reached ₹41,504 crore.
The activity extends beyond companies already in the market. The estimated mainboard IPO pipeline stood at around ₹3.86 lakh crore as of September 2026, according to India Today’s report citing AIBI. The pipeline includes offerings at different stages of the approval process; it is not a forecast of funds certain to be raised.
For companies planning listings, the extension could help reduce delays and duplicated filing work when the required amount of fresh capital changes after a draft prospectus has been submitted.
Why Strong IPO Fundraising Does Not Guarantee Investor Demand
The fundraising boom also needs to be viewed alongside a less uniform picture of foreign investment in Indian equities.
According to the Financial Express, citing JM Financial’s FII Monthly Flow Tracker, foreign institutional investors recorded approximately $9.2 billion in net inflows into India’s primary market over the 12 months to September 2026, while withdrawing about $39 billion from the secondary market.
These figures cover different investment channels and are not directly interchangeable. Nevertheless, they highlight a potential tension: new share offerings can attract foreign capital even as investors sell existing listed shares.
For IPO-bound companies, the distinction matters. Greater flexibility to revise an issue size can help issuers respond to market conditions, but it cannot guarantee that investors will accept the proposed valuation, subscribe to the issue or support the stock after listing.
The extension addresses the procedural burden associated with resizing a fresh issue. It does not remove the commercial risks involved in launching an IPO during uncertain market conditions.
What the Extension Means for IPO Investors
For retail investors, the change is primarily a regulatory and procedural development, rather than a direct investment signal.
A revision in the fresh issue size can alter the amount of new capital a company intends to raise. Investors should therefore review the updated offer document and addendum to understand the revised issue size, intended use of proceeds and other relevant disclosures.
It is also important to distinguish a fresh issue from an offer for sale (OFS). In a fresh issue, the company raises capital by issuing new shares. In an OFS, existing shareholders sell their shares, with the proceeds going to those shareholders rather than to the company.
Consequently, the total IPO size alone does not show how much money the company will receive directly.
Investors should continue to assess an IPO’s valuation, financial position, business risks and use of proceeds independently. The SEBI extension may make the filing process more adaptable, but it does not make every upcoming IPO more attractive.
The next test is whether the additional flexibility helps issuers complete suitable offerings without weakening disclosure discipline. The change gives companies more room to adjust fundraising plans; actual IPO outcomes will still depend on market conditions, pricing and investor appetite.
TRACK LIVE: Latest IPO News & Updates
Need to Know
- Deadline: IPOs opening on or before March 31, 2027.
- Permitted revision: Increase or decrease in fresh issue size by up to 50%, subject to the relaxation’s conditions.
- Key restriction: The main objective of the issue must remain unchanged.
- Investor safeguards: Justification, updated offer documents, a public addendum, due diligence and regulatory compliance remain necessary.
Read Next: STT Relief? FM Makes No Promise; F&O Costs Stay Higher
FAQs
1. What is SEBI’s IPO size relaxation?
It is a temporary relaxation allowing eligible IPO-bound companies to revise the size of their fresh issue by up to 50% without filing an entirely fresh draft offer document, subject to specified conditions.
2. When does the extended IPO size relaxation expire?
The extension applies to IPOs opening on or before March 31, 2027. The earlier September 30, 2026, deadline has been extended.
3. Can a company change the purpose of its IPO under this relaxation?
No. The main objective of the issue must remain unchanged. Companies and lead managers must also meet applicable disclosure, due-diligence and compliance requirements.
4. Does the extension guarantee listing gains?
No. It changes the procedural flexibility available to issuers. It does not guarantee regulatory clearance, subscription demand, attractive valuations or positive listing-day returns.
5. Does the 50% flexibility apply to the entire IPO?
The reported relaxation specifically concerns the fresh issue component. Investors should review the revised offer documents to distinguish new capital raised by the company from shares sold by existing shareholders through an OFS.
Disclaimer
This article is for informational and educational purposes only and does not constitute investment advice or a recommendation to apply for any IPO. Public issues carry risks relating to valuation, subscription demand, market conditions and post-listing volatility. Investors should read the offer documents carefully and consult a SEBI-registered investment adviser where appropriate.