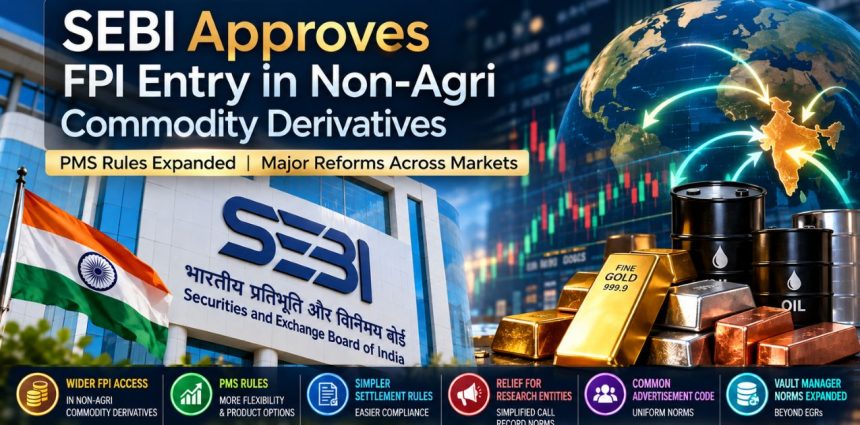
SEBI has approved wider foreign portfolio investor access to non-agricultural commodity derivatives, expanding the range of contracts available to overseas institutions.
At the same board meeting, the regulator approved a new ₹25 lakh PRIM route for mutual-fund-focused portfolio management, along with a wider overhaul of PMS rules.
The next market signal to watch is whether these changes translate into deeper institutional participation, higher liquidity and greater asset flows once the detailed implementation framework takes effect.
Track Live: Opening Price Clues – What Pre-Market Data Says Today
SEBI Approves Major Capital-Market Reforms
The Securities and Exchange Board of India (SEBI) on September 24, 2026, approved a broad package of regulatory reforms covering foreign portfolio investors, portfolio managers, settlement proceedings, research analysts, advertising norms, accredited investors, REITs, InvITs and market infrastructure.
The two developments likely to draw the most immediate attention are the broader FPI access to commodity derivatives and the new Portfolio Managers Route for Investing in Mutual Fund Units (PRIM) with a ₹25 lakh minimum investment.
For markets, however, the important distinction is between regulatory approval and actual market impact. The board has cleared the framework, but operational rules, notifications and exchange-level implementation will determine when and how participants can use the new routes.
FPIs Get Wider Access to Non-Agricultural Commodity Derivatives
The biggest market-access change is the decision to allow FPIs to participate in a broader range of non-agricultural commodity derivatives.
Under the approved framework, FPIs will be permitted to participate in non-agricultural index derivative contracts irrespective of whether the underlying contracts are cash-settled or non-cash-settled. They will also be permitted to participate in non-cash-settled non-agricultural commodity derivative contracts.
Earlier, FPI participation was largely limited to cash-settled non-agricultural commodity contracts and relevant non-agricultural commodity indices. The August 11, 2026 SEBI consultation paper had proposed expanding access to physically settled non-agricultural commodity derivatives.
The reform is particularly relevant for segments linked to bullion, energy and base metals, where wider institutional participation could potentially improve liquidity and hedging activity.
ALSO READ: SEBI’s New FPI Rule Could Leave Brokers Holding the Bag on Commodity Trades
Can FPIs Take Physical Commodity Delivery?
Not directly.
SEBI has widened trading access, but it has also retained safeguards to ensure FPIs do not become part of the physical-delivery obligation for non-cash-settled contracts.
FPIs will have to exit their positions before the delivery obligation arises, with arrangements required with their trading member or trading-cum-clearing member for handling positions approaching delivery.
Earlier consultation-stage proposals had focused on a three-day delivery-period safeguard. For the final article, the safer description is that the approved framework requires positions to be exited before the delivery obligation, while the precise operational mechanics will depend on the final regulations and circulars.
That distinction matters. The reform is intended to expand access to commodity derivatives without creating a direct physical-delivery route for overseas investors.
What Happens to Residual FPI Positions?
The framework provides for arrangements between the FPI and its trading member or trading-cum-clearing member to deal with positions that remain open as the contract approaches delivery.
This gives the market a defined mechanism for handling residual positions rather than leaving delivery obligations unresolved.
Why Traders Should Care About Wider FPI Access
The immediate signal is broader institutional participation.
More foreign participation could increase trading depth and hedging activity in eligible commodity contracts. But regulatory access does not automatically mean large foreign inflows on day one.
Actual participation will depend on factors such as contract liquidity, trading costs, hedging demand, exchange rules and operational comfort with the delivery safeguards.
That creates an important expectation gap: the regulatory door opens today, but actual foreign participation and liquidity gains could take time to emerge.
₹25 Lakh PMS Route: What Exactly Has Changed?
SEBI has also approved a new Portfolio Managers Route for Investing in Mutual Fund Units (PRIM).
The route is designed for portfolio-management strategies investing in direct mutual-fund schemes, including ETFs, index funds and specialised investment funds. The minimum investment under PRIM is ₹25 lakh.
One clarification is important: ₹25 lakh is not a blanket reduction in the minimum investment requirement for every conventional PMS product.
The ₹25 lakh threshold belongs specifically to the new PRIM framework.
Portfolio managers offering PRIM must have a minimum net worth of ₹2 crore. The framework also includes a 25% prudential cap on investments in schemes of affiliated, group or associate asset-management companies, while fixed management fees are capped at 1% of client AUM.
ALSO READ: SEBI Board Meeting: Advertising Code, PMS Reforms and REIT Fundraising Rules on Table
Why the ₹25 Lakh PRIM Route Matters
The new structure could widen the addressable market for professionally managed mutual-fund portfolios while keeping conventional PMS as a separate category.
SEBI’s consultation-stage data indicated that PMS assets under management had risen to ₹42.61 lakh crore as of May 31, 2026, from ₹18.07 lakh crore in April 2019. The number of registered portfolio managers had also increased to 515.
That means PRIM arrives after substantial expansion in the broader portfolio-management industry.
The market will now watch whether the new route attracts genuinely new assets or encourages investors and managers to shift from existing wealth-management products.
PMS Rules Get a Wider Investment Universe
SEBI has approved the SEBI (Portfolio Managers) Regulations, 2026, replacing the existing 2020 framework.
The revised rules expand the investment universe for portfolio managers to include areas such as:
Overseas securities: Greater flexibility for international investments, subject to the applicable foreign-exchange and regulatory conditions.
IPOs and to-be-listed securities: Portfolio managers will have access to selected primary-market opportunities.
Primary debt: The framework permits wider participation in primary debt issuance.
Investment-grade unlisted debt: Specified discretionary PMS portfolios can invest in eligible unlisted debt within the prescribed framework.
Exchange-traded derivatives: Portfolio managers get greater flexibility in using exchange-traded derivative products.
Mutual-fund portfolios: PRIM provides a separate route for managed investments in direct mutual-fund schemes.
The important point is that these are expanded avenues, not unrestricted permissions. Product-specific conditions and the applicable foreign-exchange framework continue to apply.
Track Live: Gap Up / Gap Down Stocks – Today’s NSE Opening Gaps
Independent Fund Managers: A New PMS Operating Model
One of the more structural changes is the introduction of Independent Fund Managers (IFMs).
An IFM can manage and operate client portfolios under the umbrella of a SEBI-registered portfolio manager, while the registered portfolio manager retains regulatory responsibility for activities carried out within the framework.
Orders generated by IFMs are required to flow through the registered portfolio manager’s infrastructure, while fees are routed through the registered portfolio manager.
Clients will also have an exit option if the relevant IFM leaves or is terminated.
The model could reduce the infrastructure burden for independent investment managers, but it also makes oversight and accountability across multiple managers more important.
Smaller PMS Managers Get Compliance Relief
SEBI’s PMS reforms also address operational requirements affecting smaller portfolio managers.
The framework provides relief around dedicated dealing-room requirements for portfolio managers with fewer than 10 clients or AUM below ₹100 crore, subject to adequate audit trails and internal controls.
The broader direction is toward differentiating essential market-integrity requirements from operational rules that may impose relatively high costs on smaller businesses.
Settlement Rules Get a New Framework
SEBI has also approved the SEBI (Settlement of Administrative and Civil Proceedings) Regulations, 2026, replacing the 2018 settlement framework.
The revised framework introduces a more formula-based methodology for determining settlement amounts.
The base amount will be linked to the applicable minimum penalty, while aggravating and mitigating factors can affect the final amount. Wrongful gains and investor losses are treated separately through disgorgement, rather than being counted twice in the base settlement calculation.
SEBI has also approved a fast-track settlement mechanism for specified cases involving settlement amounts of up to ₹10 lakh. Same-day reports also highlighted the fast-track route for eligible disclosure-related violations.
The revised framework is aimed at making proceedings more structured and predictable while retaining deterrence.
Accredited Investor Framework Expanded
SEBI has approved a wider accredited-investor framework that includes a route based on ₹5 crore of securities-market assets.
The framework also provides for manager-led accreditation, with accreditation remaining valid for three years for products managed by the same manager or group under the prescribed framework.
An earlier SEBI estimate suggested that around 3.7 lakh investors could potentially qualify under the ₹5 crore securities-market-asset criterion, based on April 30, 2026 data. That figure is an estimate of potential eligibility, not a current count of newly accredited investors.
REITs and InvITs Get a New Overseas Fundraising Route
SEBI has also approved a framework allowing REITs and publicly listed InvITs to issue Depository Receipts against their units.
The mechanism can create another route for attracting overseas capital through an IFSC-linked depository-receipt structure.
Fresh DRs can be backed by new units, while existing units can also be transferred under the prescribed framework.
The board has also approved changes to the voting threshold for specified matters to 75% of votes cast, rather than 75% of all outstanding units. REITs and InvITs can also take minority stakes in specified under-construction third-party projects within prescribed limits.
The DR framework should be viewed as an enabling route. It does not mean a large foreign fundraise will automatically happen.
Gold and Silver Bullion Enter a Wider Vault Framework
SEBI has expanded the scope of the Vault Managers Regulations beyond Electronic Gold Receipts.
The revised framework will cover physical bullion underlying products including gold and silver ETFs and bullion derivatives.
The minimum net-worth requirement for vault managers will rise from ₹50 crore to ₹75 crore, alongside stronger requirements covering security, insurance, audit, reconciliation and risk management.
The change becomes increasingly relevant as bullion-linked financial products expand beyond traditional gold-related structures.
Research Analysts Get Relief on Institutional Communications
SEBI has approved a relaxation of mandatory call-recording requirements for research analysts and research entities dealing with institutional investors.
The requirement to maintain verifiable records such as emails, SMS and other communications remains.
The relief does not apply in the same way to retail-investor communications, keeping a stronger compliance framework around retail interactions.
This is another example of SEBI moving toward more risk-based compliance across institutional and retail market activity.
Common Advertising Code Approved
SEBI has also approved a common advertising code for certain regulated entities.
The objective is to replace overlapping entity-specific requirements with a more uniform advertising framework. Certain prior-approval requirements will be removed, while advertisements involving celebrity endorsements will remain subject to the applicable approval conditions.
The framework also introduces a more streamlined post-publication reporting approach for applicable advertisements.
At the same time, requirements around fair and non-misleading investor communication remain.
AIF, NCD and Other Market Reforms
The September 24 package also includes measures affecting Alternative Investment Funds, first-time NCD issuers, certification requirements and other intermediary-level compliance rules.
Among the debt-market changes, first-time NCD issuers receive relief from mandatory retrospective listing of previously issued unlisted NCDs, while future issuances continue to be subject to mandatory listing requirements under the revised framework.
These measures may attract less immediate trading attention than the FPI and PMS decisions, but together they make September’s Board meeting a broad market-structure reform package rather than a single-rule change.
What SEBI’s Reforms Mean for Markets
The September 24 decisions broadly fall into three themes.
Access is widening. FPIs receive a larger commodity-derivatives universe, while PMS managers get more investment options.
Market structures are becoming more flexible. PRIM creates a new ₹25 lakh managed-mutual-fund route, Independent Fund Managers create a new PMS operating model, and REITs and InvITs receive a new foreign-capital channel through depository receipts.
Compliance is being recalibrated. Research analysts, advertisers, smaller PMS managers and certain debt issuers receive targeted relief, while settlement proceedings move toward a more structured framework.
But regulatory approval should not be confused with immediate market impact.
For commodities, the key question is whether overseas institutions actually begin using the newly permitted contracts and whether that results in measurable changes in volume, open interest and liquidity.
For PMS, investors will watch whether PRIM brings new money into professionally managed mutual-fund portfolios or mainly shifts assets from existing products.
For REITs and InvITs, the new DR framework creates an additional option for raising overseas capital, but execution will still depend on investor demand and pricing.
The Expectation Gap: Approval Today, Impact Later
The most important distinction for market participants is Board approval versus implementation.
SEBI has approved the reforms, but the practical rollout depends on subsequent regulations, notifications, circulars and implementation requirements.
That means the headline impact can appear immediate while the economic and trading impact takes longer to develop.
For the FPI commodity framework, traders should watch for the exchange-level operating rules and contract eligibility.
For PRIM and the wider PMS overhaul, the focus will shift to implementation details, onboarding requirements and whether portfolio managers actually launch products under the new route.
In other words, the next catalyst is no longer the proposal. It is the implementation.
What Traders Should Watch Next
The most important follow-through points are likely to be:
Commodity derivatives: Eligible contracts, exchange circulars, FPI onboarding and any changes in volume or open interest.
PMS: PRIM launches, ₹25 lakh portfolio adoption, new product offerings and changes in PMS asset flows.
Foreign capital: Whether the REIT/InvIT depository-receipt framework translates into actual overseas fundraising.
Market infrastructure: Implementation of the wider vault-manager framework covering bullion-linked products.
READ NEXT: Tata Sons Listing Row Deepens as Trusts Question RBI Talks; AGM Faces Fresh Hurdle