Hindustan Zinc earned about Rs 70 crore a day in the September quarter and lowered its FY27 zinc cost guidance. The stock is still about 26% below its 52-week high, so here is what the numbers say and what the market may be pricing in.
Rs 70 Crore a Day: The Headline Numbers
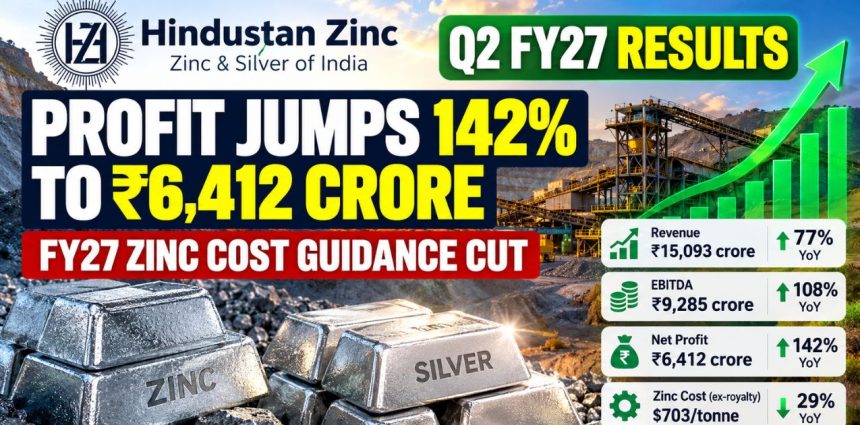
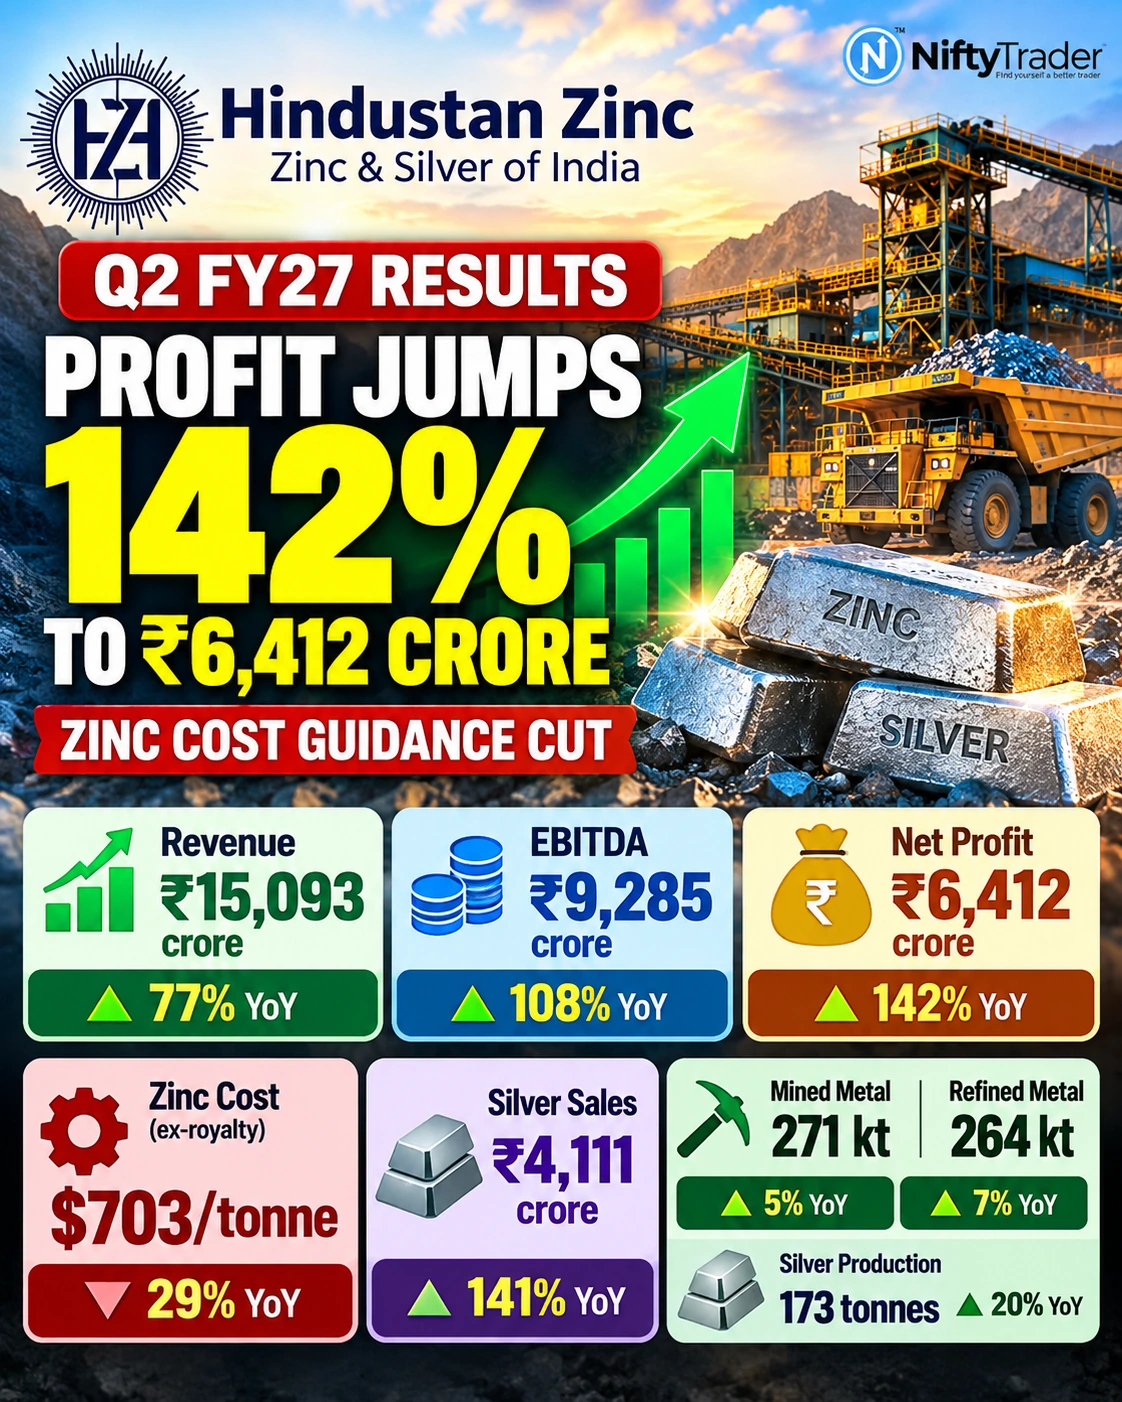
Hindustan Zinc earned roughly Rs 70 crore in net profit on every day of the July-September quarter (NiftyTrader calculation). The Vedanta Group company reported a 142% jump in net profit to Rs 6,412 crore for Q2 FY27, from Rs 2,649 crore a year earlier. Revenue from operations rose 77% to Rs 15,093 crore from Rs 8,549 crore, and EBITDA more than doubled to a record Rs 9,285 crore. The EBITDA margin was 62%, about 900 basis points above a year ago.
Costs lagged far behind sales. Total expenses rose 31.5% to Rs 6,895 crore, against revenue growth of 76.5%, and net profit margin widened to 42% from 31%.
The result also beat the pre-earnings mood. A Mint report on Motilal Oswal’s preview said the brokerage expected profit after tax to rise about 106% year-on-year and warned that production cost could increase. On that estimate, profit would have been near Rs 5,450 crore, so the actual number came in roughly 17% higher (NiftyTrader calculation).
Q2 FY27 at a Glance
| Metric | Q2 FY27 | Q2 FY26 | Change |
|---|---|---|---|
| Revenue (Rs crore) | 15,093 | 8,549 | +77% |
| EBITDA (Rs crore) | 9,285 | 4,467 | +108% |
| EBITDA margin | 62% | 52% | up ~900 bps |
| Net profit (Rs crore) | 6,412 | 2,649 | +142% |
| Net profit margin | 42% | 31% | +11 pts |
| Zinc cost (ex-royalty) | $703/t | $994/t | -29% |
| Mined metal | 271 kt | 258 kt | +5% |
| Refined metal | 264 kt | 246 kt | +7% |
| Silver | 173 t | 144 t | +20% |
Source: company results and investor presentation.
For the first half, revenue rose 77% to Rs 28,840 crore, EBITDA rose 108% to Rs 17,359 crore and net profit climbed 143% to Rs 11,881 crore.
Track Live: HINDUSTAN ZINC Option Chain (NSE) — Live OI, PCR & Greeks
Costs Fall 29%, and Guidance Comes Down
Prices helped, but cost is the bigger story. The zinc cost of production excluding royalty fell 29% to $703 per tonne. The company credited better mined grades, higher output, more renewable power and stronger by-product realisations, partly offset by weaker domestic coal usage and costlier input commodities. That is also a sharp step down from $851 per tonne in Q1.
According to a summary of the earnings call, management cut its full-year FY27 zinc cost guidance to $825-850 per tonne from $975-1,000. The old range had been left unchanged in July.
Read closely, the new range is not a promise that $703 will last. The first half averaged $776 per tonne, so a full-year figure of $825-850 implies second-half costs of about $875-925, assuming similar volumes in both halves (NiftyTrader calculation). That is roughly a quarter to a third above Q2. It fits the caution in the Motilal Oswal preview.
The company has disclosed how much cost matters. Every $25 per tonne change in zinc cost moves annual EBITDA by Rs 225-250 crore. On that arithmetic, the $148 fall from Q1 is worth Rs 1,330-1,480 crore a year, if prices and volumes hold (NiftyTrader estimate).
Zinc cost of production, $ per tonne
| Quarter | Cost ($/tonne) | Change |
|---|---|---|
| Q2 FY26 | 994 | — |
| Q3 FY26 | 940 | -5.4% QoQ |
| Q4 FY26 | 903 | -3.9% QoQ |
| Q1 FY27 | 851 | -5.8% QoQ |
| Q2 FY27 | 703 | -17.4% QoQ |
Source: Company results and investor presentation. Percentage changes calculated by NiftyTrader.
Silver: From Side Metal to Profit Powerhouse
Silver sales revenue surged 141% to Rs 4,111 crore, while zinc revenue rose 54% to Rs 8,224 crore. Silver’s share of revenue rose to about 27% from 20% a year ago (NiftyTrader calculation). Silver output rose 20% to 173 tonnes, and silver contributed about 45% of first-half profitability. Jefferies pointed to firmer silver prices backed by demand for precious metals.
| Product revenue (Rs crore) | Q2 FY27 | Q2 FY26 | Change | Share of Q2 FY27 |
|---|---|---|---|---|
| Zinc | 8,224 | 5,354 | +54% | 54.5% |
| Silver | 4,111 | 1,706 | +141% | 27.2% |
| Others | 1,628 | 649 | +151% | 10.8% |
| Lead | 1,130 | 840 | +35% | 7.5% |
| Total | 15,093 | 8,549 | +77% | 100% |
Source: company investor presentation. Shares calculated by NiftyTrader.
The exposure runs both ways. Each $1 per ounce move in silver changes annual EBITDA by Rs 200-225 crore, and each $100 per tonne move in zinc changes it by Rs 725-750 crore.
Five Straight Quarters of Rising Profit
Net profit has risen sequentially for five consecutive quarters and now stands at 2.42 times its Q2 FY26 level (NiftyTrader calculation). Against Q1 FY27, when profit was Rs 5,469 crore on revenue of Rs 13,747 crore, Q2 profit is up about 17% and revenue about 10%.
| Quarter | Revenue | EBITDA | Net profit | EBITDA margin |
|---|---|---|---|---|
| Q2 FY26 | 8,549 | 4,467 | 2,649 | 52% |
| Q3 FY26 | 10,980 | 6,087 | 3,916 | 55% |
| Q4 FY26 | 13,544 | 7,706 | 5,033 | 57% |
| Q1 FY27 | 13,747 | 8,074 | 5,469 | 59% |
| Q2 FY27 | 15,093 | 9,285 | 6,412 | 62% |
All figures in Rs crore. Source: company filings and results releases.
Hindustan Zinc Quarterly Net Profit (₹ crore)
| Quarter | Net profit | Sequential growth |
|---|---|---|
| Q2 FY26 | 2,649 | — |
| Q3 FY26 | 3,916 | +47.8% |
| Q4 FY26 | 5,033 | +28.5% |
| Q1 FY27 | 5,469 | +8.7% |
| Q2 FY27 | 6,412 | +17.2% |
Source: Company filings and results releases. Sequential growth calculated by NiftyTrader.
Also Check: HINDUSTAN ZINC Options Chart | Nifty Trader
A Balance Sheet Turned Inside Out
On September 30, the company held gross investments and cash of Rs 17,439 crore against borrowings of Rs 6,171 crore. That implies a net cash of about Rs 11,270 crore (NiftyTrader calculation). The company also retains a CRISIL AAA rating.
A year earlier the picture was reversed. On September 30, 2025, it had net debt of Rs 2,547 crore, and by December 31, 2025, net cash of just Rs 329 crore. The swing is roughly Rs 13,800 crore in 12 months. Free cash flow before growth capex was Rs 6,389 crore in the quarter and Rs 11,642 crore in the first half.
Where the Cash Is Going
The company plans FY27 capex of about Rs 5,000 crore, with roughly 80% earmarked for projects already under way. The two big board-approved projects:
A 250,000 tonne per annum zinc expansion at Debari would lift refined capacity from 1.1 million to 1.4 million tonnes. It carries Rs 12,000 crore of approved investment and a Q2 FY29 target.
India’s first zinc tailings reprocessing plant, at 10 million tonnes a year, has Rs 3,823 crore approved and a Q4 FY28 target.
The company is also widening its metals mix. It secured a letter of intent for the Gundlupet Rare Earth Element and Yttrium Block in Karnataka. Renewables supplied 27% of power consumption in the quarter. The company paid Rs 13,027 crore to the national exchequer in the first half, including Rs 3,724 crore to Rajasthan.
The Market Tension: Profit Doubled, the Stock Did Not
Here is the puzzle. The stock closed at Rs 540 on Friday, October 16, down 8.85% in six months and up 6.59% over one year. Its 52-week high is Rs 733. At about Rs 2.3 lakh crore of market capitalisation, the stock trades near 11 times its last four quarters of profit, which total Rs 20,830 crore (NiftyTrader calculation). That is a simple market-cap-to-profit ratio, not the exchange-displayed P/E, which still reflects older quarters and should ease as Q2 is absorbed.
One reading is that investors are not paying for peak margins to last. The implied second-half cost rise and the sensitivity tables above support that caution. A second factor is share supply. In August, reports said the government was weighing a roughly 1.5% stake sale through an offer for sale, worth Rs 3,500-4,000 crore, and the shares fell nearly 3% that day. That was a media report, not a confirmed transaction.
The results came after market hours, with the earnings call scheduled for 4 pm IST. Tuesday’s session will be the first market verdict.
What to Watch Next
First, second-half costs. Can the company beat the roughly $875-925 per tonne that its new guidance implies?
Second, volumes. As of July, guidance stood at 1.1 million tonnes of refined metal and 680 tonnes of silver. The first half delivered 524 kt of refined metal and 321 tonnes of silver, about 48% and 47% of those targets (NiftyTrader calculation).
Third, new leadership. Amarendu Prakash succeeded Arun Misra as CEO from August 1, and this is the first set of results announced under him. He has said the focus will be disciplined growth, AI-led innovation and a bigger critical minerals portfolio.
Fourth, metal prices and the rupee. Each Rs 1 move in the rupee-dollar rate shifts annual EBITDA by Rs 325-350 crore.
Read Next: Adani Energy Solutions Q2 FY27 Results on Oct 22, Investor Call on Oct 23: What to Watch
Hindustan Zinc Q2 FY27: Quick Answers
What was Hindustan Zinc’s Q2 FY27 net profit?
Rs 6,412 crore, up 142% from Rs 2,649 crore in Q2 FY26.
What was the EBITDA margin?
62%, up about 900 basis points from a year ago.
Why did profit grow faster than revenue?
Zinc cost of production fell 29% to $703 per tonne while silver output and prices lifted revenue. Expenses rose 31.5% against 77% revenue growth.
Did the company change its FY27 guidance?
According to the earnings-call summary, FY27 zinc cost guidance was cut to $825-850 per tonne from $975-1,000.
Was a dividend announced with the Q2 results?
The results announcement did not mention a new dividend. The last payout was Rs 11 per share, announced in April, a yield of about 2%.
Disclaimer: This article is for information only and is not investment advice. Commodity-linked earnings are volatile. Consult a SEBI-registered adviser before acting.