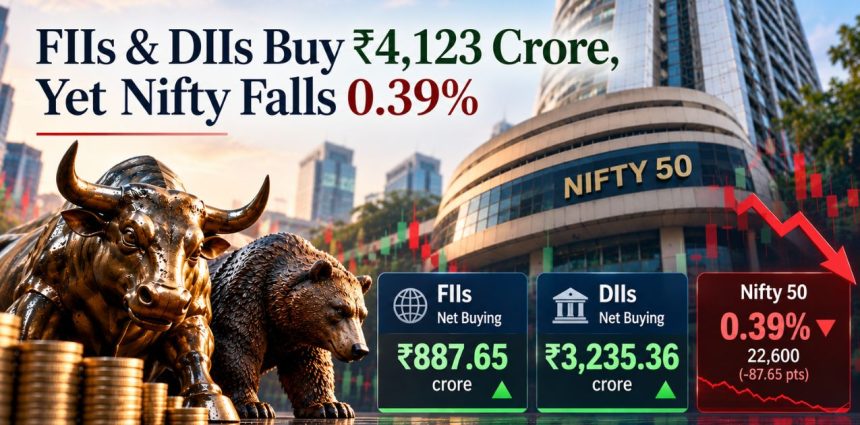
Foreign institutional investors (FIIs) turned net buyers of Indian equities on October 23, purchasing ₹887.65 crore, while domestic institutional investors (DIIs) bought ₹3,235.36 crore. However, the Nifty 50 fell 87.65 points, or 0.39%, to close at 22,600, extending its losing streak to four sessions. The disconnect between institutional cash buying and market weakness highlights how geopolitical risk-off sentiment and rising crude oil prices can outweigh support from domestic investors.
The combined net buying by FIIs and DIIs reached ₹4,123.01 crore during Friday’s session, according to provisional exchange cash-market data. Yet the broader market suffered heavier losses: the Nifty Midcap 100 fell 2.21%, while the Nifty Smallcap 100 declined 2.94%. India VIX, a gauge of expected market volatility, rose 6.31% to 16.76.
Friday’s inflow improved the daily FII picture, but it does not establish that foreign investors have returned to sustained buying. NiftyTrader’s FII-DII dashboard provides additional context: FIIs remained net short in index futures even as they bought equities in the cash market.
Need to Know
- FII cash flows: Net buying of ₹887.65 crore on October 23, reversing the previous session’s net selling of ₹3,458.70 crore.
- DII cash flows: Net buying of ₹3,235.36 crore, taking combined institutional net buying to ₹4,123.01 crore.
- October flows: FIIs remained net sellers by approximately ₹51,466 crore, while DIIs were net buyers of approximately ₹59,110 crore through October 23.
- Market performance: The Nifty 50 fell 0.39%, while midcap and smallcap indices declined more sharply.
- Derivative positioning: FIIs continued to hold a substantial net short position in index futures, cautioning against interpreting one positive cash-flow session as a confirmed reversal.
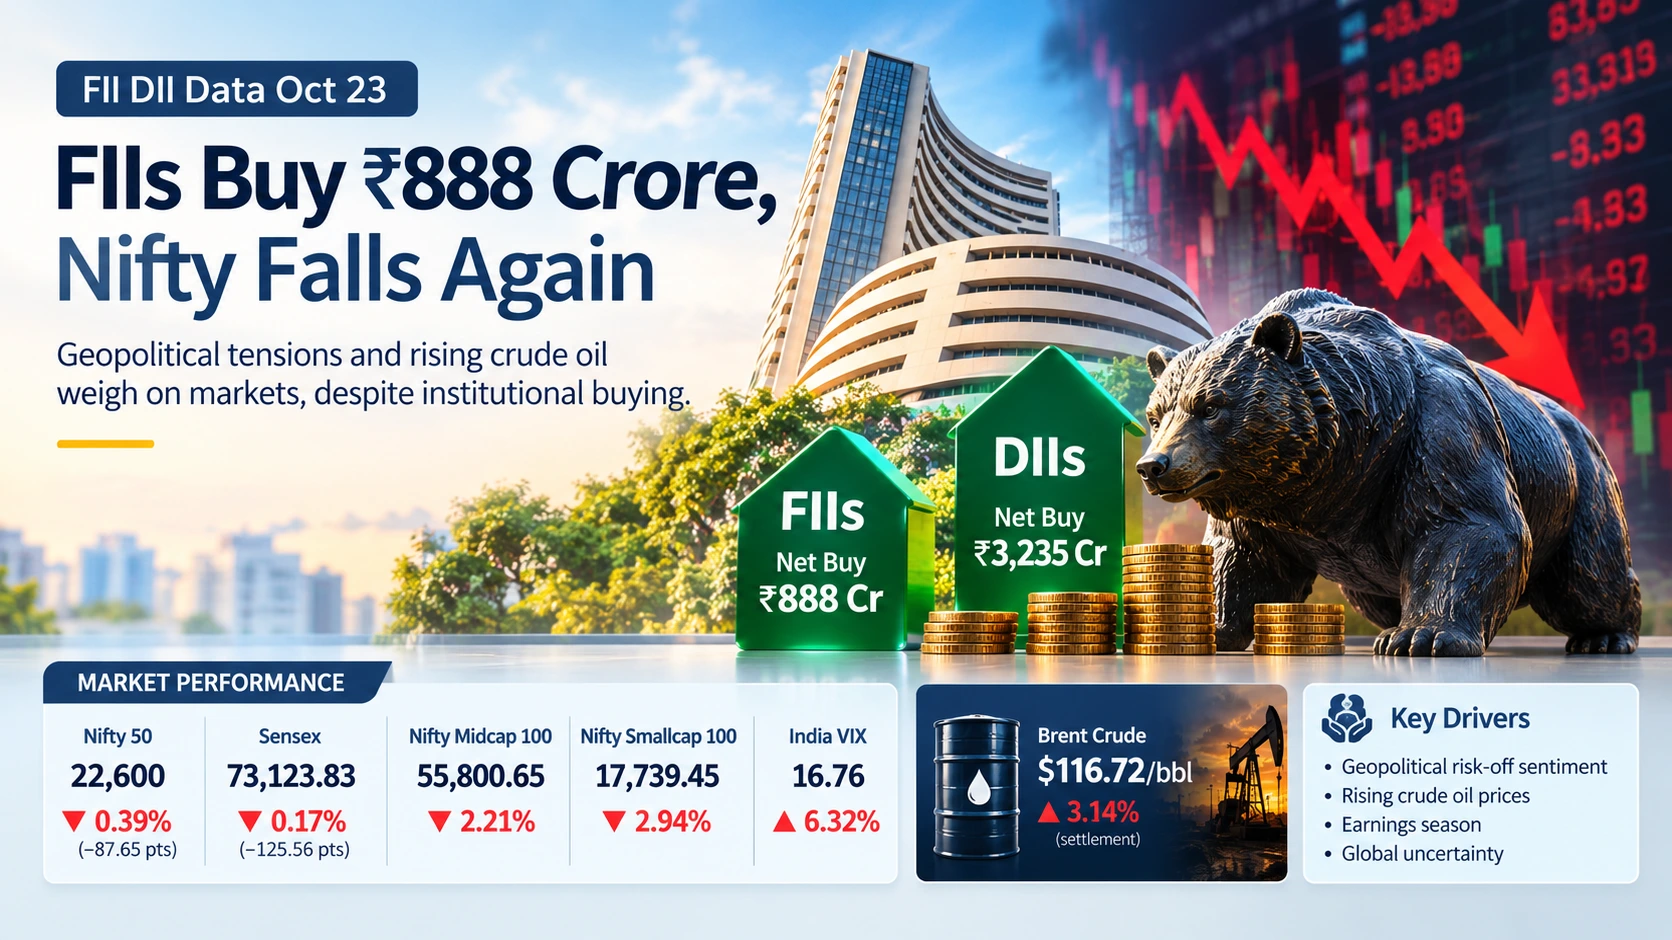
FII-DII Data on October 23: Complete Cash-Market Breakdown
The provisional figures show that both foreign and domestic institutions bought more shares than they sold during the session.
| Institutional activity | FIIs (₹ crore) | DIIs (₹ crore) |
|---|---|---|
| Gross purchases | 14,445.54 | 19,232.31 |
| Gross sales | 13,557.89 | 15,996.95 |
| Net buying | 887.65 | 3,235.36 |
NiftyTrader calculation: Combined gross purchases stood at ₹33,677.85 crore, compared with gross sales of ₹29,554.84 crore. This produced combined net buying of ₹4,123.01 crore.
DIIs’ net buying was approximately 3.6 times the day’s FII net inflow. However, these are cash-market figures, not a complete measure of institutional exposure across futures and options.
October FII Selling Remains Substantial Despite Friday’s Buying
Friday’s inflow improved the daily picture but did not erase the month’s accumulated foreign selling.
| October cash-market flows through October 23 | Net flow |
|---|---|
| FII/FPI | −₹51,466.38 crore |
| DII | +₹59,110.32 crore |
| Combined net flow | +₹7,643.94 crore |
Figures are provisional and cover October trading through October 23.
The monthly totals show that domestic institutions have more than offset net foreign selling in the cash market. DIIs’ cumulative net buying was approximately 115% of FII net selling, leaving combined institutional flows positive by ₹7,643.94 crore.
This distinction matters: persistent DII buying can absorb foreign selling, but it does not guarantee that benchmark or broader-market indices will rise. Prices also reflect the urgency of orders, sector-specific selling, derivatives positioning, earnings expectations and global risk appetite.
Foreign investors had been net sellers in most October sessions, with buying seen on October 16, October 21 and October 23. The October 23 inflow was a positive daily development but not yet evidence of a sustained change in behaviour.
What NiftyTrader’s 30-Session Data Reveals
A longer lookback helps separate a one-day improvement from the prevailing trend.
| NiftyTrader rolling 30-session indicator | Reading |
|---|---|
| FII net cash-market flow | −₹98,010 crore |
| DII net cash-market flow | +₹1,14,657 crore |
| Sessions with FII net selling | 25 out of 30 |
| DII buying as a share of FII selling | Approximately 117% |
Source: NiftyTrader’s FII-DII dashboard; rolling-period figures are separate from October-to-date totals.
The 30-session figures show that foreign selling has remained persistent even as domestic institutional buying has been substantial. The figures are consistent with a market in which domestic capital is providing an offset, rather than one in which foreign investors have decisively returned to sustained buying.
FII Cash Buying Versus Futures Positioning
NiftyTrader’s participant-wise open-interest dashboard showed FIIs with a net short position of 2,80,183 index-futures contracts at the end of October 23.
| FII positioning indicator | October 23 reading |
|---|---|
| Index-futures long contracts | 36,986 |
| Index-futures short contracts | 3,17,169 |
| Net index-futures position | −2,80,183 contracts |
The negative net position indicates that short contracts substantially outnumbered long contracts in this segment. It does not, by itself, prove that FIIs expect an immediate market decline: futures positions can reflect hedging as well as directional views.
Still, the divergence between positive cash-market flows and a heavily net-short index-futures position is worth monitoring. A sustained shift would require evidence from subsequent cash-flow sessions and changes in derivative positioning, rather than a single day’s buying alone.
Geopolitical Risk-Off Sentiment and Rising Crude Weighed on Equities
Market reports attributed Friday’s broader sell-off to escalating geopolitical tensions in West Asia and rising crude oil prices, which heightened concerns about inflation and corporate earnings. Brent crude futures traded around $114 a barrel amid energy-supply concerns following Houthi attacks on Saudi Arabia. Reuters’ market report linked the oil surge and Middle East tensions to the weakness in Indian equities.
| Market indicator | October 23 close | Daily change |
|---|---|---|
| Nifty 50 | 22,600.00 | −87.65 points (−0.39%) |
| Sensex | 73,123.83 | −125.56 points (−0.17%) |
| Nifty Midcap 100 | 55,800.65 | −2.21% |
| Nifty Smallcap 100 | 17,739.45 | −2.94% |
| India VIX | 16.76 | +6.31% |
The gap between benchmark and broader-market performance was particularly notable. The midcap and smallcap indices fell much more sharply than the Nifty 50, while the rise in India VIX indicated increased uncertainty about near-term price movements.
The broader risk-off environment helps explain why institutional cash buying did not translate into gains. However, market movements cannot be attributed to a single factor with certainty. Earnings disappointments, liquidity conditions, individual-stock selling and derivatives activity may also have influenced prices.
Track Live: Nifty 50, Sensex, INDIA VIX
Crude Oil Adds Another Risk for Indian Equities
Energy prices remained an important external risk. Brent crude futures were trading above $114 a barrel during Friday’s Indian market session and subsequently settled at $116.72 a barrel, up $3.55 or 3.14%, according to Reuters. This was the highest settlement since April 29.
The rise followed Houthi attacks in Saudi Arabia and renewed concern about possible disruptions to Middle Eastern energy supplies.
For India, a prolonged increase in crude prices can raise the import bill and add pressure to inflation, the rupee and energy-related input costs. These are potential transmission channels, not proof that crude alone caused Friday’s equity decline.
The combination of elevated crude prices, weak broader-market breadth and persistent foreign selling makes the outlook more complicated than the one-day FII inflow might suggest.
What Investors Should Watch Next Week
Three developments will help establish whether Friday’s buying marks a meaningful change in institutional behaviour.
1. Whether FII cash buying continues. A sequence of net-buying sessions would provide stronger evidence of a shift than one positive reading. The monthly and rolling 30-session totals remain negative for FIIs.
2. Whether futures positioning changes materially. A sustained reduction in FII net shorts alongside continued cash buying would offer a more constructive signal than a cash-market inflow in isolation. Futures exposure must still be interpreted in the context of hedging and other positions.
3. Whether market breadth improves as Q2 earnings arrive. The sharp underperformance of midcaps and smallcaps shows that institutional buying did not prevent broad selling. Upcoming earnings, crude prices and geopolitical developments could influence whether that weakness persists.
The main uncertainty is whether domestic buying will continue to cushion the market if foreign selling resumes, particularly if energy prices remain elevated.
Bottom Line
FIIs’ net purchase of ₹887.65 crore on October 23 was a welcome daily reversal, while DIIs continued to provide substantial support through cash-market buying. October’s combined institutional cash flow remained positive by ₹7,643.94 crore despite net FII selling.
However, the Nifty’s fourth consecutive decline, sharper losses in midcaps and smallcaps, rising volatility and FIIs’ sizeable net-short index-futures position argue against treating the inflow as a confirmed recovery signal. Geopolitical risk-off sentiment and higher crude prices remain important headwinds. The next few sessions should help determine whether foreign buying becomes more consistent or remains an isolated improvement within a broader period of selling pressure.
Read Next: Adani Power Q2 FY27 Results: Profit Up 142%, But Continuing EBITDA Rises Just 18.5%
Disclaimer: This article is for informational and educational purposes only and is not investment advice. Investments in securities markets are subject to market risks. Verify data independently before making investment decisions.