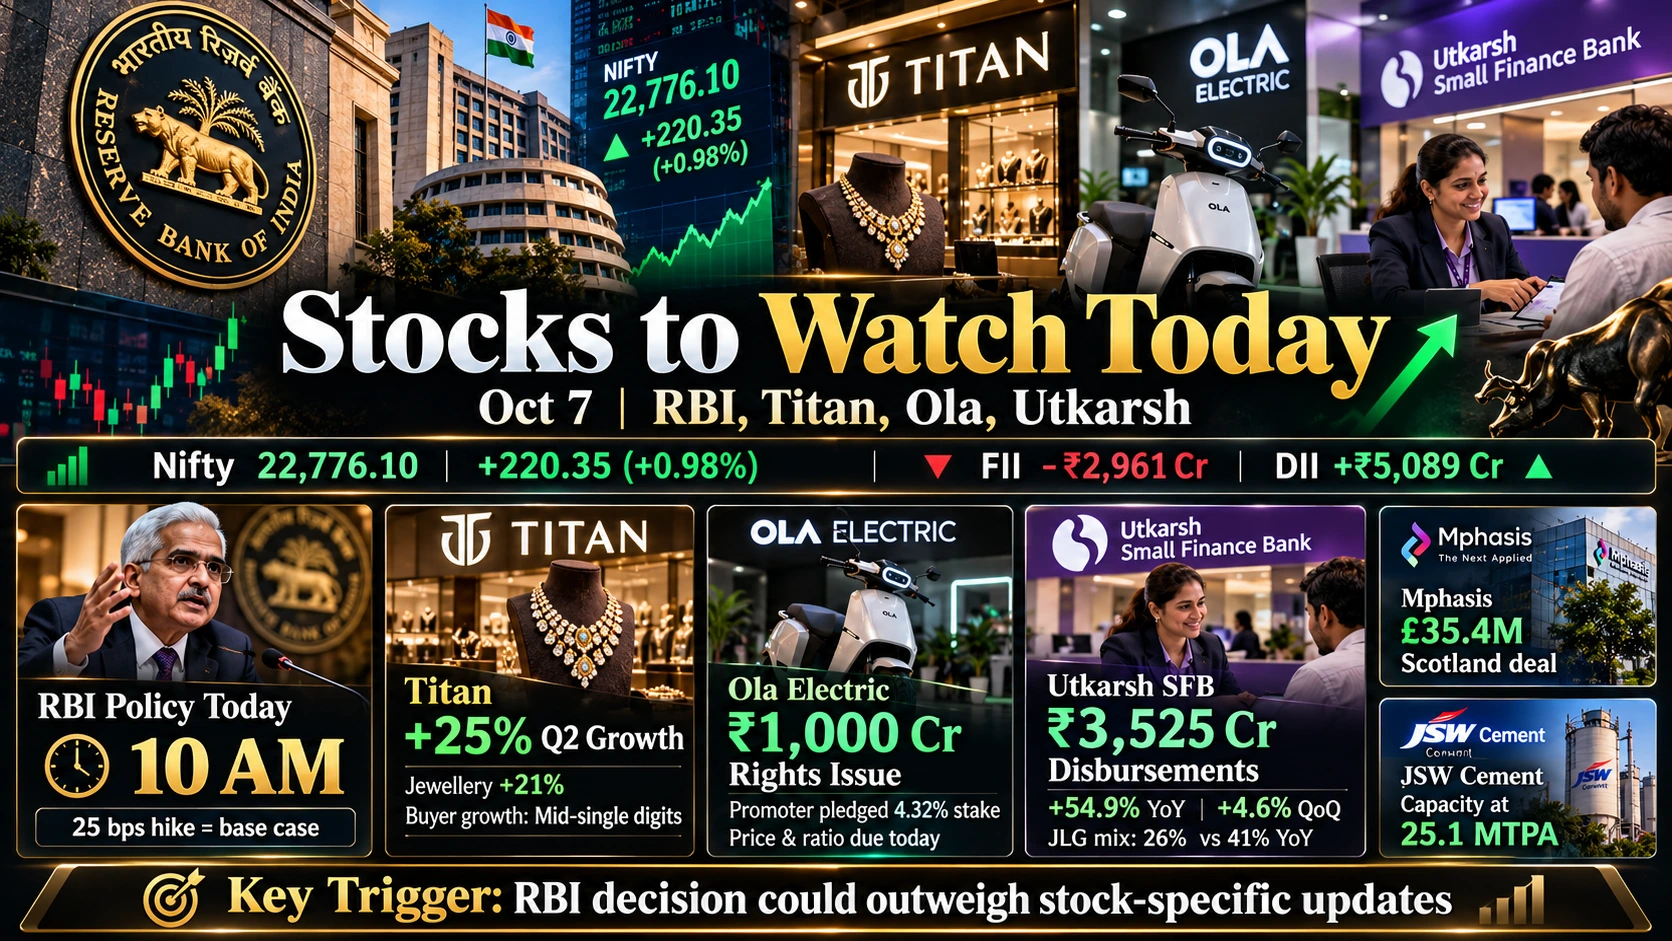
Titan’s 25% Q2 growth comes with a softer buyer-growth signal, Ola Electric will set key terms for its ₹1,000 crore rights issue, and Utkarsh Small Finance Bank is rapidly changing its loan mix. But the RBI monetary policy decision at 10 AM remains the biggest trigger for Indian markets today.
Indian markets face a major test on Wednesday as the Reserve Bank of India announces its monetary policy decision, with investors also tracking fresh company-specific triggers in Titan, Ola Electric, Utkarsh Small Finance Bank, Mphasis, JSW Cement and other stocks.
The Nifty 50 closed 220.35 points, or 0.98%, higher at 22,776.10 on October 6, while the Sensex gained 685.34 points to 73,067.81.
Yet the rebound has not been matched by foreign flows.
FIIs remained net sellers of ₹2,961.30 crore on Tuesday, while domestic institutional investors bought ₹5,088.92 crore.
Pre-market cues also remain cautious, with GIFT Nifty futures indicating a weaker start ahead of the RBI announcement.
That sets up the central market tension for October 7:
The index is attempting to recover, but foreign selling, the rupee and the RBI’s rate signal could decide whether the rebound has enough strength to continue.
Track Live: GIFT NIFTY, NIFTY50, SENSEX, FII DII DATA, INDIA VIX
Here are the stocks and triggers traders should watch today.
RBI Decision Today: 25-Bps Hike Is the Base Case, but Guidance Matters More
Before the individual stocks, the biggest market-wide event comes from the RBI.
A Reuters poll found that a majority of economists expect the central bank to raise the repo rate by 25 basis points from the current 5.25%, while derivatives pricing has also indicated a smaller possibility of a larger 50-bps move.
That means the market may be prepared for the headline rate increase.
The bigger surprise could come from what the RBI says next.
Investors will closely track Governor Sanjay Malhotra’s commentary on inflation, crude oil, the rupee, liquidity, economic growth and whether another rate increase could follow.
The rupee closed near ₹96.42 per US dollar on October 6, around a two-month low, while continued foreign equity outflows have added to pressure on Indian assets.
For banks, NBFCs, real estate companies, automobiles and other rate-sensitive stocks, the policy guidance could therefore matter as much as the rate decision itself.
1. Titan: 25% Growth Looks Strong, but Buyer Growth Tells a Different Story
Titan Company is one of the most important stocks to watch today after its Q2 FY27 business update showed around 25% year-on-year growth across consumer businesses.
Domestic businesses grew 22%, while international operations increased 97%. Titan also added 78 net stores during the quarter, taking its consumer-store network to 3,758.
Jewellery grew around 21%, watches rose 30% and EyeCare increased 28%.
Those are strong headline numbers.
But one detail underneath the jewellery growth may matter more to investors.
Buyer growth remained in the mid-single digits, while average ticket sizes increased at a double-digit rate.
In other words, spending per customer grew much faster than the number of customers buying jewellery.
That creates an important distinction.
Titan can generate strong value growth when gold prices, product mix and premiumisation push ticket sizes higher, even if customer additions are more moderate.
But sustainable growth becomes more convincing if both the number of buyers and spending per customer expand together.
The festive calendar adds another layer.
Titan said demand remained healthy through much of the quarter but moderated toward the end as part of the festive season shifted into Q3.
That makes the December quarter particularly important.
If festive demand brings more customers into stores, the softer buyer-growth number may prove mainly a timing issue.
If buyer additions remain modest while ticket-size growth continues to do most of the work, investors may start questioning how broad-based the underlying jewellery demand really is.
Titan’s 97% international growth also requires context, as it includes Damas Jewellery following consolidation.
What traders should watch: buyer growth, festive demand, average ticket sizes, jewellery volumes and whether Titan’s expanding store network translates into broader customer growth.
Also Read: Titan Q2 FY27: Growth Moderates to 25% From 41% as Jewellery Buyers Lag
2. Ola Electric: ₹1,000 Crore Rights Issue Meets a 4.32% Promoter Pledge
Ola Electric Mobility could see elevated attention as its board prepares to determine key terms for a rights issue of up to ₹1,000 crore.
The company has already received in-principle approvals, but the most important variables are still ahead.
The board is expected to determine the issue price, entitlement ratio, record date and payment structure.
There is also an important promoter angle.
Ola Electric promoter Bhavish Aggarwal has pledged a 4.32% stake in the company to fund his participation in the rights issue.
The company has said the pledge is solely for subscribing to the issue, that no shares are being sold, and that the promoter will participate alongside other shareholders on the same terms.
That adds another dimension to the fundraising story.
Promoter participation signals an intention to maintain exposure to the company, but investors will still focus heavily on how the rights issue is priced and structured.
A deeply discounted issue could improve subscription prospects but create a different dilution equation for shareholders who do not participate.
The fundraising also comes after Ola Electric raised ₹780 crore through a QIP earlier this year.
The key question is therefore no longer simply whether Ola can raise additional capital.
It is what the capital costs shareholders and whether it ultimately translates into stronger operations, cash flows and market position.
What traders should watch: rights-issue price, entitlement ratio, payment terms, promoter participation and how the fresh capital will be used.
3. Utkarsh SFB: 55% YoY Growth Looks Very Different on a Quarterly Comparison
Utkarsh Small Finance Bank reported one of the strongest headline growth numbers in the latest business updates.
Q2 FY27 disbursements rose 54.9% year on year to ₹3,525 crore, compared with ₹2,275 crore in the same quarter last year.
But there is another number investors should not ignore.
Disbursements were around ₹3,370 crore in Q1 FY27, meaning sequential growth was only about 4.6%.
That does not weaken the annual improvement.
It changes the interpretation.
The more important story may actually be happening inside the loan book.
Non-JLG disbursements surged 94.2% year on year, while the bank continues to reduce its exposure to the joint-liability-group segment.
The gross loan portfolio stood at ₹20,063 crore, up 7.5% year on year.
The mix has changed sharply.
JLG loans represented around 26% of the portfolio, compared with 41% a year earlier, while non-JLG loans accounted for roughly 74%.
That is a substantial strategic shift.
Moving toward a more diversified portfolio could reduce dependence on microfinance-style lending.
But faster growth outside JLG also creates a new test:
Can Utkarsh scale these businesses while keeping credit costs and asset quality under control?
Deposits increased 6.6% year on year to ₹23,869 crore.
The CASA ratio stood at 21.5%, higher than 20.9% a year earlier but below the 22.1% reported in June.
The bank also reported a liquidity coverage ratio of 176%.
These are provisional business numbers, so profitability and asset-quality trends will remain important when detailed results arrive.
What traders should watch: non-JLG growth, asset quality, credit costs, deposits and whether diversification translates into sustainable profitability.
4. Mphasis: £35.4 Million Deal Is Important, but It Is an Extension
Mphasis has signed an agreement worth approximately £35.4 million with Social Security Scotland to support and maintain its core benefits-management platform.
The system supports benefit services used by more than 2 million people.
The contract value is meaningful, but investors should note an important distinction:
This is an expansion of an existing relationship rather than an entirely new customer acquisition.
That makes the deal particularly relevant as a measure of account stickiness.
Winning additional work from an existing government client can indicate confidence in delivery and provide recurring revenue visibility.
But the full contract value should not automatically be treated as near-term incremental revenue.
For Mphasis, the larger question remains whether its deal pipeline converts into faster organic growth as clients navigate discretionary technology spending and AI-led changes.
What traders should watch: incremental revenue contribution, large-deal conversion and growth across major accounts.
5. JSW Cement: New Capacity Is Operational—Now Utilisation Becomes the Test
JSW Cement has successfully commissioned an additional 1 MTPA grinding unit at Nagaur in Rajasthan.
The addition takes Nagaur’s grinding capacity from about 2.5 MTPA to 3.5 MTPA and lifts JSW Cement’s total installed grinding capacity to 25.1 MTPA.
This matters because the development is no longer simply a future capacity announcement.
The unit has been commissioned.
That shifts the investment question from construction to execution.
How quickly can JSW Cement ramp up utilisation?
Can the new capacity generate stronger volumes in North India?
And can those additional volumes be achieved without sacrificing pricing and margins?
Nagaur also represents an important part of the company’s northern expansion strategy.
What traders should watch: capacity utilisation, regional volumes, pricing and the margin contribution from the additional grinding capacity.
6. HCLTech: ₹500 Crore Lucknow Plan Needs One Important Distinction
HCLTech is in focus after developments related to AI skilling and expansion in Lucknow.
HCLTech has announced an initiative to train 1,000 students across Uttar Pradesh in AI and related technologies during FY27.
Separately, HCL Group has announced a planned ₹500-crore expansion of HCL IT City in Lucknow.
The proposed expansion could add up to 9.5 lakh sq ft of capacity for around 4,500 technology professionals.
But investors should avoid interpreting the announcement incorrectly.
The ₹500 crore commitment has been attributed to HCL Group, not specifically as ₹500 crore of immediate HCLTech capex.
That makes the announcement strategically relevant to HCLTech’s talent and delivery ecosystem without necessarily producing a direct ₹500-crore listed-company earnings or capital-expenditure trigger.
For HCLTech shareholders, the more immediate focus will remain on upcoming results, deal conversion, revenue growth and margins.
What traders should watch: AI-related demand, capacity utilisation, hiring and expectations ahead of HCLTech’s Q2 earnings.
7. Adani Ports: Paradip Subsidiary Is an Execution Step, Not Another 18 MMT Award
Adani Ports and Special Economic Zone has incorporated Paradip Mahanadi Terminal Ltd as a wholly owned subsidiary for the development and operation of two dry-bulk berths at Paradip Port in Odisha.
The incorporation is new.
The underlying project award is not.
APSEZ had already received the Letter of Award in September for the CQ-I and CQ-II berths.
The project carries a 30-year concession and will add 18 million tonnes per annum of mechanised dry-bulk capacity.
That will take APSEZ’s capacity portfolio to around 671 MMT per annum.
The latest subsidiary formation should therefore be viewed primarily as an execution milestone for the previously announced project, rather than a fresh additional 18 MMT capacity win.
That distinction helps investors avoid double-counting the same project announcement.
What traders should watch: project execution, construction timelines, cargo ramp-up and the eventual contribution from Paradip.
More Stocks in Focus Today
Godrej Consumer Products
Godrej Consumer Products has inaugurated the first phase of its manufacturing facility in Indonesia’s Kendal Special Economic Zone, part of an investment of around IDR 500 billion.
The investment strengthens local manufacturing capacity, but the stock trigger will increasingly shift toward utilisation, Indonesia revenue growth and margins.
Granules India
Granules India plans to invest around ₹2,000 crore over the next three to four years across complex generics, oncology, peptide CDMO, manufacturing and R&D.
The strategy could move the company further up the pharmaceutical value chain, but eventual returns on the planned investment will matter more than the capex headline itself.
Apollo Tyres
Apollo Tyres said Gaurav Kumar ceased to be CFO and key managerial personnel at the close of business on October 6.
He had earlier stepped down from the company’s board while continuing as CFO during the transition period.
Investors will now watch for management continuity and the appointment of a successor.
Blue Dart Express
Blue Dart has announced a 9%–12% increase in domestic service prices from January 1, 2027, depending on the service and customer profile.
The key question is whether stronger pricing improves revenue realisation without materially affecting customer volumes.
Mahindra Lifespace Developers
Mahindra Lifespaces has launched Mahindra Rivenza in Pune, a 13.46-acre residential project carrying an estimated gross development value of around ₹3,500 crore.
Bookings and the pace of monetisation will matter more than headline GDV alone.
Asian Paints
Asian Paints’ board is scheduled to meet on October 29 to consider an interim dividend for FY27.
The company has set November 4, 2026 as the record date, subject to the board approving the dividend.
What Traders Should Watch After the RBI Decision
Today’s market could look very different before and after 10 AM.
For Titan, the most interesting question is not whether 25% consumer-business growth is strong—it clearly is—but whether customer additions can catch up with the increase in average spending.
For Ola Electric, the rights-issue price and entitlement ratio could matter more than the ₹1,000-crore headline.
For Utkarsh SFB, the real debate is whether rapid diversification away from JLG improves the quality and resilience of the loan book.
For Mphasis, investors should distinguish a valuable contract extension from an entirely new-client win.
For JSW Cement, the story has moved from capacity creation to utilisation.
And across the wider market, one question dominates:
Can domestic institutional buying continue to absorb persistent foreign selling if the RBI signals that monetary conditions may remain tighter for longer?
That could determine whether Tuesday’s Nifty rebound develops into something more durable.
Bottom Line
October 7 combines several meaningful stock-specific triggers with one major macro event.
Titan has delivered strong headline growth, but jewellery buyer additions deserve closer attention. Ola Electric is moving into the decisive pricing stage of its ₹1,000-crore rights issue, with promoter Bhavish Aggarwal pledging a 4.32% stake to participate. Utkarsh SFB is growing rapidly on a year-on-year basis while fundamentally changing its loan mix. Mphasis has strengthened an existing government relationship, while JSW Cement has added operational capacity in North India.
HCLTech and Adani Ports also have positive strategic developments, although both require careful interpretation of what is genuinely new.
The RBI decision may ultimately overshadow all of them.
If the central bank delivers the expected 25-bps hike, the market reaction could depend less on the hike itself and more on whether policymakers signal that further tightening is likely.
That makes October 7 a stock-picker’s session with a strong macro overlay.
The biggest share-price moves may come where the actual update differs most sharply from what investors had already priced in.
Read Next: SEBI CAS Update: 30-Minute VWAP May Return for Derivatives Settlement
Disclaimer: This article is for informational purposes only and does not constitute investment advice or a recommendation to buy or sell any security. Investments in securities are subject to market risks. Readers should conduct their own research and consult a qualified financial adviser where appropriate.