Sun Pharma Q2 FY27 Results on October 30: What Investors Should Watch
Sun Pharmaceutical Industries is approaching its September-quarter earnings announcement with several factors competing for investors’ attention. Growth in specialty medicines and domestic formulations could support revenue, but rising research spending, raw material costs and uncertainty surrounding its proposed Organon acquisition may influence market sentiment.
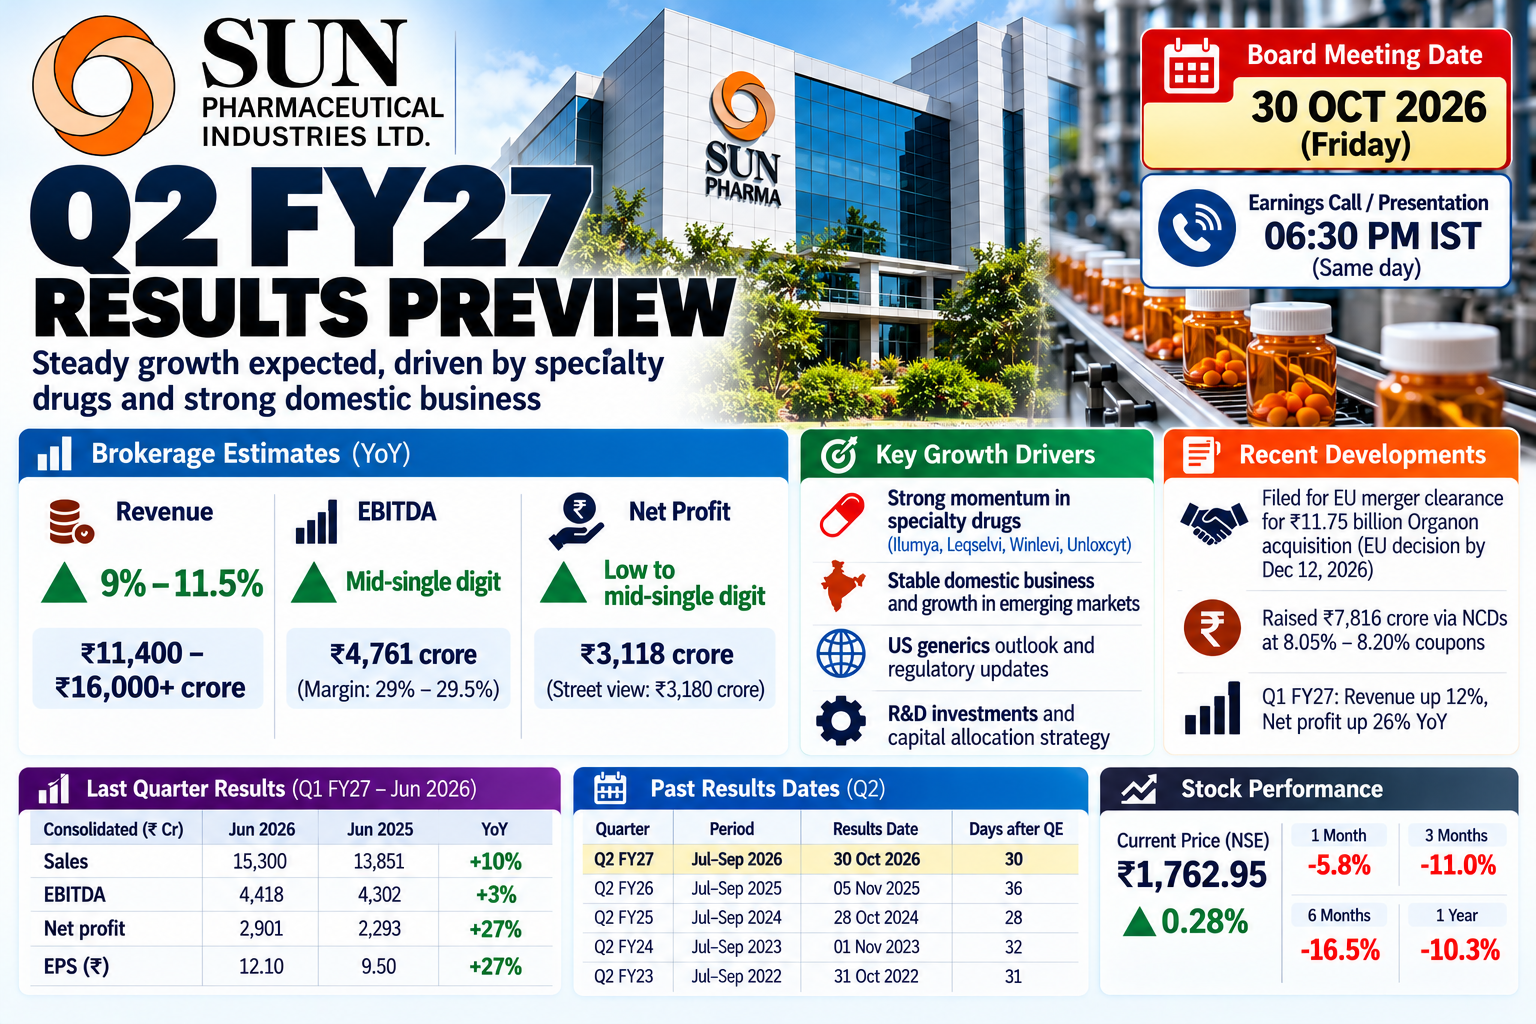
The pharmaceutical major is scheduled to announce its Q2 FY27 results on Friday, October 30, 2026. Its earnings presentation and investor call are also scheduled for the same day, with the presentation expected around 6:30 PM IST, according to the details provided.
Investors will be watching one crucial question: can Sun Pharma maintain healthy growth while protecting profitability and advancing its international expansion plans?
Track Live : Results Calendar — NSE & BSE
Sun Pharma Q2 FY27 Results: Revenue and Profit Estimates
Market estimates point to year-on-year revenue growth of approximately 9% to 11.5%. Consolidated net profit is projected at around ₹3,118 crore to ₹3,180 crore, while EBITDA is estimated at approximately ₹4,761 crore.
Operating profit margins are expected to remain around 29% to 29.5%, although research and development expenditure and input costs could create pressure.
The supplied estimates contain differing revenue figures, ranging from ₹11,400 crore to above ₹16,000 crore. These projections should be reconciled with individual brokerage reports before publication, as the difference is material.
Sun Pharma Q2 FY27 results date and earnings call details
| Event | Details |
|---|---|
| Company | Sun Pharmaceutical Industries Ltd. |
| Results | Q2 FY27, July–September 2026 |
| Board meeting date | Friday, October 30, 2026 |
| Earnings call | October 30, 2026, at 6:30 PM IST |
| Previous Q2 results | November 5, 2025 |
| Q2 FY25 results | October 28, 2024 |
Sun Pharma’s last two years of Q2 results announcement dates
| Financial quarter | Quarter ended | Results announcement date |
|---|---|---|
| Q2 FY27 | September 30, 2026 | October 30, 2026 — scheduled |
| Q2 FY26 | September 30, 2025 | November 5, 2025 |
| Q2 FY25 | September 30, 2024 | October 28, 2024 |
The historical announcement dates are consistent with the company’s press releases and exchange filings.
Sun Pharma Q2 FY27 Consensus Earnings Estimates
Brokerage estimates point to moderate revenue growth for Sun Pharmaceutical Industries in the July–September 2026 quarter, with US generics pricing pressure and higher R&D spending likely to weigh on profitability.
| Metric | Consensus / Estimate | YoY Outlook |
|---|---|---|
| Revenue | ₹15,769 crore | Up around 9% |
| EBITDA | ₹4,429 crore | Moderate growth |
| EBITDA margin | 26.3%–29.3% | Below 31.3% a year ago |
| Net profit (PAT) | ₹3,118 crore | Broadly flat YoY |
Track Live : NSE Option Chain — Live | BSE Option Chain — Live Sensex & Bankex Options Data Today
Specialty Drugs and US Generics Could Shape Sun Pharma’s Earnings
Sun Pharma’s specialty portfolio remains an important potential growth driver. Investors will monitor traction from products including Ilumya, Leqselvi, Winlevi and Unloxcyt.
The domestic formulations business is also expected to provide support, alongside growth opportunities in selected emerging markets.
In the United States, the key monitorable will be the pace of generic-drug price erosion. Updates on regulatory inspections at manufacturing facilities could also influence investor confidence.
Management commentary on research spending, specialty-drug expansion and capital allocation will help investors assess whether current investments are translating into sustainable growth.
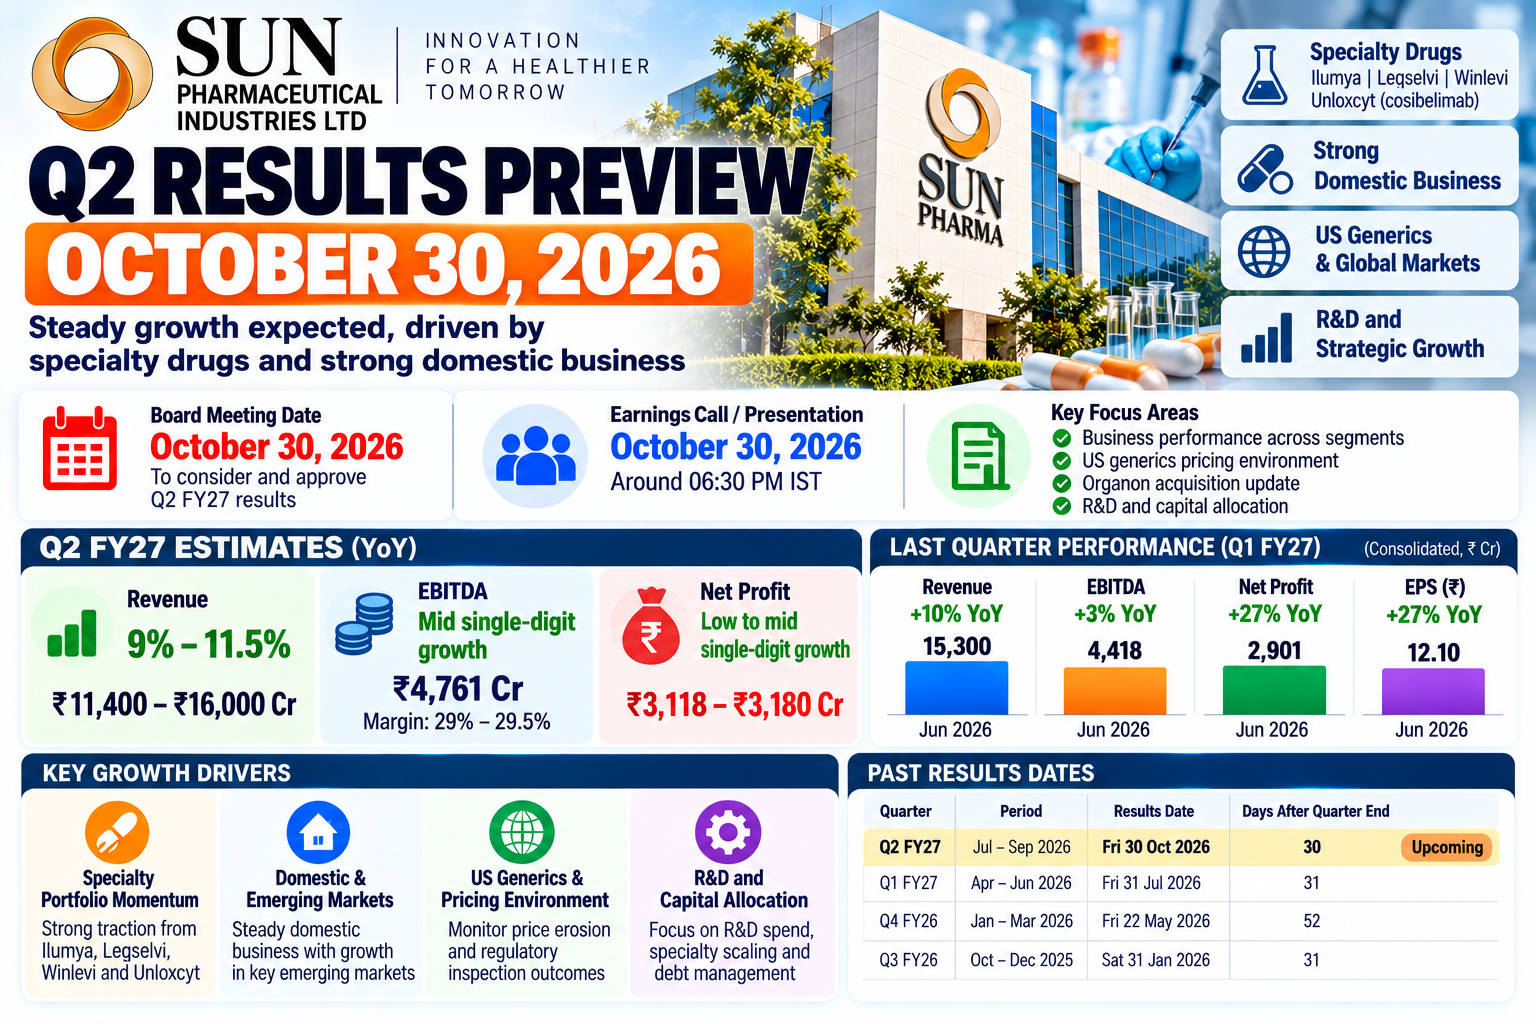
Sun Pharma: Key Pillars Monitored by Analysts
- Specialty Portfolio Momentum: Investors will track growth in Ilumya, Leqselvi and Winlevi. Unloxcyt received an updated NCCN Category 2A preferred recommendation for locally advanced cutaneous squamous cell carcinoma on October 20, 2026, potentially supporting its market positioning.
- Organon Acquisition: Sun Pharma’s proposed $11.75 billion acquisition could expand its presence in women’s health and biosimilars. The transaction remains subject to regulatory approvals and other closing conditions, with completion expected in early 2027.
- Bond Fundraising: Sun Pharma allotted ₹7,816 crore in NCDs on October 26, 2026, below its ₹10,000-crore fundraising target. The reported coupons were 8.05% and 8.20% for the respective bond tranches. Investors will monitor financing costs and capital allocation amid the planned acquisition.
- US Generics and Regulatory Oversight: Investors will monitor generic-drug pricing pressure, manufacturing-site inspection outcomes and compliance updates, as these can influence margins and earnings visibility.
Track Live : Nifty Levels Today | Sensex Levels Today
Here’s What Happened Today and Why Traders Reacted
Sun Pharma shares have remained in focus amid developments surrounding its proposed $11.75 billion acquisition of Organon. The company has reportedly filed for European Union merger clearance, with a December 12 decision deadline cited in the supplied information.
The transaction could expand Sun Pharma’s international business, but regulatory approvals, financing requirements and integration risks remain important considerations.
The company has also reportedly allotted ₹7,816 crore of non-convertible debentures at coupon rates of 8.05% to 8.20%. The reported fundraising shortfall and higher borrowing costs have added another factor for investors to monitor.
These developments do not necessarily indicate a deterioration in the company’s underlying business, but they could influence near-term sentiment and valuation.
Read More : BEL Q2 FY27 Results Oct 30: Order Book Rs 72,000 Cr, Margin in Focus
What Sun Pharma Q2 Results Could Mean for Investors
Sun Pharma’s near-term performance will depend on the balance between revenue growth, margins, specialty-drug demand and acquisition-related developments.
Results that exceed expectations, accompanied by reassuring guidance, could improve investor confidence. Conversely, higher costs, weak US generic pricing or delays in the Organon transaction could weigh on sentiment.