Hinduja Leyland Finance Merger Moves Ahead After NCLT Approval, but Auditors Flag Loan Issues
The proposed merger of Hinduja Leyland Finance (HLF) with NDL Ventures has received approval from the National Company Law Tribunal (NCLT), marking an important step towards the consolidation of the two entities. However, the transaction has encountered another challenge after auditors flagged discrepancies in loan balances and transactions across HLF’s underlying systems.
The development has brought attention to the merger process and the financial reporting of the non-banking financial company (NBFC).
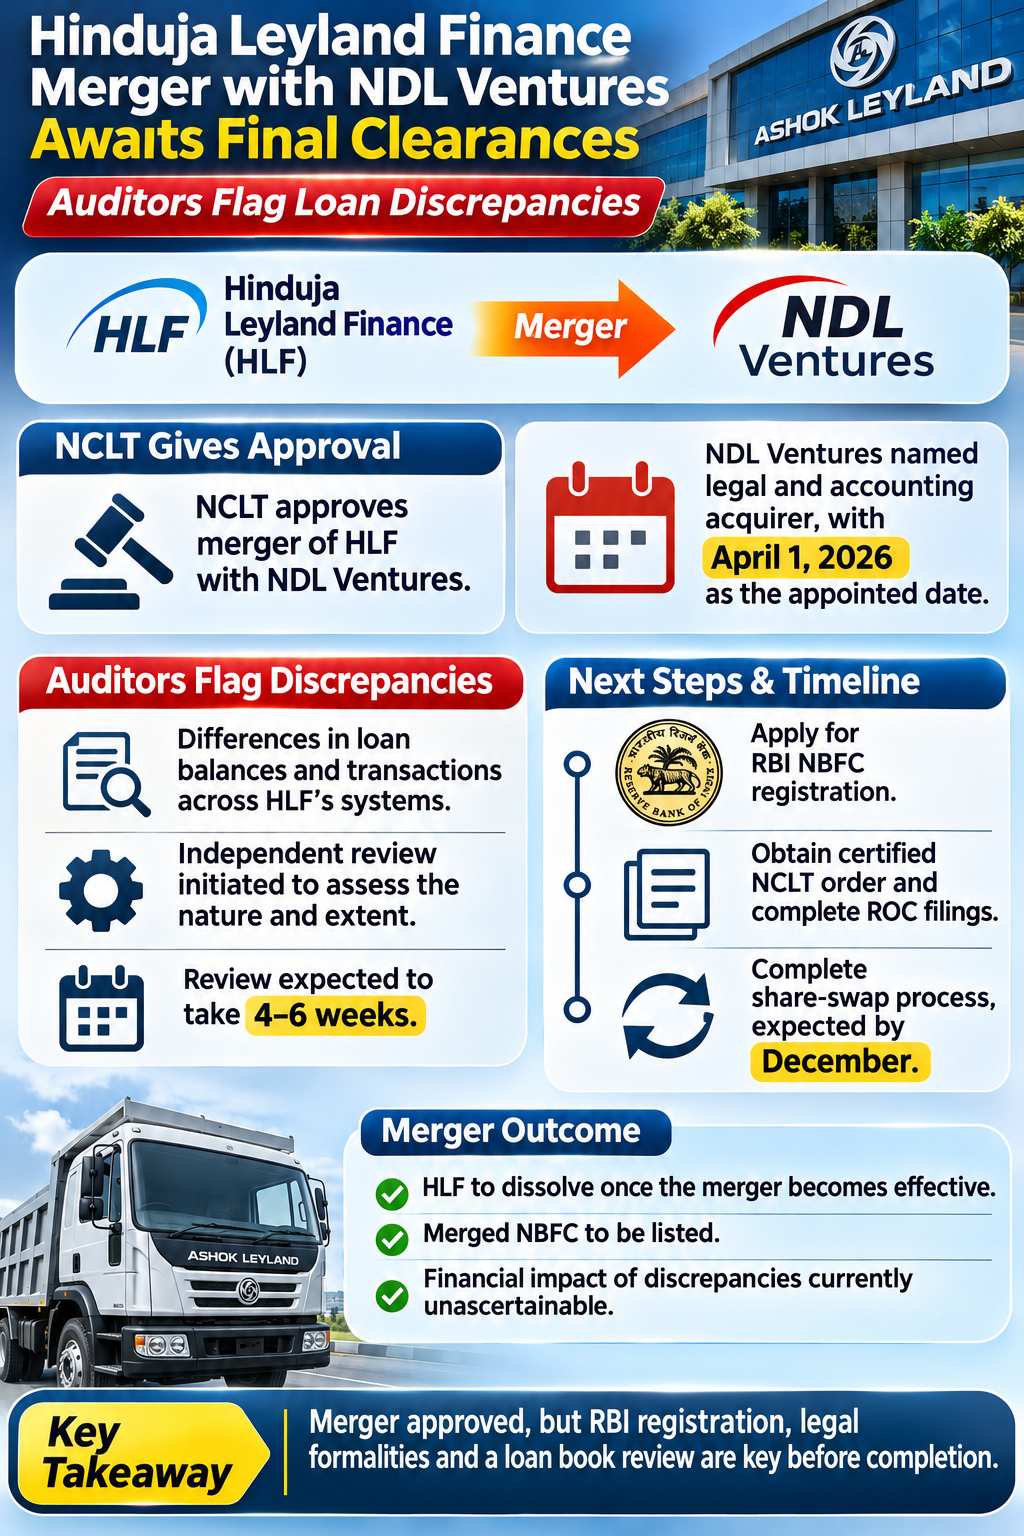
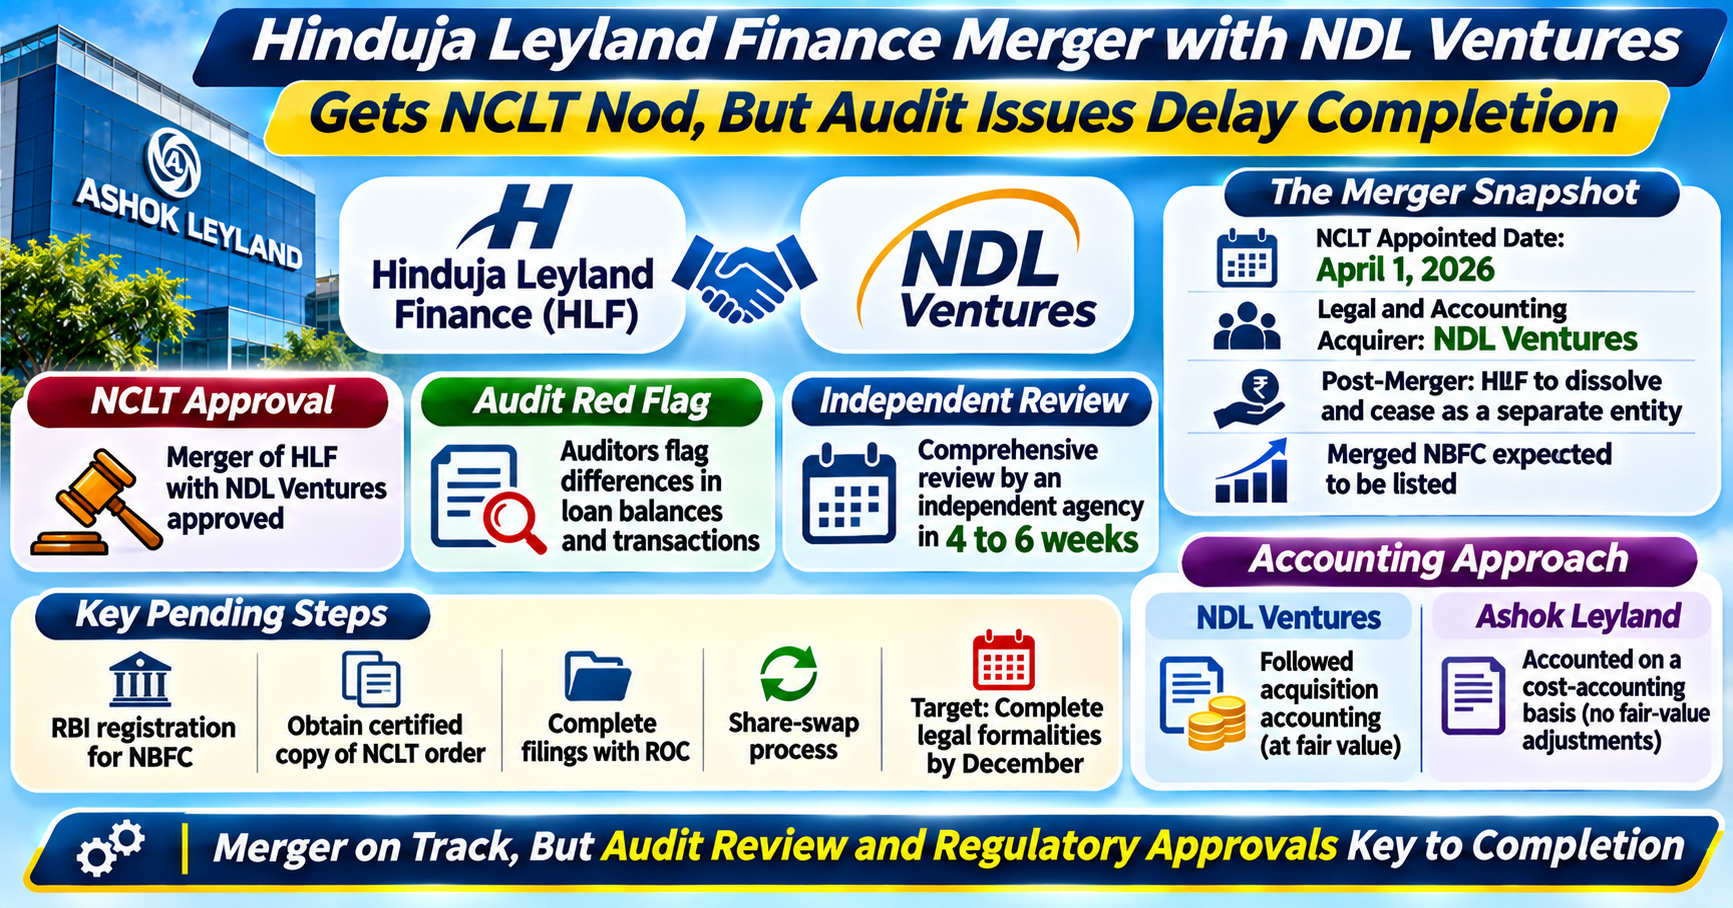
According to Ashok Leyland management, a comprehensive independent review is being planned to establish the nature and extent of the discrepancies. The exercise is expected to take four to six weeks.
Track Live : Nifty Levels Today | Sensex Levels Today | Bank Nifty Levels Today
NCLT Approves Merger, but RBI Registration and Legal Formalities Remain
The NCLT order identifies NDL Ventures as the legal and accounting acquirer of Hinduja Leyland Finance, with April 1, 2026, designated as the appointed date.
However, the merger is not yet operationally complete.
NDL Ventures must obtain registration as an NBFC from the Reserve Bank of India (RBI), secure a certified copy of the NCLT order and complete the necessary filings with the Registrar of Companies (ROC).
The share-swap process also remains pending.
During Ashok Leyland’s post-earnings analyst call on November 16, management said it hoped to complete the remaining legal formalities by the end of December, although the process could take longer.
Once the merger scheme becomes effective, HLF will dissolve as a separate entity, paving the way for the merged NBFC to be listed.
Key Merger & Audit Summary
| Aspect | Current Status & Details |
|---|---|
| NCLT Approval | Approved by the NCLT Mumbai Bench on November 3, 2026, with an appointed date of April 1, 2026. |
| Share Swap Ratio | 25 shares of NDL Ventures (face value ₹10) for every 10 shares of HLF (face value ₹10). |
| Post-Merger Ownership | Ashok Leyland’s stake will change from 61.12% in HLF to 59.64% in listed NDL Ventures. |
| Audit Findings | Joint auditors issued a disclaimer of opinion on Q2 FY27 results due to unreconciled loan balances and transactions across internal sub-systems. |
| HLF Q2 FY27 Financials | Net profit stood at ₹174.54 crore, with total assets of ₹70,403 crore, subject to the outcome of the system audit. |
The appointed date means the scheme’s accounting and legal effects are linked to April 1, subject to completion of the applicable implementation formalities.
Share-Swap Ratio: What Will HLF Shareholders Receive?
An important detail missing from the original report is the approved share-exchange ratio.
Under the merger scheme, NDL Ventures will issue:
25 fully paid-up equity shares of ₹10 each for every 10 fully paid-up equity shares of ₹10 each held in Hinduja Leyland Finance.
This means HLF shareholders will receive 2.5 NDL Ventures shares for every one HLF share, subject to the scheme’s terms.
The share-swap process has not yet been completed.
The scheme was approved by shareholders at meetings held on July 30, 2026. HLF shareholders approved it unanimously, while NDL Ventures received approval from 99.99% of the value of shareholders present and voting.
Track Live : NSE Option Chain — Live | BSE Option Chain — Live Sensex & Bankex Options Data Today
Different Accounting Treatments Raise Attention Around Merger Reporting
Another important aspect of the transaction is the difference in accounting treatment adopted by the two companies.
NDL Ventures has followed acquisition accounting in its standalone financial statements. Under this approach, HLF’s assets and liabilities, including its loan book and investments, have been recognised at fair value.
NDL Ventures also treated the NCLT order as an adjusting event in its second-quarter financial statements.
Ashok Leyland, however, has followed cost accounting in its consolidated financial statements. It has not incorporated the fair-value or purchase price adjustments recognised by NDL Ventures.
This difference is important for investors because the accounting treatment can influence how assets, liabilities and the financial impact of a merger are reflected in company statements.
Why Did Auditors Issue a Disclaimer of Opinion?
Another important detail concerns the auditors’ observations in the financial statements.
Ashok Leyland’s statutory auditors, PwC, highlighted differences in loan balances across HLF’s underlying systems.
Because the discrepancies were still being reconciled, their possible financial impact could not be reliably quantified.
Consequently, the consolidated financial results were prepared without recognising any possible impact arising from these differences.
However, the auditors also noted that, based on management’s assessment, the differences were unlikely to be significant enough to adversely affect HLF’s financial health or its ability to service debt obligations.
This distinction is important: the auditor’s qualification reflects an inability to establish the financial impact, not a conclusion that HLF is unable to meet its obligations.
Track Live : NSE F&O Lot Size | FII DII Data Today
NDL Ventures and Ashok Leyland Follow Different Accounting Treatments
The merger has also resulted in different accounting treatments in the financial statements of NDL Ventures and Ashok Leyland.
| Particulars | NDL Ventures | Ashok Leyland |
|---|---|---|
| Accounting approach | Acquisition accounting | Cost-accounting basis |
| HLF assets and liabilities | Recognised at fair value | No corresponding fair-value adjustments |
| Purchase price adjustments | Recognised | Not incorporated |
| NCLT order | Treated as an adjusting event | Consolidation follows its accounting treatment |
NDL Ventures recognised HLF’s assets and liabilities, including its loan book and investments, at fair value in its standalone second-quarter accounts.
Ashok Leyland, meanwhile, did not incorporate the fair-value or purchase-price adjustments made by NDL Ventures into its consolidated financial statements.
HLF’s Financial Position: Important Figures Investors Should Know
Hinduja Leyland Finance had assets under management of approximately ₹59,000 crore in FY26.
Its Q2 FY27 financial disclosures also provide useful context.
| Financial indicator | Reported figure |
|---|---|
| Q2 FY27 net profit | ₹174.54 crore |
| Total assets | ₹70,403 crore |
| FY26 assets under management | Approximately ₹59,000 crore |
These figures help establish the scale of the lending business undergoing the merger.
The discrepancies therefore deserve attention because they concern the underlying loan balances and transactions of a sizeable NBFC.
Read More : Nvidia Loses $2.3 Trillion From Its Peak Despite Record Sales: What Is Behind the Slide?
Independent System Audit Expected to Take Four to Six Weeks
To investigate the issue, HLF’s board has initiated a system audit and is in the process of appointing an independent agency.
The review will examine the company’s systems and processes to identify the nature and extent of the discrepancies.
Management expects the exercise to take approximately four to six weeks.
“In the absence of such a review, it would not be possible for us to say what is the amount involved here,” Agarwal said.
The statement explains why auditors issued a disclaimer of opinion, as the financial implications could not be established without further verification.
The company will evaluate the findings after the independent review and take appropriate action.
Here’s What Happened Today and Why Traders Reacted
The merger approval is a positive procedural development for the consolidation of Hinduja Leyland Finance and NDL Ventures.
However, the auditors’ observations have introduced uncertainty around the accuracy of HLF’s loan balances and the financial implications of the merger.
For investors tracking Ashok Leyland and the proposed NBFC listing, the key concern is whether the independent review identifies material discrepancies that require adjustments or corrective action.
What Should Ashok Leyland and NDL Ventures Investors Watch Next?
Investors should closely monitor three developments: completion of RBI registration, finalisation of the share-swap process and findings of the independent system audit.
The four-to-six-week review will be particularly important because the financial impact of the discrepancies has not yet been quantified.
A satisfactory review could provide greater clarity on HLF’s loan book and support the merger process. However, material findings could lead to accounting adjustments, additional disclosures or further delays.