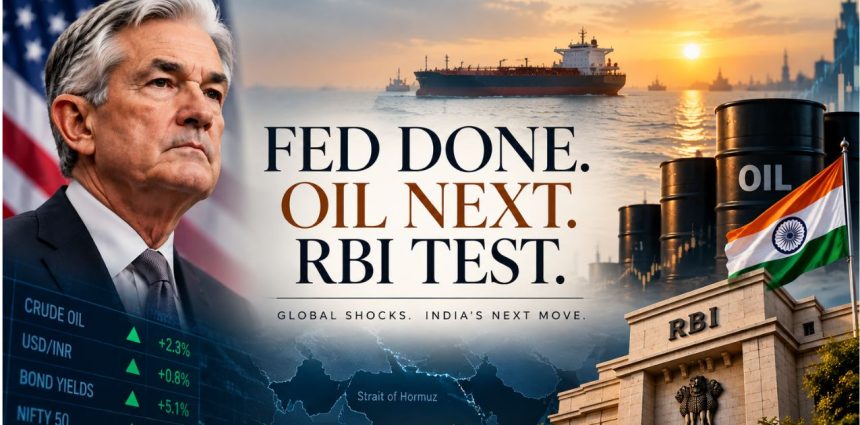
Somewhere off the coast of Iran, a shipping lane most Indians have never had reason to think about is quietly doing more to your fuel bill than the US Federal Reserve ever could.
Here’s what most coverage is still getting wrong this week: the Fed’s rate decision isn’t breaking news anymore. It happened seven days ago, on September 16, and markets absorbed it within a single trading session.
What’s actually been moving the rupee, India’s bond yields, and its inflation prints since then isn’t a press conference in Washington; it’s a live, still-unfolding Gulf oil shock that has spent the past month pushing Brent crude towards $110 a barrel, then pulling it back towards $98 as a damaged Saudi pipeline comes back online.
Whether that de-escalation holds over the next two weeks could be an important factor for India’s next rate decision, alongside domestic inflation, growth and financial conditions.
The Fed Already Pulled the Trigger — Here’s What’s Changed Since
The Federal Reserve’s rate decision has already happened. On September 16, the FOMC under Chair Kevin Warsh voted unanimously to raise the federal funds rate by 25 basis points to a target range of 3.75%–4%, the central bank’s first rate increase in more than three years. The move had been telegraphed for weeks, so the announcement itself barely moved markets.
What matters now, a week later, is what comes next. The Fed’s updated projections show a committee that isn’t done: on the 2027 rate path, eight officials pointed towards another increase, six favoured holding steady, and four saw room for cuts, with 18 officials submitting projections in total.
Separately, 16 of those 18 policymakers expected at least one more 25-basis-point hike before the end of 2026. The US 10-year Treasury yield touched 5% in the days after the decision, a level last seen in 2007, before easing to just under 5% as of September 22.
Two regional Fed presidents have since kept the hawkish tone alive: Chicago Fed’s Austan Goolsbee said the central bank cannot overlook persistent supply shocks, while St. Louis Fed’s Alberto Musalem said further hikes may be needed to bring inflation back to target.
For India, the Fed decision itself is now a settled fact. The live question is how much further US rates and yields still have to climb, and that increasingly depends on something the Fed doesn’t control.
Also Read: Inflation Bites as Fed Raises Rates by 25 bps; RBI Seen Hiking Repo Rate to 5.75% by FY27
The Real Story Isn’t the Fed. It’s the Gulf Oil Shock.
The oil price spike that’s rattled Indian markets this month has less to do with US monetary policy than with damaged infrastructure and shipping risk in the Gulf.
Drone attacks forced Saudi Arabia to shut its East-West Pipeline around September 11–13, halting crude loadings at the kingdom’s Yanbu port and pushing Brent towards $108 as the kingdom’s main workaround for the Strait of Hormuz went offline.
That picture has since moved twice. First came diplomatic signals: at the UN, President Trump said he faced a “big decision” on whether to pursue a deal with Iran or escalate further, while Iranian officials indicated Tehran would reopen the Strait of Hormuz to shipping within seven days if the US eased its blockade.
Then, on September 22, Saudi Arabia actually restarted the East-West Pipeline, running at a low rate for now, with Aramco targeting a return to its normal 4 million barrels a day, though a full restart could take six to eight weeks. Brent fell more than $2 a barrel on the news to $97.81, its lowest in two weeks. Even with the pullback, Brent remains up nearly 46% from a year ago.
This is the context Delhi has been navigating for months, not just this week. The RBI’s August policy statement explicitly flagged renewed tensions in West Asia, volatile crude prices, an uneven monsoon under El Niño conditions, and global trade uncertainty as key risks to growth and inflation, with West Asia sitting alongside other worries, not necessarily above the Fed, but treated by the central bank as a live and direct threat to its own outlook well before this week’s headlines.
The Rupee Is Under Siege — But RBI Just Rebuilt Its War Chest
The rupee has spent the past week hovering in a tight, weak band, trading around 95.6–96.1 to the dollar and down about 10.7% over the past 12 months, though still off its all-time weak point.
That record was set on May 20, 2026, when the rupee touched roughly 96.9 to the dollar, driven by a lingering US tariff overhang, sustained foreign portfolio outflows, and an earlier spike in oil prices tied to the same Strait of Hormuz standoff.
What’s changed since then is India’s ability to defend the current level. Foreign exchange reserves jumped a record $44.9 billion in a single week to touch $785.71 billion for the week ended September 4, the highest level on record, and the surge pushed India past Russia to become the world’s fourth-largest reserve holder. But the mechanics behind that number are the real story.
The RBI turned to India’s 35-million-strong diaspora, nudging banks to raise foreign-currency deposits and absorbing the currency-hedging costs itself, the same playbook it used during the 2013 taper tantrum.
The scheme drew $127.2 billion through FCNR(B) deposits and $136.4 billion in total inflows by August 31, arriving so much faster than expected that the RBI closed the window a month ahead of its original September 30 deadline.
That war chest looks less like comfortable surplus and more like a rebuild once you see where reserves stood just two months earlier: reserves had fallen to $682 billion in late July, having been depleted by $46 billion amid an earlier flare-up of the same conflict, before the diaspora scheme clawed the buffer back to a record.
The RBI has already fought and won one round of rupee defense this year using largely the same geopolitical trigger that’s back in play now.
Also Read: RBI Closed FCNR(B) Window as Inflows Surged Beyond Expectations
Inflation Is the RBI’s Real Headache
Two separate inflation gauges are moving in the wrong direction at once. Retail inflation rose to 4.82% in August from 4.45% in July, a steady climb from 2.74% in January, and now the third straight month above the RBI’s 4% target and the highest reading since December 2024.
Wholesale prices are running even hotter. WPI inflation climbed to 9.92% in August from 9.78% in July, keeping wholesale inflation near or above 9.5% for a fourth straight month, a sharp reversal from the near-zero and negative readings of a year earlier.
The driver is unmistakable: inflation in mineral oils jumped to 38.48% and crude petroleum and natural gas prices rose 34.41% year-on-year, directly tracking the Brent spike. Oil isn’t just a rupee problem for India right now, it’s showing up in the price data the RBI is legally mandated to control.
Bond Yields Are in a Tug of War
Indian government bonds are being pulled in two directions simultaneously. The 10-year G-Sec yield breached 7% for the first time since early June, as the RBI’s ₹1 trillion bond-sale program, elevated global yields, and growing expectations of monetary tightening weighed on demand.
Those sales are a direct consequence of the FCNR success: the RBI sold the first ₹500 billion tranche on September 17, with ₹250 billion sold on September 21 and another ₹250 billion scheduled for September 28, to drain the surplus liquidity created by the diaspora deposit scheme, its first net bond sale in nine years.
Since the first tranche, yields have eased modestly as softer crude and lower US Treasury yields provided mild relief, even as growing bets on an October RBI hike limit how far yields can fall. Bond traders now widely expect the RBI to follow through with a 25-basis-point hike at the October policy review.
Markets Held Their Ground. Foreign Investors Didn’t.
Indian equities didn’t panic on the Fed decision, but they didn’t rally either. The day after the hike, the Sensex climbed as much as 341 points intraday to 74,677.56 before giving it all back, closing down 21.86 points at 74,314.59.
The Nifty fared slightly better, touching 23,325 intraday before settling up 53 points at 23,270.60. The steadier tone came from realty, pharma and auto stocks, while banking names lagged, a sign the market was digesting the hike rather than cheering it, helped along by cooling crude and a large NSE IPO drawing fresh liquidity.
The more telling split is between foreign and domestic money. Foreign portfolio investors had returned as modest buyers in July and August but resumed selling in September, NSDL data showed FPI outflows of roughly ₹23,676 crore through exchanges as of September 19, with FIIs remaining net sellers through every completed week of the month so far.
Financial services alone has absorbed over ₹1 lakh crore in FII outflows since January, the single largest sectoral drag. What’s kept indices from cracking is domestic buying: DIIs remained net buyers throughout September, limiting the market’s fall even as foreign selling continued.
TRACK HERE: GIFT NIFTY, NIFTY50, SENSEX, FII DII DATA | NIFTYTRADER
GDP Growth Is India’s Cushion — But Not Without Pushback
The one clearly positive data point in this picture is growth. India’s real GDP expanded 7.8% year-on-year in the April-June quarter, comfortably beating the RBI’s 7% forecast, powered by 9.2% manufacturing growth, 10% services growth, and an 11.9% jump in investment.
It isn’t an uncontested number, though. Congress leader Jairam Ramesh argued the headline figure masks weaker private investment sentiment, falling household savings, rising household debt, and a widening trade deficit with China, worth weighing against how much real cushion the growth story provides against the external shocks above.
What Happens Next: Two Scenarios for October
Two dates now matter more than the Fed meeting that already happened. The RBI’s MPC meets October 5–7, and the Fed’s next decision lands October 27–28.
Scenario one — de-escalation holds. The Saudi pipeline restart is the first concrete step in this direction. If it ramps towards full capacity without incident and Iran’s Hormuz offer firms up, Brent could settle closer to $90–95, easing pressure on the rupee, bond yields and imported inflation simultaneously. The RBI’s neutral stance likely survives October intact.
Scenario two — the disruption isn’t over. The pipeline is still running well below capacity, and a full restart is six to eight weeks out, leaving a real window for renewed strikes, a slower-than-expected ramp-up, or a stalled Hormuz negotiation to send Brent back above $105–110.
Axis Capital has already flagged the possibility of up to 50 basis points of RBI tightening split across the October and December meetings, capping the overall hiking cycle at 75 basis points, a view not everyone shares.
Ventura’s Vinit Bolinjkar, for instance, still expects an October hold, just with a noticeably more hawkish tone from the RBI. Either way, it would mark the RBI’s first serious tightening debate in years, a sharp reversal from the rate-cut narrative that dominated earlier in 2026.
Key Numbers at a Glance
| Metric | Latest Reading | Context |
|---|---|---|
| US Fed funds rate | 3.75%–4.00% | Up 25 bps on Sept 16; first hike since 2023 |
| US 10-year Treasury yield | ~4.93%–4.98% | Touched 5% intraday, highest since 2007 |
| Brent crude | ~$97.81/barrel | Down from ~$108 peak; still up ~46% YoY |
| USD/INR | ~95.6–96.1 | Off its all-time low of ~96.9 (May 20, 2026) |
| India 10-year G-Sec yield | Breached 7% | First time since early June 2026 |
| India retail CPI (Aug) | 4.82% | Up from 2.74% in January; 3rd month above 4% target |
| India WPI (Aug) | 9.92% | 4th straight month near/above 9.5% |
| India GDP (Q1 FY27) | 7.8% | Beat RBI’s 7% forecast |
| RBI repo rate | 5.25% | Held for 4 straight MPC meetings |
| India forex reserves | $785.7 billion | All-time record, week ended Sept 4 |
| FII net flow (Sept, thru Sept 19) | ~-₹23,676 crore | Reverses July-Aug inflows |
Policy Calendar
| Event | Date | Status |
|---|---|---|
| Fed rate decision | September 16, 2026 | Already happened — 25 bps hike |
| RBI MPC meeting | October 5–7, 2026 | Upcoming — hike odds rising |
| Next Fed FOMC meeting | October 27–28, 2026 | Upcoming |
The Number That Will Move Before the Fed Does Again
Before the Fed meets again on October 27, India will already have its answer. The RBI’s October 5–7 meeting comes first, and Governor Sanjay Malhotra will be looking at the same Brent print, the same near-96 rupee, and the same 9.92% wholesale inflation number every trader on Dalal Street is already watching.
If the Saudi pipeline ramps up cleanly and oil stays anchored below $100, this Fed hike quietly becomes a non-event for India, priced in, absorbed, and forgotten within a month.
If the repair proves slower or shakier than expected, October 7 could mark this cycle’s first RBI rate hike, a move few were pricing in as recently as August. Either way, the number that decides it won’t come from a Fed press conference. It’ll come from a pipeline in the Saudi desert that’s still running at a fraction of capacity, and that story is still being written.
Read Next: Stocks To Watch, Sept 23: Persistent-Nagarro, Tata Sons, HDFC Bank